
Collagen Dressings Market Overview:
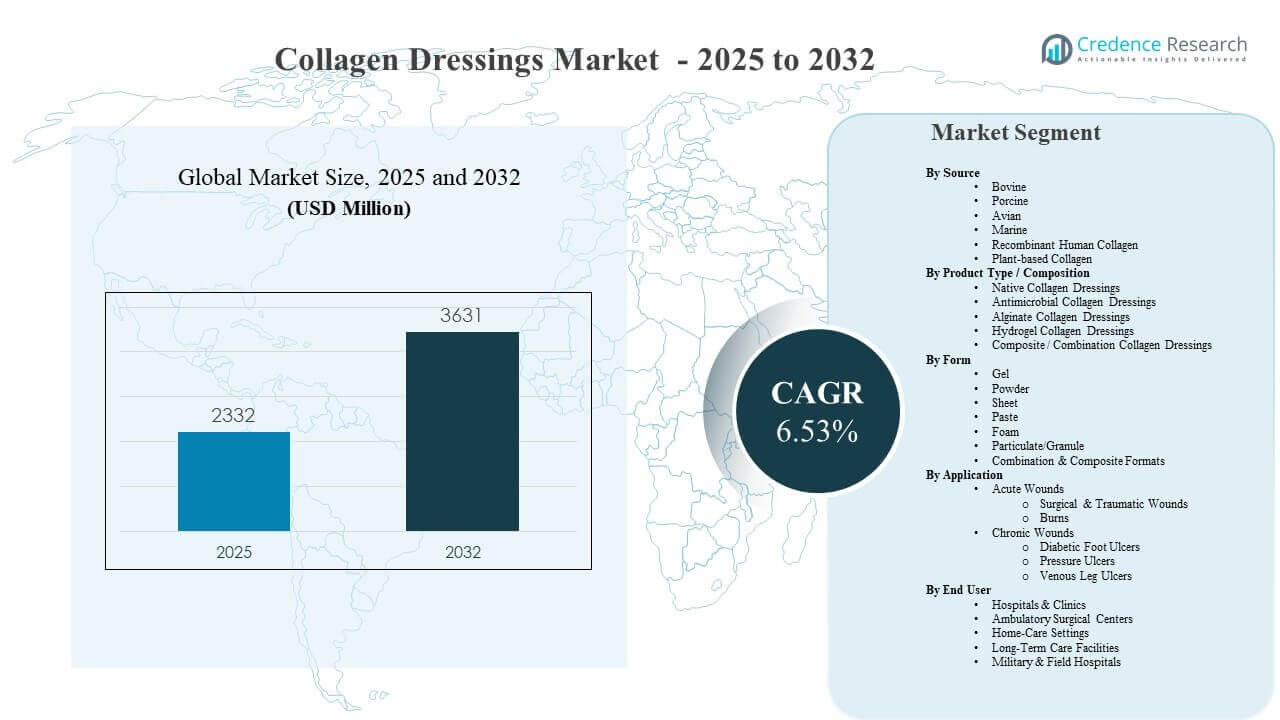
The global Collagen Dressings Market size was estimated at USD 2,332 million in 2025 and is expected to reach USD 3,631 million by 2032, growing at a CAGR of 6.53% from 2025 to 2032. Growth momentum is anchored in rising clinical demand for advanced wound management that supports granulation, maintains a controlled healing environment, and reduces complications in hard-to-heal wounds. Demand expansion is reinforced by protocol-driven adoption across acute care, outpatient settings, and home-care models where faster closure and lower treatment burden remain central objectives.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Collagen Dressings Market Size 2025 | USD 2,332 million |
| Collagen Dressings Market, CAGR | 6.53% |
| Collagen Dressings Market Size 2032 | USD 3,631 million |
Key Market Trends & Insights
- The Collagen Dressings Market advances at a 6.53% CAGR (2025–2032), reflecting sustained conversion from basic dressings to advanced wound care.
- North America accounted for 39.60% of 2025 revenue, supported by broad availability of advanced wound care products and structured clinical pathways.
- Europe represented 26.90% of 2025 revenue, reflecting mature adoption across hospitals, outpatient care, and long-term care systems.
- Bovine source held 36.90% share in 2025, supported by established clinical familiarity and large-scale supply chains.
- Acute wounds captured 56.70% share in 2025, sustained by surgical volumes, trauma care protocols, and standardized inpatient dressing utilization.
Segment Analysis
Collagen dressings are positioned within advanced wound care due to collagen’s role in supporting the wound bed environment and enabling consistent clinical workflows across different care settings. Purchasing decisions are shaped by clinical evidence, ease of use, wear time, compatibility with adjunct therapies, and supply reliability across multi-site provider networks. Product selection also aligns with wound type and severity, including exudate levels, depth, and infection risk factors that influence whether antimicrobial or combination formats are prioritized.
Adoption patterns increasingly align with care pathway standardization and the expansion of outpatient and home-care delivery models. Hospitals and clinics remain central for higher-acuity wounds and post-operative management, while ambulatory and home-care settings influence demand for simplified application, predictable wear time, and reduced dressing-change burden. Across regions, utilization intensity is influenced by reimbursement depth, availability of specialized wound clinics, and the scale of chronic disease-driven wound incidence.
By Source Insights
Bovine accounted for the largest share of 36.90% in 2025. Bovine-derived collagen remains widely used because clinical familiarity supports consistent selection in institutional procurement and established supply chains support predictable availability. Manufacturer portfolios commonly emphasize standardized formats and broad indications that fit routine protocols. Increasing scrutiny around traceability and sourcing is also shaping portfolio strategies, supporting ongoing differentiation through quality systems and documentation.
By Product Type / Composition Insights
Product mix across collagen dressing compositions is shaped by infection risk management, exudate control requirements, and clinical preferences for combination dressings that simplify treatment steps. Antimicrobial collagen dressings remain important in clinical settings where microbial load and biofilm concerns are common, particularly for chronic wounds. Alginate-collagen and hydrogel-collagen combinations address moisture balance and absorption needs across heterogeneous wound profiles. Composite designs also support workflow efficiency by reducing the number of products required across dressing changes.
By Form Insights
Gel accounted for the largest share of 30.60% in 2025. Gel formats are frequently selected for conformability and coverage in irregular wound geometries, supporting wound bed contact and manageable application in clinical workflows. Gel utilization is also supported by settings where cavity filling and localized coverage are prioritized. Manufacturers focus on handling characteristics and compatibility with adjunct modalities to maintain clinical preference across diverse indications.
By Application Insights
Acute Wounds accounted for the largest share of 56.70% in 2025. Acute wound demand is supported by surgical procedures and trauma care protocols that require predictable dressing performance and standardized use. Clinical pathways favor products that maintain a stable wound environment and reduce complication risks during recovery. Acute care settings also benefit from established procurement and formulary processes that scale utilization across high-volume departments.
By End User Insights
Hospitals and clinics remain the primary adoption centers due to higher-acuity wound management needs and standardized post-operative pathways. Ambulatory surgical centers support incremental demand as procedure migration expands outpatient volumes and accelerates needs for efficient, easy-to-apply dressing systems. Home-care settings strengthen demand for user-friendly formats that reduce dressing changes and support continuity of care after discharge. Long-term care facilities contribute demand linked to pressure ulcer prevention and management, while military and field hospitals emphasize portability, reliability, and rapid deployment use cases.
Collagen Dressings Market Drivers
Rising chronic wound burden and comorbidity-linked wounds
The Collagen Dressings Market is propelled by increasing incidence of chronic wounds associated with diabetes, vascular disease, and aging populations. Longer treatment durations for chronic wounds elevate cumulative dressing consumption and intensify the need for advanced products that support closure and complication reduction. Provider systems also emphasize wound management standardization to reduce readmissions and infection risk. Collagen-based solutions benefit from clinical acceptance as part of advanced wound care pathways in complex wounds.
- For instance, Integra LifeSciences' Omnigraft Dermal Regeneration Matrix demonstrated in its FDA-pivotal clinical study that 51% of diabetic foot ulcer patients achieved complete ulcer healing at 16 weeks, compared to 32% among patients receiving standard care alone a statistically significant advantage that reinforced its adoption in chronic wound protocols across diabetic care settings.
Procedure volumes and protocol-based post-operative care
Surgical and trauma volumes sustain strong baseline demand for collagen dressings in acute wound management. Post-operative care pathways prioritize consistent wound coverage, controlled healing environments, and predictable handling characteristics that fit clinical workflows. Hospitals and outpatient centers adopt advanced dressings to support recovery and reduce treatment burden. Collagen dressings also benefit from integration with broader advanced wound care toolkits used across surgical specialties.
Expansion of outpatient care and home-care delivery models
Care delivery shifts increase demand for dressings that reduce change frequency and simplify application across non-specialist settings. Ambulatory settings favor products that support quick turnover and standardized application, strengthening utilization where protocols prioritize efficiency. Home-care settings increase the value of intuitive formats that reduce caregiver burden and support adherence. Manufacturer investments in user-centric packaging and guidance reinforce adoption across distributed care environments.
- For instance, MiMedx's HELIOGEN bovine-derived fibrillar collagen matrix, evaluated in a 2025 case series by Boynton et al. in stage 3 pressure injuries, achieved complete wound closure in all patients within 27 to 52 days from a single application with individual wounds recording up to 98% area reduction by day 14 reinforcing its suitability for home and non-specialist care settings where minimal reapplication is a clinical priority.
Product innovation and portfolio differentiation in advanced wound care
Competitive differentiation supports growth through continuous upgrades in composite designs, antimicrobial integration, and format optimization. Portfolios increasingly target clinical workflow needs, including improved conformability, handling, and compatibility with adjunct therapies. Evidence generation and clinician education reinforce adoption, particularly in complex chronic wounds where outcomes drive product selection. Supply reliability and standardized SKUs also strengthen vendor positioning in large provider networks.
Collagen Dressings Market Challenges
The Collagen Dressings Market faces constraints from pricing pressure and formulary controls, particularly in systems where reimbursement and procurement emphasize cost containment. Clinical decision-makers often require strong evidence packages, creating adoption hurdles for newer compositions without robust outcomes data. Variation in wound care protocols across sites can slow standardization and limit rapid conversion from basic dressings. Supply chain complexity and sourcing scrutiny can also elevate compliance requirements and documentation burdens.
- For instance, 3M's Promogran Prisma a collagen/oxidized regenerated cellulose (ORC) matrix demonstrated per-patient dressing costs of $561.48 versus $2,577.65 under standard care in a controlled analysis, a compelling cost-reduction profile.
Market participation is further shaped by product differentiation complexity across similar formats and overlapping clinical claims. Provider training requirements, handling preferences, and workflow fit influence switching barriers and can reduce the pace of conversion in busy clinical settings. Quality assurance expectations remain stringent, and any manufacturing variability can affect buyer confidence and vendor qualification. Competitive intensity also increases promotional noise, raising the importance of credible evidence and consistent performance.
Market Trends and Opportunities
Care pathway integration is emerging as a key trend, with advanced wound care increasingly managed through standardized protocols that align products with wound types and risk profiles. Opportunities expand for combination dressings that reduce treatment steps and simplify decision-making in outpatient and home-care environments. Digital enablement and patient-support tools also create differentiation by improving compliance and continuity of care after discharge. Portfolio extensions that align with prevention protocols, particularly for pressure injury prevention, strengthen high-volume use cases.
- For instance, Mölnlycke Health Care demonstrated that standardizing wound care protocols and products around its Mepilex® Border Flex dressing improved 16-week healing rates from 48% to 88% at a wound care center.
Innovation is also shifting toward formats that optimize wear time, handling, and compatibility with adjunct therapies to reduce clinician workload. Supplier strategies increasingly emphasize traceability and sourcing transparency to meet procurement expectations in regulated markets. Emerging opportunities include targeted offerings for ambulatory and long-term care settings where prevention and maintenance protocols drive recurring demand. Regional expansion also supports growth as advanced wound care penetration rises with improving healthcare access.
Regional Insights
North America
North America led the Collagen Dressings Market in 2025 with 39.60% revenue share, supported by strong adoption of advanced wound care, broad product availability, and established clinical protocols across acute and chronic wound pathways. Provider systems emphasize standardization and outcomes-driven purchasing, reinforcing demand for evidence-backed collagen formats. Outpatient expansion and home-care models further strengthen demand for simplified dressing systems that reduce treatment burden and support continuity after discharge.
Europe
Europe accounted for 26.90% of 2025 revenue, reflecting mature advanced wound care adoption across hospitals, outpatient care, and long-term care facilities. Procurement emphasizes performance, safety, and value, supporting steady utilization across both prevention and treatment pathways. Clinical practice patterns favor standardized product sets in many systems, sustaining demand for reliable formats and combination designs aligned with local reimbursement and tender structures.
Asia Pacific
Asia Pacific represented 23.10% share in 2025, supported by expanding access to advanced wound care, rising chronic disease prevalence, and improving wound care infrastructure in key markets. Growth is reinforced by increasing hospital capacity, expanding outpatient care models, and broader adoption of advanced dressings in specialized wound clinics. Product penetration remains influenced by pricing sensitivity and uneven reimbursement coverage, creating opportunities for scalable formats and portfolio localization.
Latin America
Latin America held 6.80% share in 2025, supported by improving access to advanced wound care in larger healthcare systems and growing awareness of chronic wound management. Adoption is shaped by reimbursement variability and procurement constraints, which can moderate conversion rates from basic to advanced dressings. Growth opportunities strengthen where private care networks expand specialized wound services and where standardized protocols increase advanced dressing utilization.
Middle East & Africa
The Middle East and Africa contributed 3.60% share in 2025, with demand concentrated in higher-capacity care centers and private healthcare networks. Adoption is supported by modernization initiatives and expanding specialized care capabilities in select markets. Market development remains constrained by uneven access, limited specialist coverage in parts of the region, and variable reimbursement depth, sustaining a smaller base relative to North America, Europe, and Asia Pacific.
Competitive Landscape
Competition in the Collagen Dressings Market is shaped by portfolio breadth, clinical evidence packages, and differentiated positioning across infection management, exudate control, and workflow efficiency. Vendors compete on product performance, handling characteristics, wear time, and the ability to integrate with standardized wound care protocols across diverse care settings. Contracting strength, supply reliability, and training support also influence purchasing decisions, particularly among multi-site provider networks and systems focused on clinical pathway consistency.
Solventum competes through advanced wound care portfolio capabilities and workflow-oriented product design that supports adoption across hospital, outpatient, and home-care environments. Product strategy focuses on simplifying application steps, improving usability, and supporting consistent protocol alignment in high-volume use cases. Commercial execution is reinforced by relationships with provider systems and channel reach that supports broader clinical adoption. Portfolio updates also reflect competitive pressure to improve wear time, handling, and overall treatment efficiency.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Solventum
- Smith+Nephew
- ConvaTec Group
- McKesson Medical-Surgical
- DermaRite Industries
- Human BioSciences
- MPM Medical
- Integra LifeSciences
- Coloplast
- Mölnlycke Health Care
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In July 2024, MIMEDX announced the commercial launch of HELIOGEN™ Fibrillar Collagen Matrix, a 510(k)-cleared bovine-derived collagen product designed for complex wounds, especially in surgical settings. The company said the launch expanded its wound and surgical portfolio with its first xenograft collagen offering.
- In November 2024, RTI Surgical completed its acquisition of Collagen Solutions, a global supplier of engineered medical-grade collagen and xenograft tissue. RTI said the deal broadened its biomaterials portfolio and increased its capabilities across regenerative medicine applications, including wound-related solutions.
- In March 2025, BioLab Holdings, Inc. announced a partnership and collaboration agreement with Real Collagen GmbH to develop new wound care products using fish collagen. BioLab stated that the partnership would help expand its wound care portfolio, while Real Collagen would contribute its fish-collagen hydrogel material designed for wound dressing applications.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 2,332 million |
| Revenue forecast in 2032 | USD 3,631 million by 2032 |
| Growth rate (CAGR) | 6.53% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Source Outlook: Bovine, Porcine, Avian, Marine, Recombinant Human Collagen, Plant-based Collagen; By Product Type / Composition Outlook: Native Collagen Dressings, Antimicrobial Collagen Dressings, Alginate Collagen Dressings, Hydrogel Collagen Dressings, Composite / Combination Collagen Dressings; By Form Outlook: Gel, Powder, Sheet, Paste, Foam, Particulate/Granule, Combination & Composite Formats; By Application Outlook: Acute Wounds (Surgical & Traumatic Wounds, Burns), Chronic Wounds (Diabetic Foot Ulcers, Pressure Ulcers, Venous Leg Ulcers); By End User Outlook: Hospitals & Clinics, Ambulatory Surgical Centers, Home-Care Settings, Long-Term Care Facilities, Military & Field Hospitals |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Solventum, Smith+Nephew, ConvaTec Group, McKesson Medical-Surgical, DermaRite Industries, Human BioSciences, MPM Medical, Integra LifeSciences, Coloplast, Mölnlycke Health Care |
| No. of Pages | 338 |
Segmentation
By Source
- Bovine
- Porcine
- Avian
- Marine
- Recombinant Human Collagen
- Plant-based Collagen
By Product Type / Composition
- Native Collagen Dressings
- Antimicrobial Collagen Dressings
- Alginate Collagen Dressings
- Hydrogel Collagen Dressings
- Composite / Combination Collagen Dressings
By Form
- Gel
- Powder
- Sheet
- Paste
- Foam
- Particulate/Granule
- Combination & Composite Formats
By Application
- Acute Wounds [Surgical & Traumatic Wounds, Burns]
- Chronic Wounds [Diabetic Foot Ulcers, Pressure Ulcers, Venous Leg Ulcers]
By End User
- Hospitals & Clinics
- Ambulatory Surgical Centers
- Home-Care Settings
- Long-Term Care Facilities
- Military & Field Hospitals
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Collagen Dressings Market and the expected size by 2032?
What is the CAGR for the Collagen Dressings Market during 2025–2032?
Which segment holds the largest share in the Collagen Dressings Market?
What factors are driving growth in the Collagen Dressings Market?
Who are the leading companies in the Collagen Dressings Market?
Which region leads the Collagen Dressings Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 2,332 million → 2032: USD 3,631 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Collagen Dressings Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Collagen Dressings Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Collagen Dressings Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Collagen Dressings Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Collagen Dressings Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Collagen Dressings Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Collagen Dressings Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Collagen Dressings Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 2,332 million → 2032: USD 3,631 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Collagen Dressings Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Collagen Dressings Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Collagen Dressings Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Collagen Dressings Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

