
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Colombia Contract Pharmaceutical Manufacturing Market Size 2023 | USD 736.63 Million |
| Colombia Contract Pharmaceutical Manufacturing Market, CAGR | 6.99% |
| Colombia Contract Pharmaceutical Manufacturing Market Size 2032 | USD 1,353.75 Million |
Market Overview
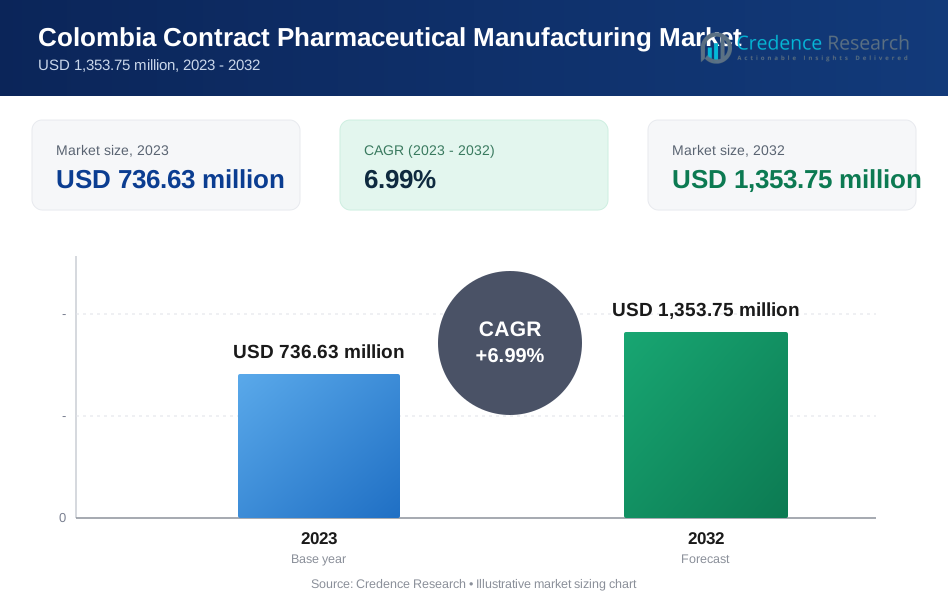
The Colombia Contract Pharmaceutical Manufacturing Market is expected to grow from USD 736.63 million in 2023 to USD 1,353.75 million by 2032, with a CAGR of 6.99%.
The Colombia Contract Pharmaceutical Manufacturing market is driven by the increasing demand for cost-effective drug production and the country’s strategic location as a key player in Latin America’s healthcare sector. Pharmaceutical companies are seeking to optimize their operations by outsourcing manufacturing to contract service providers, allowing them to focus on R&D and distribution. Additionally, Colombia’s favorable regulatory environment and skilled workforce contribute to its appeal for both local and international pharmaceutical companies. The market is also benefiting from the growing trend of personalized medicine, which requires flexible and efficient manufacturing processes. Furthermore, the rising adoption of biologics and biosimilars is creating new opportunities for contract manufacturers to expand their capabilities. As the healthcare industry continues to evolve, advancements in technology, including automation and digitalization, are enhancing manufacturing efficiency and ensuring the production of high-quality pharmaceuticals, further driving the market’s growth.
Colombia's Contract Pharmaceutical Manufacturing market is primarily concentrated in key cities such as Bogotá, Medellín, Cali, and the coastal regions of Barranquilla and Cartagena. Bogotá, as the capital, serves as a central hub for pharmaceutical production due to its well-developed infrastructure, skilled workforce, and proximity to regulatory bodies. Medellín and Cali also play significant roles with their competitive manufacturing costs and growing expertise in both generic and specialized pharmaceutical production. The coastal cities of Barranquilla and Cartagena are emerging as important centers due to their strategic access to international trade routes. Key players in Colombia's contract pharmaceutical manufacturing sector include multinational and local companies such as EMS Pharma, Eurofarma, Hypera Pharma, Natulab, UCB Pharma, and Pfizer Inc., among others. These companies leverage Colombia's favorable business environment, skilled workforce, and strategic location to enhance production and access regional and global markets.
Market Insights
- The Colombia Contract Pharmaceutical Manufacturing market was valued at USD 736.63 million in 2023 and is projected to reach USD 1,353.75 million by 2032, growing at a CAGR of 6.99%.
- A favorable regulatory environment, including adherence to international quality standards, drives the market's growth.
- The demand for high-quality, affordable medicines is increasing, particularly with the rise in healthcare expenditure and aging population.
- Colombia's strategic geographic location and participation in free trade agreements facilitate access to key global markets.
- The market is highly competitive with key players like EMS Pharma, Eurofarma, Pfizer, and UCB Pharma leading the way.
- Supply chain vulnerabilities and regulatory hurdles can restrain market expansion, posing challenges to timely market entry.
- Regional manufacturing hubs such as Bogotá, Medellín, and Cali are central to Colombia’s pharmaceutical production, with each city offering unique advantages.
Market Drivers
Favorable Regulatory Environment Colombia’s commitment to stringent regulatory standards, such as Good Manufacturing Practices (GMP) and Good Clinical Practices (GCP), ensures high-quality and safe pharmaceutical products. These international standards make the country an attractive destination for contract pharmaceutical manufacturing. For instance, the National Food and Drug Surveillance Institute (INVIMA) plays a crucial role in maintaining these standards, ensuring that all pharmaceutical products meet stringent safety and efficacy requirements. Additionally, the Colombian government has streamlined regulatory processes, making it easier for pharmaceutical companies to navigate approval procedures and bring products to market quickly. This efficient regulatory framework enhances the country’s appeal as a reliable partner for pharmaceutical manufacturing.
Cost-Effective Operations One of the major drivers of the contract pharmaceutical manufacturing market in Colombia is its cost-effectiveness. The country offers competitive labor costs compared to developed nations, significantly reducing operational expenses for pharmaceutical manufacturers. For instance, the Colombian government provides various tax incentives and benefits, which further enhance the cost-efficiency of operations. Furthermore, the Colombian government provides various tax incentives and benefits, which further enhance the cost-efficiency of operations. These factors make Colombia an attractive option for companies looking to outsource manufacturing while maintaining high-quality standards and minimizing production costs.
Skilled Workforce and Infrastructure Colombia is home to a skilled workforce capable of meeting the demands of the pharmaceutical industry. The country produces a high number of qualified professionals, including chemists, pharmacists, and engineers, which supports the growth of contract manufacturing services. For instance, Colombia's universities and research institutions, such as the University of the Andes and the National University of Colombia, produce a steady stream of highly skilled graduates. In addition, Colombia’s robust infrastructure, including well-developed transportation networks, efficient logistics, and advanced manufacturing facilities, ensures smooth operations for pharmaceutical companies. This combination of talent and infrastructure enables efficient and reliable production processes, further boosting Colombia's position in the global pharmaceutical manufacturing market.
Strategic Geographic Location Colombia’s strategic geographic location in South America provides easy access to both North and South American markets, facilitating efficient distribution and supply chain management. For example, Bogota's El Dorado International Airport is one of the busiest in South America, offering excellent connectivity for both passenger and cargo traffic. The country’s participation in various free trade agreements (FTAs) further benefits the pharmaceutical sector by reducing tariffs on exported pharmaceutical products. This access to global markets, combined with favorable trade policies, makes Colombia a key player in the international pharmaceutical manufacturing industry, offering enhanced logistics and trade advantages for both local and international companies.
Market Trends
Focus on Specialized Manufacturing and Niche Markets
Colombian pharmaceutical manufacturers are increasingly turning their attention to the production of complex drug substances, such as active pharmaceutical ingredients (APIs) and biologics, which require advanced technological capabilities and specialized manufacturing processes. This shift is driven by the growing demand for high-value, complex medicines in both domestic and international markets. For instance, Colombia has developed expertise in niche therapeutic areas such as oncology and rare diseases, positioning itself as a leader in producing innovative treatments. Furthermore, Colombia is developing expertise in niche therapeutic areas such as oncology, rare diseases, and specialty pharmaceuticals. This focus on specialized manufacturing positions Colombia as a leader in producing innovative treatments for underserved patient populations, creating new growth opportunities in the pharmaceutical sector.
Adoption of Digital Technologies and Industry 4.0
The adoption of digital technologies and Industry 4.0 is transforming the pharmaceutical manufacturing landscape in Colombia. Pharmaceutical companies are increasingly embracing digital tools to improve operational efficiency, enhance quality control, and optimize supply chain management. For example, the integration of artificial intelligence (AI) and automation into manufacturing processes has helped companies reduce production costs and improve consistency. Technologies such as automation and artificial intelligence (AI) are being integrated into manufacturing processes, helping to reduce production costs, improve consistency, and increase output. These advancements are also enabling pharmaceutical companies to scale operations more effectively, providing them with a competitive edge in the global market. This technological shift is poised to drive further innovation and efficiency within the Colombian pharmaceutical sector.
Increasing Demand for High-Quality, Affordable Medicines
The growing domestic market in Colombia, driven by increasing healthcare expenditure and an aging population, is significantly boosting the demand for both generic and branded medicines. As more people seek affordable healthcare solutions, there is a noticeable shift toward cost-effective yet high-quality pharmaceutical products. Moreover, Colombia’s strategic location and favorable trade agreements have positioned the country to tap into global markets, particularly in Latin America and North America. This access to a broader market not only benefits the local pharmaceutical industry but also enables manufacturers to expand their reach internationally, capitalizing on growing demand in neighboring regions.
Regulatory Favorability and Investment Incentives
The Colombian government’s commitment to streamlining regulatory processes has simplified the approval and market entry for pharmaceutical products. This regulatory favorability enhances Colombia's attractiveness as a destination for pharmaceutical manufacturing. Additionally, the government offers various tax incentives and investment support programs, further stimulating domestic pharmaceutical production and attracting foreign investment. These measures provide companies with cost-saving opportunities and a conducive environment for business growth, making Colombia a competitive player in the contract pharmaceutical manufacturing sector.
Market Challenges Analysis
Infrastructure and Financial Constraints
While Colombia has made notable progress in developing its infrastructure, challenges remain, particularly in areas such as reliable power supply and transportation bottlenecks. These infrastructure limitations can disrupt manufacturing operations, delay product deliveries, and increase production costs. Moreover, the Colombian pharmaceutical sector faces vulnerabilities in its supply chain, primarily due to its reliance on imported raw materials and specialized equipment. For example, small and medium-sized enterprises in Colombia often struggle to secure affordable financing due to the perceived risks associated with the pharmaceutical sector. Fluctuations in global supply chains can lead to price volatility and shortages, affecting the stability of local production. On the financial side, access to affordable financing remains a significant challenge, especially for small and medium-sized enterprises. The risk-averse nature of financial institutions further exacerbates this issue, as they may hesitate to lend to the pharmaceutical sector due to perceived risks and uncertainties. These infrastructure and financial constraints can limit the growth potential of the industry, making it difficult for companies to scale and compete globally.
Regulatory Challenges and Intellectual Property Concerns
The Colombian pharmaceutical industry faces significant regulatory hurdles, primarily due to the stringent international quality standards it must adhere to, such as Good Manufacturing Practices (GMP) and Good Clinical Practices (GCP). Compliance with these standards is not only time-consuming but also costly, posing challenges for manufacturers looking to maintain high-quality production. Additionally, the regulatory environment is often burdened by bureaucratic delays, which can slow down market entry and increase operational costs, hindering the ability of companies to respond quickly to market demands. Another critical challenge is the weak enforcement of intellectual property (IP) rights, which undermines innovation and discourages foreign investment. The prevalence of counterfeit drugs further exacerbates this issue, posing risks to patient safety and damaging the reputation of the pharmaceutical industry. These combined regulatory and IP challenges create a complex environment that pharmaceutical manufacturers must navigate carefully.
Market Opportunities
The Colombia Contract Pharmaceutical Manufacturing market presents several promising opportunities driven by the country’s expanding pharmaceutical industry and its strategic position within Latin America. One of the key opportunities lies in the growing demand for high-quality, affordable medicines, particularly generics and branded drugs. As Colombia’s healthcare expenditure continues to rise and the aging population increases, there is a significant opportunity for contract manufacturers to meet the domestic demand. Furthermore, Colombia’s favorable trade agreements and geographic location offer companies a unique chance to access regional markets, particularly in North and South America. These factors create a robust export opportunity, positioning Colombia as a key player in the global pharmaceutical supply chain.
Additionally, the increasing focus on specialized manufacturing, such as biologics and active pharmaceutical ingredients (APIs), provides a significant growth area for contract pharmaceutical manufacturers. With a rising demand for complex and high-value drug substances, manufacturers that can leverage advanced technology and innovation are well-positioned to capitalize on this trend. Moreover, Colombia’s skilled workforce and the government’s support through tax incentives and investment-friendly policies further enhance the appeal of the country as a manufacturing hub. As the pharmaceutical industry embraces digital technologies, automation, and Industry 4.0, there is also potential for contract manufacturers to adopt cutting-edge solutions that improve efficiency, reduce costs, and enhance product quality. These opportunities make Colombia an attractive destination for both domestic and international pharmaceutical companies looking to expand their production capabilities.
Market Segmentation Analysis:
By Service Type:
The Colombia Contract Pharmaceutical Manufacturing market is segmented by service type into two main categories: Contract Manufacturing Organizations (CMOs) and Contract Research Organizations (CROs). Within CMOs, the sub-segments include API manufacturing, final dosage form manufacturing, and packaging. API manufacturing is critical for the production of active ingredients, while final dosage form manufacturing focuses on the production of finished pharmaceutical products in various forms, including tablets, capsules, and injectables. Packaging services are essential for ensuring the safe and effective delivery of pharmaceuticals to end-users. On the CRO side, the market includes a wide range of services, from drug discovery and preclinical studies to various clinical phases (I-IV). CROs play a pivotal role in the research and development (R&D) process, offering specialized services such as medical coding, clinical data management, monitoring, and protocol development, among others. The demand for these services is fueled by the growing need for outsourced R&D and manufacturing, especially for complex drug formulations and clinical trials.
By Molecule Type: The Colombia Contract Pharmaceutical Manufacturing market is further segmented by molecule type into small molecules and large molecules. Small molecules, which are typically chemically synthesized and used in a variety of therapeutic areas, dominate the market. These include common medicines like pain relievers, antibiotics, and antihypertensives, offering a significant portion of manufacturing contracts. However, the market for large molecules, such as biologics and biosimilars, is growing rapidly. Large molecules, derived from living organisms, are used in advanced treatments like monoclonal antibodies and gene therapies, which are increasingly in demand due to their effectiveness in treating complex diseases. Both small and large molecules present unique manufacturing challenges, with small molecules requiring chemical synthesis expertise and large molecules necessitating sophisticated biotechnological processes. As the demand for biologics increases globally, Colombia’s pharmaceutical manufacturers are focusing more on scaling up production capabilities to meet the growing needs of this segment.
Segments:
Based on Service Type:
- Contract Manufacturing Organization (CMO)
- API Manufacturing
- Final Dosage Form Manufacturing
- Packaging
- Contract Research Organization (CRO)
- Drug Discovery
- Preclinical Studies
- Early Phase I-IIa
- Phase IIa-III
- Phase IIIb-IV
- Medical Coding and Writing
- Monitoring
- Clinical Data Management
- Others (Protocol Development, etc.)
Based on Molecule Type:
- Small Molecule
- Large Molecule
Based on the Geography:
- Bogotá
- Medellín
- Cali
- Barranquilla
- Cartagena
Regional Analysis
Bogotá
Bogotá, the capital and largest city of Colombia, holds the largest market share in the country's contract pharmaceutical manufacturing sector, accounting for approximately 40% of the overall market. This dominance is driven by the city’s robust infrastructure, access to skilled labor, and the presence of many multinational pharmaceutical companies. As the political and economic center of Colombia, Bogotá benefits from a well-established regulatory environment and a strong network of healthcare institutions. The city also boasts an advanced transportation network, making it an ideal location for both manufacturing and distribution. Pharmaceutical companies in Bogotá have significant access to government incentives, investment programs, and a thriving business ecosystem, contributing to its market leadership. The city's strong research and development (R&D) capabilities also make it a hub for innovation in the pharmaceutical manufacturing industry.
Medellín Medellín, known for its industrialization and innovation, holds a market share of approximately 25% in the Colombia Contract Pharmaceutical Manufacturing market. The city has evolved into a major center for pharmaceutical production, with a focus on both generic and specialized drug manufacturing. Medellín benefits from its position as the second-largest city in Colombia and its proximity to key manufacturing facilities, which allows it to attract both domestic and international pharmaceutical companies. With a growing number of life sciences and biotechnology firms, Medellín is becoming increasingly recognized for its expertise in complex manufacturing processes such as biologics and active pharmaceutical ingredients (APIs). The city's competitive labor costs and advanced infrastructure further support its strong position in the pharmaceutical market.
Cali Cali, situated in the southwest region of Colombia, holds a smaller but significant market share of approximately 15% in the contract pharmaceutical manufacturing sector. Known for its strategic location near the Pacific Ocean, Cali offers pharmaceutical manufacturers easy access to international markets, particularly those in the Americas. This has made the city a valuable hub for companies focused on export-oriented production. In addition to its transportation advantages, Cali benefits from a skilled workforce and government incentives designed to attract foreign direct investment. The city’s infrastructure, although less advanced compared to Bogotá and Medellín, is still adequate to support pharmaceutical manufacturing operations. The growing demand for pharmaceuticals in the region, especially for generics, further strengthens Cali's position in the market.
Barranquilla and Cartagena Barranquilla and Cartagena, located in the northern coastal region of Colombia, represent emerging centers for pharmaceutical manufacturing, collectively holding a market share of around 20%. Barranquilla is a key industrial and logistics hub due to its proximity to major ports, making it an attractive location for companies focused on international trade. Cartagena, on the other hand, has seen substantial growth in its pharmaceutical sector due to its coastal location and access to global markets. The two cities offer significant tax incentives and government support to foster the growth of the pharmaceutical manufacturing industry. While the market share for these cities is still smaller compared to Bogotá and Medellín, their strategic positions and growing infrastructure make them promising regions for the expansion of contract pharmaceutical manufacturing in Colombia.
Key Player Analysis
- EMS Pharma
- Eurofarma
- Hypera Pharma
- Natulab
- UCB Pharma
- Hovione
- Unilab
- Boehringer Ingelheim International GmbH
- Fresenius Kabi AG
- Unither Pharmaceuticals
- Pfizer Inc.
- Charles River Laboratories
- Laboratory Corporation of America Holdings
Competitive Analysis
The Colombia Contract Pharmaceutical Manufacturing market is highly competitive, with key players dominating various segments of the industry. Leading companies such as EMS Pharma, Eurofarma, Hypera Pharma, Natulab, UCB Pharma, Hovione, Unilab, Boehringer Ingelheim International GmbH, Fresenius Kabi AG, Unither Pharmaceuticals, Pfizer Inc., Charles River Laboratories, and Laboratory Corporation of America Holdings are pivotal in driving market growth. These companies leverage their global presence, extensive product portfolios, and strong manufacturing capabilities to gain a competitive edge. For instance, Procaps Group, a leading pharmaceutical company in Colombia, has been recognized for its extensive product portfolio and strong manufacturing capabilities. Companies with a strong global presence continue to lead, capitalizing on their extensive resources, infrastructure, and expertise. These players focus on a broad range of services, including active pharmaceutical ingredient (API) manufacturing, final dosage form production, and specialized packaging. The market is driven by the increasing demand for high-quality, cost-effective medicines, especially in generics and biologics. Companies are adopting advanced technologies such as automation, artificial intelligence, and digital solutions to optimize manufacturing processes and ensure compliance with stringent regulatory standards. Strategic partnerships and collaborations are becoming increasingly common, as firms look to leverage each other's expertise and resources to expand their portfolios and access new markets. As the demand for complex drugs, such as biologics and specialized therapies, grows, competition intensifies in the race to develop and produce innovative treatments. Overall, the competitive environment remains dynamic, with ongoing investments in R&D and infrastructure to cater to the evolving needs of the pharmaceutical industry.
Recent Developments
- In July 2024, Esteve Pharmaceuticals announced an investment of USD 108 million to build a new manufacturing unit at its Girona plant for API production.
- In May 2024, AbbVie entered into a product development and option-to-license agreement with Gilgamesh Pharmaceuticals to develop next-generation therapies for psychiatric disorders.
- In May 2024, Siren Biotechnology and Catalent, Inc. entered in partnership for manufacturing of AAV Gene Therapies for cancer.
- In April 2024, KVK-Tech entered into a strategic agreement with Sen-Jam Pharmaceutical to manufacture the latter’s injectable anti-inflammatory therapeutic, SJP-100.
- In March 2024, Lonza has signed an agreement to acquire the Genentech manufacturing facility in Vacaville (US) from Roche for USD 1.2 billion in cash.
- In November 2023, Daré Bioscience, Inc., a leader in women’s health innovation, and Premier Research International, LLC, a global clinical research, product development, and consulting company, announced that the companies extended their partnership agreement under which Premier Research International, LLC will continue to provide an exclusive basis contract research organization (CRO) service within the U.S. to support the clinical development of Daré Bioscience, Inc’s reproductive health portfolio
- In November, 2023, Ichor Life Sciences, a full-service contract research organization (CRO) and longevity biotechnology company, announced the launch of Ichor Clinical Trial Services. With the founding of Ichor Clinical, the company is able to serve biotechnology and pharmaceutical clients from early preclinical studies through late-stage clinical trials and U.S. Food Drug Administration approval.
Market Concentration & Characteristics
The Colombia Contract Pharmaceutical Manufacturing market exhibits moderate concentration, with a few large multinational companies and local players dominating the industry. These companies benefit from robust infrastructure, access to skilled labor, and the ability to scale operations for both domestic and international markets. The market is characterized by a diverse range of services, including API manufacturing, final dosage form production, packaging, and clinical research services. This diversity allows companies to cater to the growing demand for both generic and specialized medicines, especially biologics and high-value drugs. The market is also characterized by a strong regulatory environment, ensuring that manufacturing processes comply with stringent international standards such as GMP and GCP. This fosters trust in the quality of products and ensures the safety of pharmaceuticals reaching both local and international consumers. Furthermore, the industry is witnessing increasing investment in advanced technologies, including automation and AI, which improve efficiency, reduce costs, and enhance product quality. Collaboration between large multinational companies and smaller, specialized firms is also a significant characteristic, as it allows for access to new technologies and therapeutic areas. Overall, the market's concentration is balanced by ongoing investments in innovation, technological advancements, and regulatory compliance, positioning it for continued growth in the coming years.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Molecule Type, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Colombian government’s ongoing investment in healthcare infrastructure will support the growth of the pharmaceutical manufacturing sector.
- With a strong pool of skilled professionals, the labor force will continue to meet the growing demands of the pharmaceutical industry.
- The market will see expansion in niche therapeutic areas, including oncology, rare diseases, and specialty pharmaceuticals.
- Collaboration with international regulatory bodies will enhance the industry’s credibility and facilitate smoother market access.
- The adoption of digital transformation in pharmaceutical manufacturing will improve product traceability, supply chain management, and regulatory compliance.
- Demand for contract research services, particularly in drug discovery and clinical trials, will rise due to the increasing complexity of drug development.
- The market will continue to benefit from free trade agreements, reducing tariffs and promoting exports to North and South America.
- The focus on cost-effective operations and competitive labor costs will position Colombia as an attractive destination for pharmaceutical outsourcing.
- The rise of counterfeit drugs will drive the need for enhanced security measures and stronger intellectual property protection in manufacturing.
- The ongoing development of new drug formulations will lead to more specialized manufacturing capabilities, particularly in complex molecule production.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Colombia Contract Pharmaceutical Manufacturing market?
What factors are driving the growth of the Colombia Contract Pharmaceutical Manufacturing market?
What are the key segments within the Colombia Contract Pharmaceutical Manufacturing market?
What are some challenges faced by the Colombia Contract Pharmaceutical Manufacturing market?
Who are the major players in the Colombia Contract Pharmaceutical Manufacturing market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Colombia Contract Pharmaceutical Manufacturing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Colombia Contract Pharmaceutical Manufacturing Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 736.63 million → 2032: USD 1,353.75 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Colombia Contract Pharmaceutical Manufacturing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Colombia Contract Pharmaceutical Manufacturing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Colombia Contract Pharmaceutical Manufacturing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Colombia Contract Pharmaceutical Manufacturing Market Drivers
- 3.3 Colombia Contract Pharmaceutical Manufacturing Market Restraints & Challenges
- 3.4 Colombia Contract Pharmaceutical Manufacturing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Colombia Contract Pharmaceutical Manufacturing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Colombia Contract Pharmaceutical Manufacturing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Colombia Contract Pharmaceutical Manufacturing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Colombia Contract Pharmaceutical Manufacturing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Colombia Contract Pharmaceutical Manufacturing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Colombia Contract Pharmaceutical Manufacturing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Colombia Contract Pharmaceutical Manufacturing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Colombia Contract Pharmaceutical Manufacturing Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Colombia Contract Pharmaceutical Manufacturing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Colombia Contract Pharmaceutical Manufacturing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Colombia Contract Pharmaceutical Manufacturing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Colombia Contract Pharmaceutical Manufacturing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Colombia Contract Pharmaceutical Manufacturing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Colombia Contract Pharmaceutical Manufacturing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Colombia Contract Pharmaceutical Manufacturing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Colombia Contract Pharmaceutical Manufacturing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Colombia Contract Pharmaceutical Manufacturing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Colombia Contract Pharmaceutical Manufacturing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Colombia Contract Pharmaceutical Manufacturing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
