
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Commercial Hot Dog Cooker Market Size 2024 | USD 62.9 million |
| Commercial Hot Dog Cooker Market, CAGR | 3.8% |
| Commercial Hot Dog Cooker Market Size 2032 | USD 84.76 million |
Market Overview:
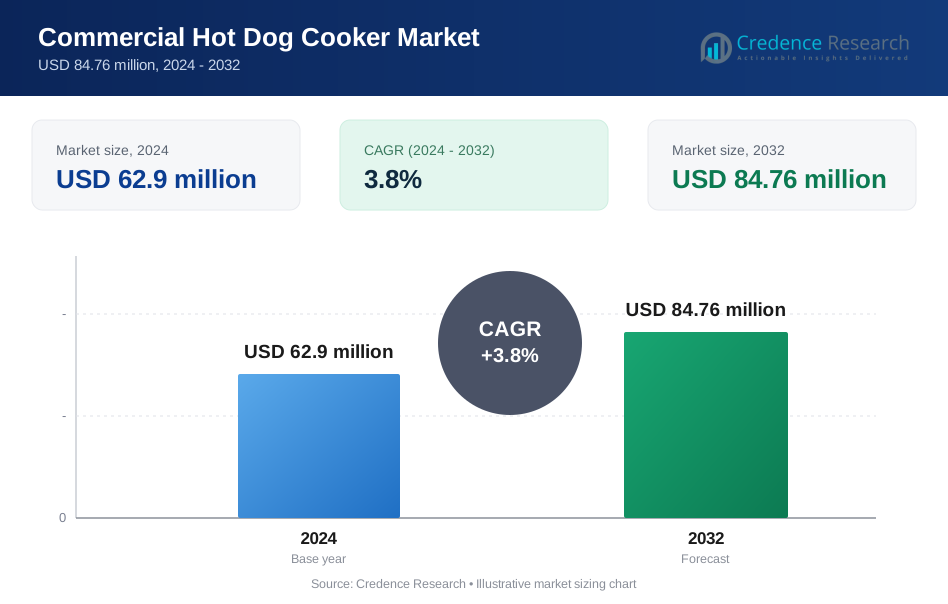
The Commercial Hot Dog Cooker Market size was valued at USD 62.9 million in 2024 and is anticipated to reach USD 84.76 million by 2032, at a CAGR of 3.8% during the forecast period (2024-2032).
Key market drivers include the rising demand for convenient and efficient food preparation solutions in the foodservice sector. The popularity of grab-and-go food options has led to increased adoption of hot dog cookers in high-footfall locations. Additionally, advancements in infrared heating technology, roller grills, and steaming mechanisms enhance cooking efficiency and maintain food quality, further boosting sales. The growing trend of food trucks and mobile catering businesses also drives market growth, as these businesses seek compact and high-performance cooking equipment. Stringent food safety regulations and the need for consistent food preparation standards encourage businesses to invest in reliable, high-capacity hot dog cookers. Rising labor costs in the food industry are also pushing businesses to invest in automated cooking solutions. Furthermore, the increasing preference for energy-efficient and easy-to-clean appliances supports the adoption of advanced hot dog cookers.
Regionally, North America dominates the market due to high fast-food consumption and a strong network of QSRs and convenience stores. The United States leads in adoption, supported by established brands and a growing food concession industry. Europe follows closely, with increasing demand from entertainment venues and street food vendors. The Asia-Pacific region is witnessing rapid growth, driven by urbanization, rising disposable income, and the expansion of international fast-food chains in countries like China, India, and Japan. Additionally, government initiatives promoting small-scale food businesses and street vending contribute to market expansion in this region. Meanwhile, Latin America and the Middle East & Africa are emerging markets, benefiting from increasing tourism and growing interest in Western-style fast food. The rising number of shopping malls and entertainment hubs in these regions also boosts the demand for commercial hot dog cookers.
Market Insights:
- The commercial hot dog cooker market was valued at USD 62.9 million in 2024 and is projected to reach USD 84.76 million by 2032, growing at a CAGR of 3.8%.
- Increasing demand for quick-service restaurants, convenience stores, and food trucks is driving market growth, along with the rising trend of grab-and-go food options.
- Technological advancements such as infrared heating, smart temperature controls, and energy-efficient roller grills are improving cooking performance and reducing energy consumption.
- The growing food truck and mobile catering industry is creating demand for compact, portable, and high-capacity hot dog cookers.
- Stringent food safety regulations are pushing businesses to invest in easy-to-clean, NSF-certified, and durable cooking appliances to ensure compliance.
- North America leads the market with a 35% share, followed by Europe (28%) and Asia-Pacific (22%), where fast food consumption and urbanization are driving growth.
- The rising cost of energy and equipment maintenance remains a challenge, leading businesses to seek cost-effective and automated solutions to enhance efficiency.
Market Drivers:
Growing Demand for Quick-Service and Grab-and-Go Food Options
The rising consumer preference for quick-service restaurants (QSRs) and grab-and-go food options is a primary driver of the commercial hot dog cooker market. As urbanization increases and busy lifestyles become the norm, consumers seek convenient and fast meal solutions, leading to higher demand for hot dog cookers in foodservice establishments. For instance, Chevron ExtraMile convenience stores offer a variety of hot and fresh foods, including hot dogs, for consumers seeking food on the go. Concession stands, convenience stores, and stadium vendors increasingly rely on efficient cooking equipment to serve customers quickly while maintaining food quality. This trend is further supported by the growing popularity of self-service food stations, which require reliable and easy-to-use cooking appliances.
Technological Advancements in Cooking Equipment
Advancements in cooking technology have significantly improved the efficiency and functionality of commercial hot dog cookers. Modern units incorporate infrared heating, energy-efficient roller grills, and steaming mechanisms to enhance cooking performance while reducing energy consumption. These innovations help businesses maintain consistent food quality, improve operational efficiency, and minimize food waste. For instance, APW Wyott offers roller grills that are made in the USA with quality and performance in mind. Additionally, automation in cooking appliances reduces manual labor requirements, making hot dog cookers more appealing to foodservice operators facing rising labor costs. The integration of smart temperature control and programmable cooking settings further enhances usability, ensuring optimal cooking conditions with minimal supervision.
Expansion of Mobile Food Businesses and Catering Services
The increasing number of food trucks, mobile catering services, and outdoor food vendors has contributed to the growing demand for compact and high-performance hot dog cookers. These businesses require space-saving and portable equipment that can deliver high-volume output without compromising food safety standards. The flexibility of hot dog cookers, which can operate efficiently in various environments, makes them an ideal choice for mobile food vendors. For instance, Nathan's Famous hot dog carts are often seen at outdoor events and festivals, providing a portable and recognizable option for attendees. Additionally, the surge in outdoor events, festivals, and corporate catering services has further fueled the adoption of commercial hot dog cookers, as businesses seek reliable solutions to meet customer demand efficiently.
Stringent Food Safety Regulations and Hygiene Standards
Food safety regulations play a crucial role in shaping the commercial hot dog cooker market. Health authorities impose strict guidelines on food preparation and handling, prompting foodservice operators to invest in equipment that ensures compliance with hygiene and safety standards. For instance, the NSF certification program requires that hot dog cookers meet strict food safety standards for materials, design, and construction. Manufacturers have responded by developing easy-to-clean, stainless steel, and NSF-certified hot dog cookers that minimize contamination risks. Additionally, features such as automatic shut-off, precise temperature control, and grease management systems enhance safety and hygiene, making these appliances a preferred choice for businesses aiming to uphold food quality standards. As regulatory scrutiny intensifies globally, the demand for compliant and efficient hot dog cooking equipment is expected to grow.
Market Trends:
Rising Adoption of Energy-Efficient and Smart Cooking Equipment
The commercial hot dog cooker market is witnessing a shift toward energy-efficient and technologically advanced cooking solutions. Businesses are increasingly investing in appliances that reduce operational costs while enhancing performance. Modern hot dog cookers now incorporate infrared heating, programmable temperature controls, and automatic shut-off features to improve energy efficiency and ensure consistent cooking results. For instance, Roller Grill's professional induction hobs offer precise temperature control and are built with robust components for continuous use, ensuring efficient and consistent cooking. Additionally, manufacturers are integrating smart technology that enables remote monitoring and control, allowing foodservice operators to maintain efficiency with minimal manual intervention.
Growing Popularity of Self-Service and Automated Food Stations
The rise of self-service kiosks and automated food stations is driving demand for user-friendly and easy-to-operate hot dog cookers. Convenience stores, supermarkets, and food courts are adopting self-serve hot dog stations equipped with roller grills and warming trays that allow customers to prepare their own meals. These solutions help businesses reduce labor costs while offering a convenient and interactive dining experience. For instance, the Unox Casa SuperOven features an easy-to-use digital control panel with over 400 automatic cooking programs, making it simple to achieve haute cuisine results with just a touch. Moreover, the increasing integration of contactless payment and digital ordering systems enhances the efficiency of self-service operations.
Expansion of Food Trucks and Mobile Catering Businesses
The rapid growth of food trucks, pop-up eateries, and mobile catering services has boosted the demand for compact, portable, and high-performance hot dog cookers. Entrepreneurs in the mobile food sector prefer cooking equipment that offers quick heating, ease of transport, and high-capacity output to meet customer demands efficiently. For instance, Lestov's 3500W countertop induction cooker is a compact and durable option for mobile kitchens, boasting high thermal efficiency and a food-grade stainless steel body. As street food culture continues to thrive, the need for versatile and durable cooking solutions is increasing, driving further innovation in the market.
Increased Focus on Hygiene and Food Safety Compliance
Strict food safety regulations and hygiene standards are influencing product development in the hot dog cooker market. Manufacturers are introducing stainless steel, NSF-certified, and easy-to-clean models to ensure compliance with health and safety guidelines. Features such as grease management systems, non-stick surfaces, and enclosed heating elements help minimize contamination risks and improve sanitation. For instance, UNOX ovens have developed an innovative self-cleaning commercial oven that checks the amount of accumulated dirt and selects the most efficient washing program in each situation, avoiding waste of water and detergent. With regulatory bodies imposing stringent hygiene requirements, businesses are prioritizing cooking appliances that ensure safe and high-quality food preparation.
Market Challenges Analysis:
Rising Operational Costs and Energy Consumption
One of the significant challenges in the commercial hot dog cooker market is the increasing operational costs associated with energy consumption and maintenance. Many traditional hot dog cookers consume high amounts of electricity, leading to elevated utility expenses for foodservice businesses. As energy costs continue to rise, operators are seeking more energy-efficient alternatives, but upgrading to advanced models requires a substantial initial investment. Additionally, frequent usage of commercial cooking equipment results in wear and tear, leading to ongoing maintenance costs. Smaller food businesses and startups, particularly in emerging markets, face difficulties in balancing affordability with the need for durable, high-performance cooking appliances. The financial burden of regular equipment servicing and part replacements further adds to the cost of ownership, making it challenging for businesses to maintain profitability. As a result, many businesses opt for lower-cost, less efficient models, which can negatively impact operational efficiency and food quality over time.
Stringent Food Safety Regulations and Compliance Requirements
Regulatory compliance is another major challenge for manufacturers and foodservice operators. Health and safety authorities impose strict food handling and sanitation guidelines, requiring businesses to invest in equipment that meets hygiene and quality standards. While manufacturers are innovating to develop easy-to-clean, NSF-certified hot dog cookers, compliance with evolving regulations adds to production costs. Inconsistent regulatory standards across different regions also create challenges for international manufacturers, as they must modify products to meet specific local requirements. Businesses operating in highly regulated markets must continuously update equipment and adopt best practices to avoid penalties and maintain consumer trust. Failure to comply with hygiene and safety regulations can result in fines, legal consequences, and reputational damage, further complicating operations for foodservice providers. Additionally, increasing consumer awareness of food safety has intensified scrutiny, making it essential for businesses to prioritize compliance and maintain high sanitation standards.
Market Opportunities:
The commercial hot dog cooker market presents significant growth opportunities driven by the expansion of quick-service restaurants, convenience stores, and mobile food vendors. As urbanization and fast-paced lifestyles increase, consumers seek quick, affordable, and readily available food options, creating demand for efficient cooking equipment. The rise of self-service food stations in supermarkets, gas stations, and entertainment venues offers further market potential, as businesses look for user-friendly and low-maintenance cooking solutions. Additionally, the increasing trend of food trucks and pop-up eateries provides a lucrative opportunity for manufacturers to develop compact, portable, and high-capacity hot dog cookers tailored for small-scale operators. Businesses investing in automated and smart cooking solutions can attract more customers by offering consistent food quality while reducing operational costs.
The growing emphasis on sustainability and energy efficiency is another major opportunity for market expansion. Manufacturers developing energy-efficient, eco-friendly, and easy-to-clean hot dog cookers can gain a competitive edge as businesses look for ways to minimize their carbon footprint and reduce electricity consumption. Additionally, advancements in digital integration, such as smart temperature controls and IoT-enabled monitoring, create new possibilities for innovation in the market. Emerging markets in Asia, Latin America, and the Middle East, where street food culture is expanding, present untapped opportunities for global manufacturers. As disposable income rises in these regions, the demand for high-quality and compliant food equipment is expected to grow, encouraging businesses to invest in durable and efficient cooking appliances.
Market Segmentation Analysis:
By Type
The market includes roller grills, steamers, and rotisserie cookers, each catering to specific operational needs. Roller grills hold the largest market share due to their efficiency, ease of use, and ability to cook multiple hot dogs simultaneously. These are widely adopted in high-traffic locations such as convenience stores, stadiums, and concession stands. Steamers are gaining traction in foodservice establishments that prioritize moisture retention and even heating, ensuring consistent product quality. Rotisserie cookers, while a niche segment, appeal to gourmet food vendors and specialty restaurants looking to differentiate their offerings through unique presentation and flavor enhancement.
By End-User Industry
The commercial hot dog cooker market serves quick-service restaurants, convenience stores, food trucks, and stadiums, among others. Quick-service restaurants generate significant demand as they require high-capacity, efficient cooking equipment to maintain fast customer service. Convenience stores increasingly integrate hot dog cookers into their foodservice sections to expand grab-and-go offerings. The food truck industry is a growing segment, as mobile vendors prioritize compact, portable, and high-performance cookers that optimize space and efficiency. Additionally, stadiums and entertainment venues represent a key market, requiring robust, high-capacity cookers to handle high footfall and rapid service demands. With increasing consumer preference for quick and convenient food options, demand across these industries is expected to grow steadily.
Segmentations:
By Type
- Steamers
- Roller Grills
- Rotisserie Cookers
By End-User Industry
- Quick-Service Restaurants
- Convenience Stores
- Food Trucks
- Stadiums and Entertainment Venues
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share, accounting for 35% of the global commercial hot dog cooker market. The region's dominance is driven by the widespread popularity of hot dogs in quick-service restaurants, concession stands, and convenience stores. The United States leads the market, supported by a well-established network of foodservice outlets and a strong culture of fast food consumption. High demand from stadiums, amusement parks, and entertainment venues further boosts sales. Additionally, the presence of leading manufacturers and continuous product innovation, such as energy-efficient and smart cooking solutions, contribute to market expansion. Canada also shows steady growth, with rising consumer demand for grab-and-go food options in urban centers.
Europe
Europe accounts for 28% of the commercial hot dog cooker market, driven by increasing demand from street food vendors, cafes, and fast-food chains. Germany, the United Kingdom, and France are the primary contributors, with a growing preference for quick-service meals and convenient food solutions. The region's expanding tourism and entertainment industry further support market growth, particularly in high-footfall locations such as train stations, airports, and shopping centers. Additionally, stringent food safety regulations encourage the adoption of high-quality, easy-to-clean cooking equipment. The market is also influenced by the rising popularity of American-style fast food, leading to greater investment in specialized cooking appliances.
Asia-Pacific
Asia-Pacific holds 22% of the global market share, with rapid growth driven by urbanization, rising disposable income, and expanding international fast-food chains. China, India, and Japan are the key markets, with an increasing number of quick-service restaurants, food kiosks, and convenience stores adopting hot dog cookers. The growing trend of food trucks and street food culture also fuels demand for compact, high-efficiency cooking solutions. Additionally, government initiatives supporting small-scale food businesses and local entrepreneurs contribute to market expansion. As consumer preferences shift toward Western-style fast food, manufacturers are focusing on offering cost-effective and energy-efficient cooking equipment to cater to the region's diverse foodservice sector.
Key Player Analysis:
- Nemco Food Equipment
- APW Wyott
- Star Manufacturing International
- Benchmark USA
- Vollrath Company
- Cretors & Company
- Avantco Equipment
- Adcraft (Admiral Craft Equipment Corp.)
- Waring Commercial
- Equipex
- Globe Food Equipment Company
- Great Northern Popcorn Company
Competitive Analysis:
The commercial hot dog cooker market is highly competitive, with established manufacturers focusing on innovation, product efficiency, and durability to maintain market share. Leading players compete based on factors such as product performance, energy efficiency, pricing, and compliance with food safety regulations. Companies are investing in smart cooking technology, automation, and energy-saving features to differentiate their offerings and attract foodservice businesses seeking cost-effective solutions. For instance, according to a survey by the National Restaurant Association, approximately 70% of restaurant operators consider energy efficiency when purchasing new cooking equipment.
North American and European manufacturers dominate the market due to their established distribution networks and strong brand presence. However, increasing demand in Asia-Pacific and Latin America is encouraging global players to expand into emerging markets. Strategic partnerships, product diversification, and advancements in compact, high-capacity cookers drive competition. As businesses focus on hygiene, ease of use, and sustainability, manufacturers continue to refine their products to meet evolving industry demands.
Recent Developments:
- In January 2023, Great Northern Popcorn Company released a 9-roller hot dog machine with a capacity of 24 hot dogs per batch.
- In December 2024, Hot Hold® Dry/Moist Food Warmers designed to keep both crispy and juicy foods at their flavorful best for hours.
Market Concentration & Characteristics:
The commercial hot dog cooker market is moderately concentrated, with a mix of established global manufacturers and regional players competing for market share. Leading companies dominate due to their strong brand reputation, extensive distribution networks, and continuous product innovation. The market is characterized by technological advancements, energy efficiency, and compliance with food safety regulations, driving manufacturers to develop durable and high-performance cooking equipment. Competition is fueled by the increasing demand for compact, automated, and easy-to-maintain hot dog cookers, especially in quick-service restaurants, convenience stores, and mobile food businesses. While North America and Europe lead in market presence, Asia-Pacific and Latin America are emerging as high-growth regions due to urbanization and the expansion of international fast-food chains. The industry also emphasizes sustainability, hygiene, and automation, as businesses seek cost-effective and regulatory-compliant cooking solutions.
Report Coverage:
The research report offers an in-depth analysis based on Type, End-User Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for energy-efficient and automated hot dog cookers will continue to grow as businesses seek to reduce operational costs and improve efficiency.
- The expansion of quick-service restaurants, convenience stores, and food trucks will drive market growth, particularly in emerging economies.
- Advancements in smart cooking technology, including IoT-enabled monitoring and programmable temperature controls, will enhance product appeal.
- Increasing consumer preference for grab-and-go food options will boost the adoption of self-service hot dog stations in high-footfall locations.
- Manufacturers will focus on developing compact and portable hot dog cookers to cater to the growing food truck and mobile catering industry.
- Strict food safety and hygiene regulations will encourage businesses to invest in easy-to-clean, NSF-certified, and stainless-steel cooking equipment.
- Expansion into Asia-Pacific, Latin America, and the Middle East will create new growth opportunities for manufacturers.
- Sustainability concerns will lead to the introduction of eco-friendly and energy-efficient cooking solutions to meet regulatory and consumer demands.
- The rising trend of customizable and specialty hot dog offerings will drive innovation in cooking equipment design and functionality.
- Competitive pricing and product differentiation through advanced features will be key strategies for manufacturers to maintain market share.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Commercial Hot Dog Cooker Market?
What factors are driving the growth of the Commercial Hot Dog Cooker Market?
What are some challenges faced by the Commercial Hot Dog Cooker Market?
Who are the major players in the Commercial Hot Dog Cooker Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Commercial Hot Dog Cooker Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Commercial Hot Dog Cooker Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 62.9 million → 2032: USD 84.76 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Commercial Hot Dog Cooker Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Commercial Hot Dog Cooker Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Commercial Hot Dog Cooker Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Commercial Hot Dog Cooker Market Drivers
- 3.3 Commercial Hot Dog Cooker Market Restraints & Challenges
- 3.4 Commercial Hot Dog Cooker Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Commercial Hot Dog Cooker Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Commercial Hot Dog Cooker Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Commercial Hot Dog Cooker category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Commercial Hot Dog Cooker Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Commercial Hot Dog Cooker Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Commercial Hot Dog Cooker market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Commercial Hot Dog Cooker Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Commercial Hot Dog Cooker Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Commercial Hot Dog Cooker Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Commercial Hot Dog Cooker (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Commercial Hot Dog Cooker Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Commercial Hot Dog Cooker Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Commercial Hot Dog Cooker Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Commercial Hot Dog Cooker Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Commercial Hot Dog Cooker Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Commercial Hot Dog Cooker Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Commercial Hot Dog Cooker Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Commercial Hot Dog Cooker Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Commercial Hot Dog Cooker Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer