
Market Overview
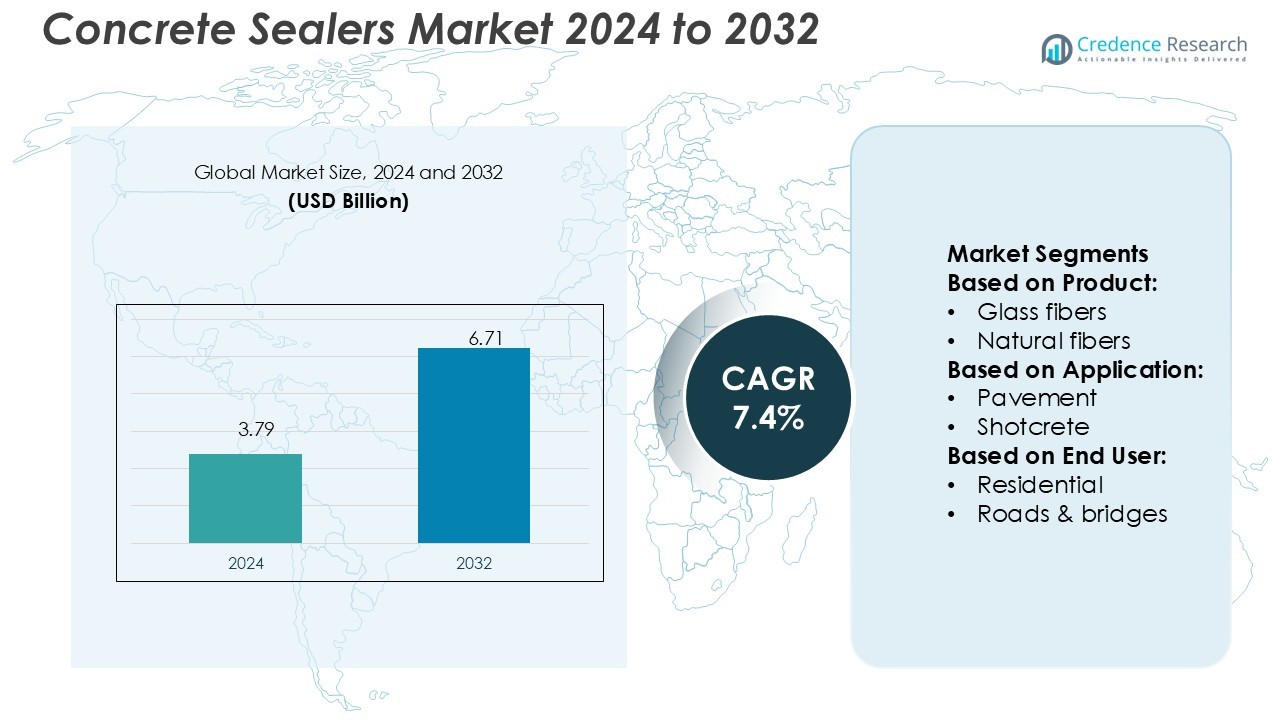
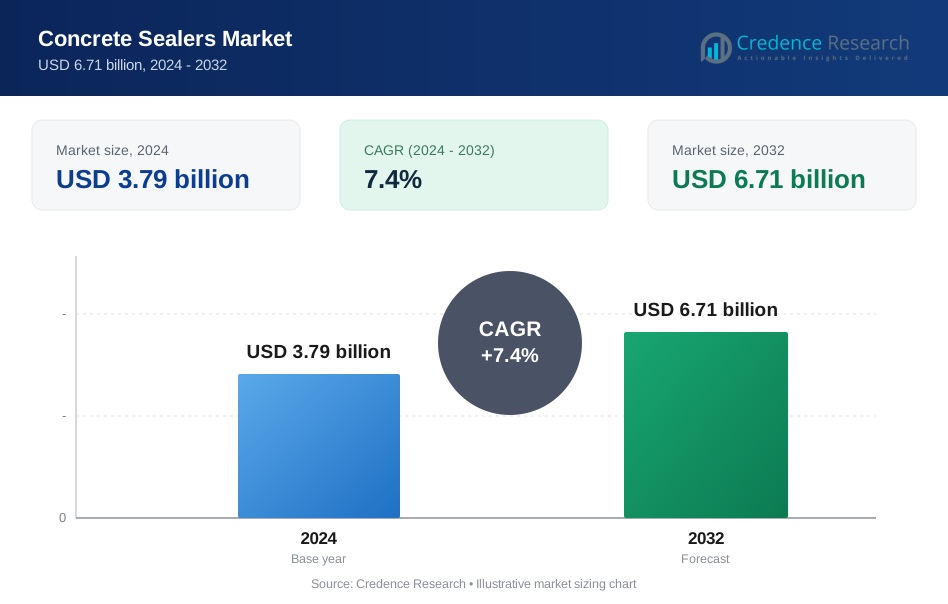
Concrete Sealers Market size was valued USD 3.79 billion in 2024 and is anticipated to reach USD 6.71 billion by 2032, at a CAGR of 7.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Concrete Sealers Market Size 2024 | USD 3.79 Billion |
| Concrete Sealers Market, CAGR | 7.4% |
| Concrete Sealers Market Size 2032 | USD 6.71 Billion |
The concrete sealers market is driven by major players including Valspar Corp., Sika AG, BASF SE, Mapei Construction Products, Vexcon Chemicals, Inc., PPG Industries, Laticrete International, Evonik Industries, Omnova Solutions, and Arkema. These companies focus on developing advanced, sustainable sealing solutions to meet rising global construction demands. Strategic investments in R&D, product diversification, and eco-friendly formulations give them a strong competitive edge. Many also expand through partnerships and acquisitions to strengthen their global footprint. North America leads the market with a 34% share, supported by widespread use of high-performance sealers in residential, commercial, and infrastructure projects. Strong regulatory standards and growing renovation activities continue to drive the region’s leadership position.
Market Insights
- The concrete sealers market size was valued at USD 3.79 billion in 2024 and is expected to reach USD 6.71 billion by 2032, growing at a CAGR of 7.4%.
- Rising infrastructure development and renovation activities in residential, commercial, and industrial sectors are driving strong product demand.
- The market is witnessing a clear shift toward eco-friendly, water-based, and low-VOC sealers as sustainability regulations tighten globally.
- Key players focus on R&D, product diversification, and strategic partnerships to enhance performance, expand global reach, and strengthen their competitive position.
- North America leads the market with a 34% regional share, followed by Europe and Asia Pacific, while steel fibers dominate the product segment, supported by increasing adoption in pavements and industrial flooring.
Market Segmentation Analysis:
By Product
Steel fibers hold the largest market share in the concrete sealers market. Their dominance comes from their high tensile strength, superior crack control, and ability to improve flexural performance in industrial and infrastructure applications. They are widely used in heavy-duty flooring, precast elements, and tunnel linings due to their durability. For instance, several major construction projects integrate steel fibers to reduce shrinkage cracking and enhance structural life. The rising adoption of fiber-reinforced concrete in warehouses, bridges, and pavements further supports their leading position over synthetic, polypropylene, and other fiber types.
- For instance, Master Builders Solutions (formerly part of BASF) produces MasterFiber M 100 monofilament polypropylene fiber, which is recommended to be dosed at 0.30 kg/m³ (0.50 lb/yd³).
By Application
Pavement applications lead the market with the highest share. This dominance is driven by the growing use of fiber-reinforced concrete in highways, airport runways, and parking structures. Fiber integration increases pavement strength, fatigue resistance, and service life, making it cost-effective for large-scale infrastructure projects. Road authorities increasingly adopt fiber-enhanced pavement to reduce maintenance cycles and improve performance under high traffic loads. Rising investments in transport infrastructure globally, combined with strict durability standards, continue to drive demand in this segment ahead of shotcrete, precast, and slab applications.
- For instance, ChemMasters, Inc. (which acquired Vexcon Chemicals) produces Certi-Vex AC1315 HG, a solvent-based, high-gloss, 30% solids acrylic cure and protect for concrete. The product has a VOC content below 700 g/L.
By End User
Industrial and commercial infrastructure represent the dominant end-user segment. These sectors favor fiber-reinforced concrete sealers for their strength, crack resistance, and reduced long-term repair costs. Warehouses, manufacturing units, logistics hubs, and commercial buildings require durable flooring and structural elements that can withstand heavy loads. Fiber concrete delivers superior performance compared to conventional reinforcement, driving its widespread adoption. Large infrastructure developers are integrating steel and synthetic fibers to meet performance standards and sustainability goals. This strong demand positions industrial and commercial applications ahead of residential and road infrastructure segments.
Key Growth Drivers
Rising Infrastructure Development Activities
The growing investment in large-scale infrastructure projects is a major growth driver for the concrete sealers market. Governments and private firms are expanding roads, bridges, airports, and commercial facilities. Concrete sealers protect surfaces from moisture, chemical spills, and abrasion, extending their lifespan. For example, projects in rapidly urbanizing economies require durable construction materials to minimize maintenance costs. This rising demand for improved structural performance and longevity is pushing contractors and developers to use high-performance sealers. Increased focus on cost-efficient construction further accelerates market adoption.
- For instance, PPG Industries produces PSX® 700, a high-performance polysiloxane coating known for its excellent durability, color retention, and chemical resistance. This product is suitable for protecting surfaces in industrial and logistics facilities.
Growing Demand for Decorative Concrete Finishes
The popularity of decorative concrete surfaces is increasing in residential, commercial, and public spaces. Sealers enhance the appearance of polished and stained concrete while protecting against wear and environmental damage. Hotels, shopping malls, and modern homes are using sealers to achieve aesthetic appeal and durability. For instance, acrylic and polyurethane sealers provide glossy finishes and UV protection, making them ideal for both indoor and outdoor applications. The shift toward modern architectural designs with exposed concrete surfaces is fueling the market’s expansion in this segment.
- For instance, Evonik’s SITREN® Selfheal 455 is a concrete additive that incorporates bacterial spores (Bacillus subtilis) to promote self-healing. When water penetrates cracks, the microbes are activated and produce calcium carbonate, which can seal pores and fine cracks and reduce water penetration.
Rising Awareness of Surface Protection Benefits
Awareness of concrete protection solutions is growing among builders, facility managers, and homeowners. Sealers help reduce cracking, moisture penetration, freeze-thaw damage, and staining, improving overall durability. This leads to lower maintenance costs and extended structural life. Industrial and commercial operators increasingly invest in sealer applications to reduce downtime caused by surface repairs. For example, high-performance sealers are used in warehouses, factories, and logistics hubs to protect high-traffic surfaces. This growing understanding of long-term value is encouraging greater market penetration across multiple end-user segments.
Key Trends & Opportunities
Shift Toward Eco-Friendly and Low-VOC Sealers
Sustainability is becoming a defining trend in the concrete sealers market. Manufacturers are developing water-based, low-VOC, and non-toxic products that meet strict environmental standards. These sealers reduce harmful emissions and are safer for indoor use. Green building certifications are driving demand for eco-friendly sealing solutions in commercial and residential projects. For instance, many contractors prefer water-based polyurethane sealers for LEED-compliant buildings. As regulatory pressures increase globally, suppliers offering sustainable formulations are gaining a competitive edge in infrastructure and building projects.
- For instance, Synthomer, formerly Omnova Solutions, manufactures the Pliolite® 400 series of resins, which are used to formulate durable coatings with excellent weather and chemical resistance.
Integration of Advanced Sealer Technologies
Technological innovation is creating new opportunities in the market. Companies are introducing sealers with improved chemical resistance, faster curing times, and better bonding performance. Smart and self-healing sealers are also gaining attention for their ability to repair microcracks and enhance durability. For example, nano-based sealer formulations provide deep penetration and long-lasting protection against wear. These advanced solutions are ideal for high-stress applications like industrial floors, bridges, and pavements. Increased investment in R&D is expected to accelerate the adoption of high-performance sealer technologies.
- For instance, Sika offers both SikaFiber® products for reinforcing concrete and Sikagard® products for sealing and protecting concrete surfaces. Sikagard®-705 L is a silane-based penetrating sealer that reduces water absorption and chloride ion ingress into concrete.
Growing Adoption in Residential Renovation Projects
Rising renovation and remodeling activities present a strong opportunity for market expansion. Homeowners increasingly apply sealers to driveways, patios, garages, and decorative flooring to extend service life and enhance appearance. This trend is driven by the growing popularity of low-maintenance, long-lasting home improvement solutions. Easy-to-apply sealers are making inroads into the DIY segment, further expanding the customer base. Increased disposable incomes and urban lifestyle upgrades are also supporting residential demand, particularly in developed and emerging markets.
Key Challenges
High Cost of Advanced Sealer Products
Premium sealers with enhanced performance features come at a higher cost than conventional products. This can limit adoption, especially in cost-sensitive residential and small-scale infrastructure projects. Budget constraints often lead contractors to select low-cost alternatives with shorter lifespans. While advanced sealers offer better durability and protection, the high upfront investment remains a key barrier. Price-sensitive markets in developing regions face slower adoption rates, creating a gap between demand potential and actual market penetration for high-end sealer technologies.
Limited Skilled Workforce for Proper Application
The effectiveness of concrete sealers depends on correct surface preparation and application. A lack of trained professionals can lead to improper sealing, reducing performance and durability. Many construction workers are unfamiliar with advanced sealer technologies, resulting in inconsistent outcomes and increased maintenance costs. This skill gap is more evident in developing regions, where training programs and quality standards are limited. Without proper application, the benefits of sealers are diminished, slowing market growth and reducing customer satisfaction.
Regional Analysis
North America
North America holds the largest share of the global concrete sealers market at 34%. This leadership is driven by widespread use of advanced sealers in commercial, industrial, and infrastructure projects. The U.S. and Canada emphasize durable, low-maintenance construction solutions to meet strict building codes. Rising residential renovations and large-scale highway upgrades also support market expansion. Contractors prefer water-based, low-VOC sealers due to sustainability goals. Key manufacturers are investing in high-performance products with improved weather resistance, catering to harsh climate conditions. The strong presence of established construction companies further strengthens the regional demand base.
Europe
Europe accounts for 27% of the global concrete sealers market share. The region benefits from strong adoption of sustainable and eco-friendly sealing solutions. Strict environmental regulations, such as REACH compliance, drive demand for low-VOC products in residential and commercial applications. Countries like Germany, the UK, and France are leading adopters of advanced sealing technologies. Infrastructure modernization projects and heritage building preservation also boost the use of high-quality sealers. Manufacturers focus on performance and energy efficiency, supporting long-term structural durability. The growing emphasis on green construction continues to shape market trends across the region.
Asia Pacific
Asia Pacific holds 24% of the global concrete sealers market share. Rapid urbanization and infrastructure expansion in China, India, Japan, and Southeast Asia drive strong demand. Government investments in highways, bridges, airports, and housing projects are accelerating market growth. Contractors increasingly use sealers to improve surface durability and reduce maintenance costs. The shift toward modern construction practices is boosting the adoption of polyurethane and epoxy sealers. Rising awareness of surface protection benefits is also supporting market expansion. The presence of cost-competitive local producers further strengthens the region’s position in the global market.
Latin America
Latin America represents 9% of the global concrete sealers market share. Infrastructure development and commercial construction in Brazil, Mexico, and Argentina are the primary growth drivers. Government initiatives to upgrade transport networks and urban spaces are increasing demand for durable sealing solutions. The market is shifting from basic solvent-based sealers toward more advanced, water-based products. Economic reforms and growing foreign investments are also creating opportunities for product penetration. Although price sensitivity remains high, rising construction activity and modernization efforts support steady growth in this region.
Middle East & Africa
The Middle East & Africa hold a 6% share in the global concrete sealers market. Large infrastructure investments in GCC countries, including Saudi Arabia and the UAE, are driving adoption in highways, commercial complexes, and urban development projects. Hot and arid climates push demand for sealers with enhanced UV and heat resistance. Industrial and residential projects are also fueling product uptake in urbanizing economies. However, lower awareness levels and uneven market maturity limit broader penetration. As government-led infrastructure programs expand, the region is expected to experience steady growth in the coming years.
Market Segmentations:
By Product:
- Glass fibers
- Natural fibers
By Application:
- Pavement
- Shotcrete
By End User:
- Residential
- Roads & bridges
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the concrete sealers market is shaped by leading players such as Valspar Corp., Sika AG, BASF SE, Mapei Construction Products, Vexcon Chemicals, Inc., PPG Industries, Laticrete International, Evonik Industries, Omnova Solutions, and Arkema. The competitive landscape of the concrete sealers market is defined by strong product innovation and strategic expansion. Companies focus on developing high-performance, low-VOC, and water-based formulations to meet sustainability goals and regulatory standards. Many players invest in advanced R&D to enhance durability, chemical resistance, and weather protection, targeting both commercial and infrastructure projects. Strategic partnerships and acquisitions help strengthen global distribution networks and expand market presence. Manufacturers are also prioritizing training programs and technical support to improve product application. This combination of innovation, sustainability, and strategic growth continues to intensify competition across regional and international markets.
Key Player Analysis
- Valspar Corp.
- Sika AG
- BASF SE
- Mapei Construction Products
- Vexcon Chemicals, Inc.
- PPG Industries
- Laticrete International
- Evonik Industries
- Omnova Solutions
- Arkema
Recent Developments
- In January 2025, the Oil Sustainability Program, launched by the NovusCrete consortium, is a worldwide collaboration effort aimed at developing and increasing the adoption of durable and sustainable saltwater concrete.
- In November 2024, Cemex’s corporate venture capital (CVC) and open innovation unit, ‘Cemex Ventures,’ announced the initial hydrogen deployment at an industrial scale with HiiROC.
- In February 2024, Arkema and Sireg Geotech developed the bendable composite rebar. This is an innovative alternative to traditional steel reinforcement. Sireg's fiberglass bars developed Glasspree TP bars by using Arkema's Elium thermoplastic resin.
- In January 2024, JOGANI Reinforcement, a leading provider of crack control concrete fibers in India, received the patent for Blended Concrete Fibers that enhance vital parameters in concrete.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand steadily due to growing infrastructure and construction activities.
- Demand for eco-friendly and low-VOC sealers will increase with stricter environmental norms.
- Advanced sealer technologies with improved durability will gain strong adoption.
- Water-based sealers will continue to replace solvent-based products in multiple applications.
- Rising renovation and remodeling activities will boost residential segment growth.
- Digital tools and automation will enhance application efficiency and consistency.
- Manufacturers will expand distribution networks to strengthen their global presence.
- Strategic partnerships and mergers will support technology advancement and market reach.
- Asia Pacific will emerge as a key growth region due to rapid urbanization.
- Sustainable construction practices will shape product innovation and market strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Concrete Sealers Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Concrete Sealers Market projected to grow between 2025 and 2032?
Which Concrete Sealers Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Concrete Sealers Market?
Who are the leading companies in the Concrete Sealers Market?
Which region commanded the largest share of the Concrete Sealers Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Concrete Sealers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Concrete Sealers Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3.79 billion → 2032: USD 6.71 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Concrete Sealers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Concrete Sealers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Concrete Sealers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Concrete Sealers Market Drivers
- 3.3 Concrete Sealers Market Restraints & Challenges
- 3.4 Concrete Sealers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Concrete Sealers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Concrete Sealers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Concrete Sealers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Concrete Sealers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Concrete Sealers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Concrete Sealers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Concrete Sealers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Concrete Sealers Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Concrete Sealers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Concrete Sealers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Concrete Sealers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Concrete Sealers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Concrete Sealers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Concrete Sealers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Concrete Sealers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Concrete Sealers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Concrete Sealers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Concrete Sealers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Concrete Sealers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
