
Market Overview:
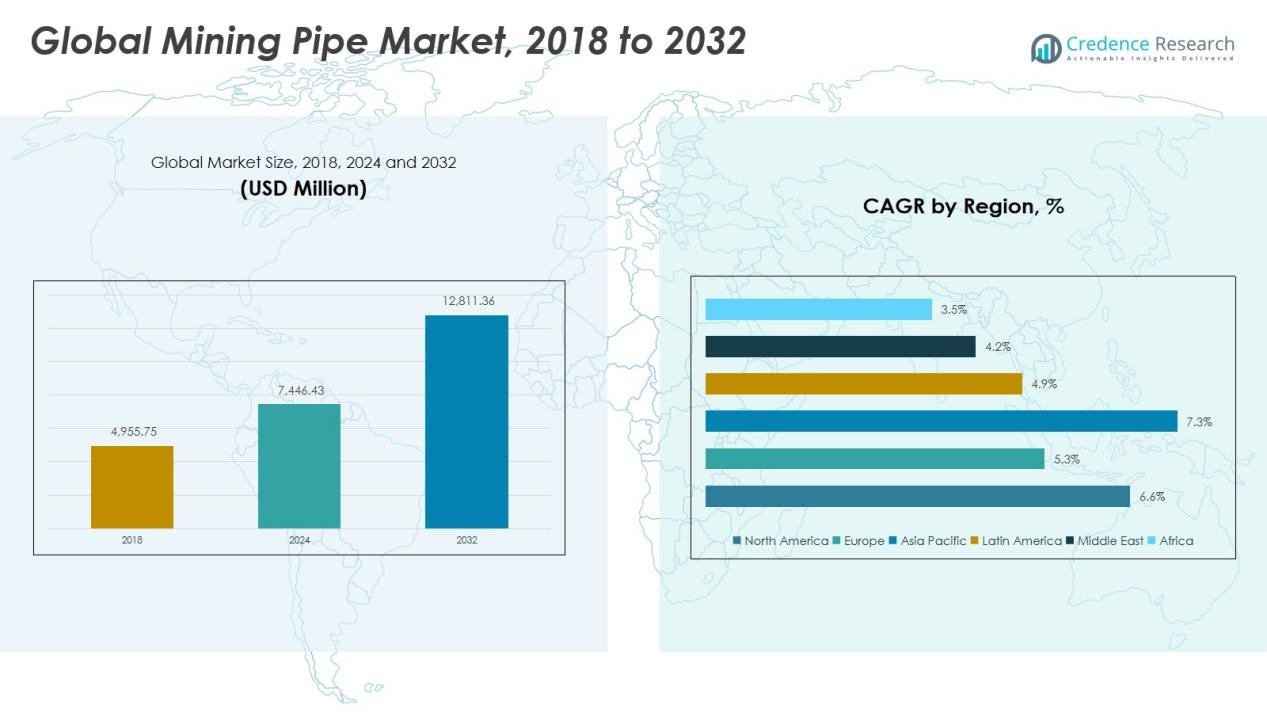
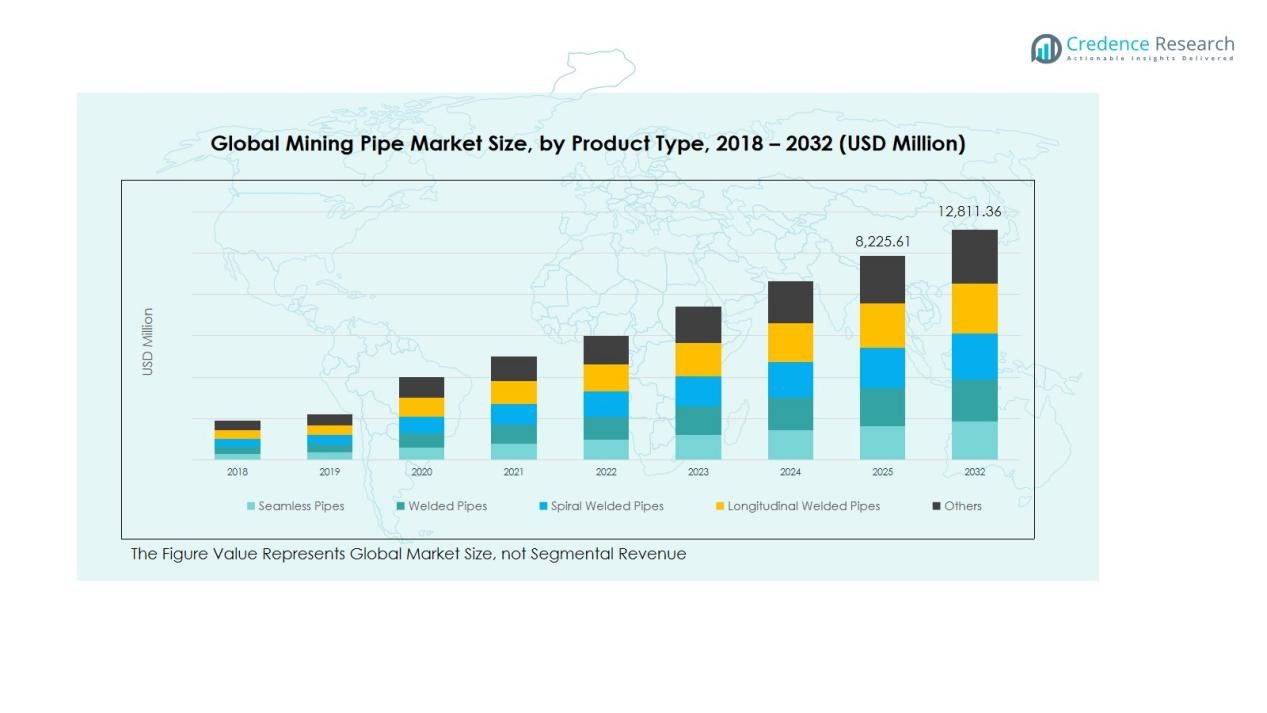
The Global Mining Pipe Market size was valued at USD 4,955.75 million in 2018 to USD 7,446.43 million in 2024 and is anticipated to reach USD 12,811.36 million by 2032, at a CAGR of 6.53% during the forecast period.| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Mining Pipe Market Size 2024 | USD 7,446.43 Million |
| Mining Pipe Market, CAGR | 6.53% |
| Mining Pipe Market Size 2032 | USD 12,811.36 Million |
Market Insights:
- The Global Mining Pipe Market was valued at USD 4,955.75 million in 2018, increased to USD 7,446.43 million in 2024, and is projected to reach USD 12,811.36 million by 2032, growing at a CAGR of 6.53% during the forecast period.
- Asia Pacific leads the market with a 43% share, driven by extensive mining activity in China, India, and Australia. North America follows with 27%, supported by advanced infrastructure and modernization of existing mining systems. Europe holds 18% due to strong environmental regulations and the shift toward sustainable materials.
- Asia Pacific remains the fastest-growing region, supported by rapid industrialization, government-backed mining expansion, and high adoption of HDPE and steel pipes.
- By product type, seamless pipes account for 38% of the market, favored for their strength and performance in high-pressure applications.
- By material type, steel pipes represent 45% of total revenue, reflecting their dominance in heavy-duty and abrasive mining environments.
Market Drivers:
Rising Demand for Durable and Corrosion-Resistant Materials The Global Mining Pipe Market experiences strong growth due to increasing demand for durable and corrosion-resistant materials. Mining operations expose pipelines to abrasive slurries, chemicals, and extreme conditions that shorten service life. Manufacturers focus on developing steel alloys, HDPE, and composite pipes that deliver superior abrasion resistance and long operational lifespan. It supports reduced maintenance frequency and lowers total ownership cost. The shift toward high-performance materials enhances safety and operational reliability in mineral transportation.- For instance, in the 2010s and early 2020s, Victaulic introduced their Series 725 (later 725S and 725T) diverter valves designed for mine backfill applications. These valves are used with abrasion-resistant piping systems, and in specific field tests, the Series 725T valve has been proven to handle over 2 million tons of paste without maintenance, demonstrating significantly extended life compared to traditional manual diversion methods or standard steel pipes.
- For instance, Weir Minerals installed over 1,700 meters of its Linatex rubber-lined slurry pipeline system at the Siguiri gold mine in Guinea in June 2023, increasing transport reliability and operational uptime for AngloGold Ashanti
Market Trends:
Adoption of Sustainable and Advanced Material Solutions The Global Mining Pipe Market witnesses a steady transition toward sustainable and advanced material solutions. Companies adopt HDPE, FRP, and thermoplastic composite pipes to replace conventional steel pipes. It improves resistance to corrosion, abrasion, and chemical exposure while lowering environmental impact. Manufacturers develop recyclable and eco-friendly pipe materials that meet stricter environmental regulations in key mining regions. Growing awareness of energy-efficient transport systems drives innovation in lightweight and flexible pipe construction. The adoption of lined and coated pipe variants supports reduced maintenance downtime and extended service life. This material shift strengthens supply reliability in remote and large-scale mining operations.- For instance, AGRU has previously supplied extensive HDPE piping systems, including its specialized MINELINE PE 100-RC pipes, for major copper mining projects in Chile.
- For instance, Siemens launched its Pipelines 4.0 integrated solution in 2017, combining automated pump and compressor station controls with digital twins and MindSphere IoT platform, enabling operators to optimize power consumption across midstream pipeline networks spanning multiple North American sites
Market Challenges Analysis:
High Installation Costs and Maintenance Complexity The Global Mining Pipe Market faces challenges related to high installation costs and complex maintenance requirements. Mining environments demand specialized materials, fittings, and equipment that increase upfront expenses. It limits adoption in small and mid-scale operations with restricted budgets. Harsh conditions such as high pressure, temperature fluctuations, and abrasive slurries accelerate wear, requiring frequent inspection. Remote mining sites further complicate replacement logistics and increase labor costs. The need for skilled technicians and precise installation standards raises overall project expenditure. These factors restrict growth in cost-sensitive developing markets. Environmental Regulations and Supply Chain Disruptions Strict environmental regulations pose hurdles for manufacturers and end users. It drives the need for compliance with emission, waste management, and sustainability standards. Producers must invest in clean production technologies and low-impact materials, adding to operational costs. Supply chain disruptions, including raw material shortages and transport delays, affect timely project execution. Political instability in mining regions also influences procurement reliability. The dependence on imported materials for polymer and alloy pipes increases vulnerability to trade fluctuations. These challenges continue to test resilience across the global mining supply network.Market Opportunities:
Expansion of Sustainable Mining and Infrastructure Projects The Global Mining Pipe Market offers strong opportunities through the expansion of sustainable mining and infrastructure projects. Governments and private firms focus on eco-efficient extraction and waste management systems. It creates demand for pipes that support water reuse, slurry transport, and tailings containment with minimal leakage. Companies introducing recyclable and low-carbon materials gain a competitive edge in meeting new environmental standards. Rapid industrialization across emerging economies encourages investments in long-term mining infrastructure. The adoption of durable, corrosion-resistant materials enables cost savings and operational reliability. Growing emphasis on responsible resource management further boosts product innovation across mining regions. Integration of Automation and Smart Pipeline Technologies Growing digital transformation in mining operations unlocks opportunities for advanced pipeline monitoring systems. It enables real-time data tracking, predictive maintenance, and improved safety across critical transport lines. Manufacturers integrating IoT, AI, and sensor-based systems expand value-added service offerings. Remote operations and autonomous mining technologies increase reliance on intelligent pipeline networks. The development of modular and pre-fabricated pipe systems enhances ease of installation and project scalability. Partnerships between technology providers and pipe manufacturers strengthen innovation capabilities. This integration trend supports efficiency, safety, and sustainability goals across global mining operations.Market Segmentation Analysis:
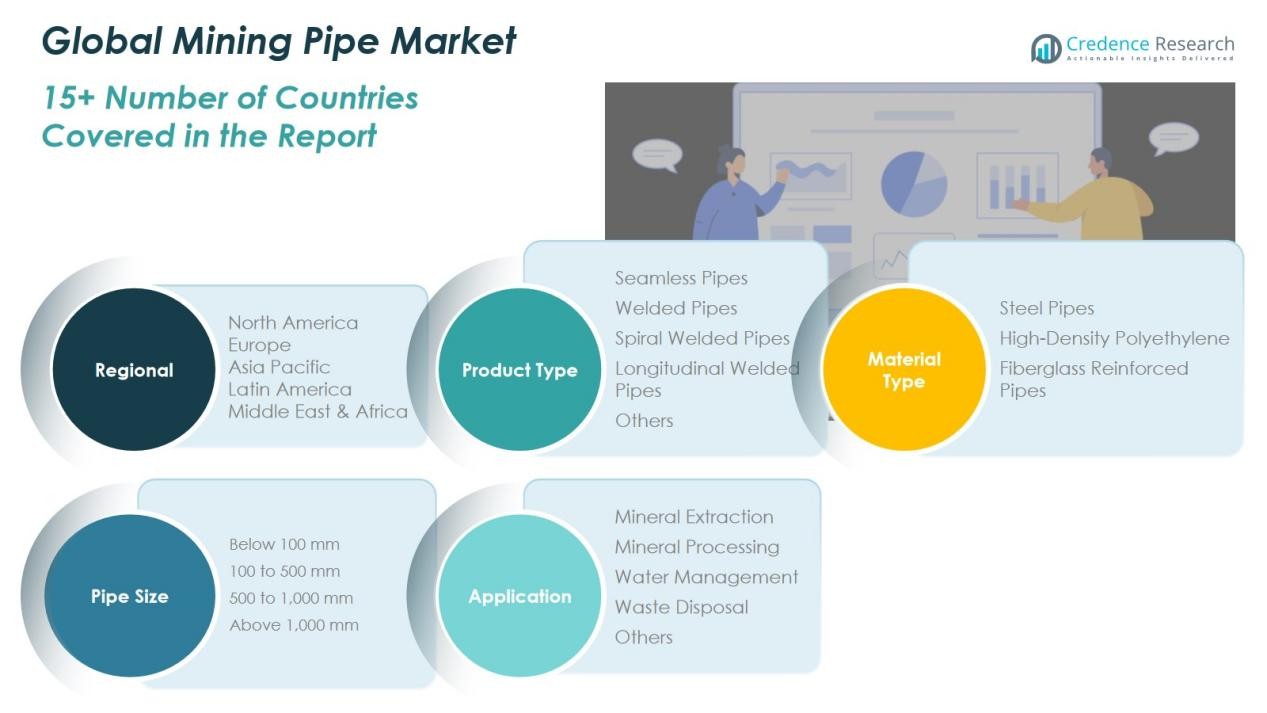
By Product Type The Global Mining Pipe Market is segmented into seamless, welded, spiral welded, longitudinal welded, and other pipe types. Seamless pipes dominate due to their strength and reliability in high-pressure applications. Welded and spiral welded pipes are gaining demand for cost-effectiveness and flexibility in large-scale slurry transport systems. It benefits mining operators by offering diverse choices that match operational and geological needs. Longitudinal welded pipes serve in long-distance transport where durability and pressure resistance are critical. The variety of product types enhances adaptability across both open-pit and underground mining projects.- For instance, Tenaris manufactures various TN grade seamless pipes, such as those used in high-pressure/high-temperature (HP/HT) oil and gas drilling operations, that are part of systems capable of withstanding pressures up to and exceeding 10,000 psi, depending on the specific pipe dimensions and grade.
- For Instance, For the Trans Mountain Expansion Project (TMEP), the primary steel pipe supplier for the bulk of the pipeline was EVRAZ North America, which supplied approximately 250,000 tonnes of pipe from its Regina, Saskatchewan plant, with most deliveries occurring well before the project's mechanical completion in late 2023 and early 2024.
Segmentations:
By Product Type- Seamless Pipes
- Welded Pipes
- Spiral Welded Pipes
- Longitudinal Welded Pipes
- Others
- Steel Pipes
- High-Density Polyethylene (HDPE)
- Fiberglass Reinforced Pipes (FRP)
- Below 100 mm
- 100 to 500 mm
- 500 to 1,000 mm
- Above 1,000 mm
- Mineral Extraction
- Mineral Processing
- Water Management
- Waste Disposal
- Others
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America The North America Mining Pipe Market size was valued at USD 1,418.51 million in 2018 to USD 2,097.65 million in 2024 and is anticipated to reach USD 3,624.33 million by 2032, at a CAGR of 6.6% during the forecast period. The region accounts for 27% of the global market share, supported by strong demand from the U.S. and Canada’s well-established mining industries. It benefits from advanced infrastructure, technological upgrades, and large-scale mineral extraction projects. Adoption of high-strength steel and polymer pipes remains widespread due to performance reliability and efficiency in slurry transport. Continuous modernization in mining hubs such as Nevada, Alberta, and Mexico strengthens regional consumption. Growing use of predictive maintenance and energy-efficient pipeline systems further enhances competitiveness across the region. Europe The Europe Mining Pipe Market size was valued at USD 923.48 million in 2018 to USD 1,311.45 million in 2024 and is anticipated to reach USD 2,051.33 million by 2032, at a CAGR of 5.3% during the forecast period. Europe captures 18% of the global market, driven by significant mining activity in Germany, Russia, and Poland. It emphasizes infrastructure modernization and adherence to stringent environmental standards. Rising demand for composite and corrosion-resistant materials aligns with the region’s focus on sustainability. Expansion of mineral recycling facilities and adoption of low-emission processes support market development. The trend toward lightweight and high-durability materials boosts innovation in pipeline design and production. Asia Pacific The Asia Pacific Mining Pipe Market size was valued at USD 2,167.37 million in 2018 to USD 3,376.81 million in 2024 and is anticipated to reach USD 6,163.80 million by 2032, at a CAGR of 7.3% during the forecast period. The region holds 43% of the global market share, led by China, India, and Australia. It benefits from rapid industrialization, rising mineral production, and heavy infrastructure investment. Government-backed exploration projects and favorable mining policies drive regional demand for advanced pipeline solutions. Growing preference for HDPE and steel pipes supports efficiency in slurry and tailings management. Local manufacturers continue investing in automation and corrosion-resistant materials to serve expanding mining operations. Latin America The Latin America Mining Pipe Market size was valued at USD 234.63 million in 2018 to USD 348.18 million in 2024 and is anticipated to reach USD 530.36 million by 2032, at a CAGR of 4.9% during the forecast period. The region represents 7% of the global market, with leading contributions from Chile, Peru, and Brazil. It experiences steady growth through copper, gold, and lithium mining projects requiring durable pipeline systems. International investment in sustainable extraction methods and processing facilities supports long-term expansion. It adopts FRP and HDPE piping to improve efficiency and cost management in remote operations. Ongoing modernization of legacy mining infrastructure provides additional growth opportunities. Middle East The Middle East Mining Pipe Market size was valued at USD 134.97 million in 2018 to USD 184.88 million in 2024 and is anticipated to reach USD 266.83 million by 2032, at a CAGR of 4.2% during the forecast period. The region contributes 4% of the global market share, driven by mineral development initiatives in Saudi Arabia, Turkey, and Iran. It focuses on diversifying resource portfolios beyond hydrocarbons. Dependence on imported materials persists, prompting investment in local manufacturing capabilities. The adoption of steel and composite pipes expands in water handling and mineral transport systems. Rising exploration of phosphate and bauxite reserves continues to strengthen future market potential. Africa The Africa Mining Pipe Market size was valued at USD 76.79 million in 2018 to USD 127.46 million in 2024 and is anticipated to reach USD 174.70 million by 2032, at a CAGR of 3.5% during the forecast period. The region accounts for 5% of the global market, led by South Africa, Nigeria, and Egypt. It gains momentum through expanding mining activities in gold, diamond, and copper sectors. Limited infrastructure and supply chain inefficiencies constrain large-scale deployment, yet investments are rising. Local pipe manufacturing capacity is improving under regional industrial programs. Demand for corrosion-resistant and long-life piping materials continues to grow, improving operational sustainability across African mines.Key Player Analysis:
- Vallourec S.A.
- Metalurgica Gerdau S.A.
- Georg Fischer Ltd.
- China National Petroleum Corporation (CNPC)
- PSL Limited
- Jindal Saw Ltd.
- Welspun Corp Limited
Competitive Analysis:
The Global Mining Pipe Market features a moderately consolidated structure with strong competition among established manufacturers. Major players include Vallourec S.A., Metalurgica Gerdau S.A., Georg Fischer Ltd., China National Petroleum Corporation (CNPC), PSL Limited, Jindal Saw Ltd., and Welspun Corp Limited. It is driven by technological advancement, capacity expansion, and strategic partnerships to strengthen global supply networks. Companies focus on producing high-strength, corrosion-resistant, and lightweight pipes to meet evolving mining requirements. Investments in automation and digital monitoring solutions improve operational performance and product differentiation. Mergers and regional collaborations enhance distribution efficiency and market penetration. Continuous innovation in composite materials and energy-efficient designs positions leading firms to capture emerging opportunities in sustainable mining infrastructure.Recent Developments:
- In October 2025, Vallourec S.A. won a major deepwater integrated contract with TechnipFMC in Brazil, supplying over 20,000 tons of subsea seamless premium carbon-steel line pipes for the Orca project operated by Shell Brasil.
- In February 2025, Gerdau S.A. completed the acquisition of the remaining shares in Gerdau Summit Aços Fundidos e Forjados S.A. from Sumitomo Corporation and The Japan Steel Works, which was a $32.6 million deal, giving Gerdau full ownership of the subsidiary.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Material Type, Pipe Size and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook:
- The Global Mining Pipe Market is expected to expand with growing investments in mineral exploration and extraction projects.
- Rising demand for durable, corrosion-resistant, and lightweight piping materials will drive product innovation.
- It will benefit from the transition toward sustainable mining practices and eco-friendly infrastructure development.
- Adoption of smart monitoring technologies and IoT-enabled pipeline systems will enhance operational safety.
- Manufacturers will focus on automation and digital integration to improve pipeline performance and lifespan.
- Emerging economies in Asia Pacific, Latin America, and Africa will offer new growth opportunities.
- It will experience higher demand for HDPE and composite pipes due to reduced maintenance and energy use.
- Companies will emphasize local production facilities to address supply chain and cost efficiency challenges.
- Environmental regulations will shape material choices, promoting recyclable and low-impact pipe solutions.
- Continued modernization of mining infrastructure will strengthen global demand for advanced pipeline systems.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Mining Operations
The growth of underground and open-pit mining projects worldwide is increasing the need for efficient and durable pipeline systems to transport minerals, slurry, and water, directly boosting demand for mining pipes.
Shift Toward Durable and Corrosion-Resistant Materials
Mining environments expose pipes to abrasive slurries and harsh chemicals, driving the adoption of steel alloys, HDPE, and composite pipes that offer superior abrasion and corrosion resistance, reducing maintenance costs and extending service life.
Technological Integration and Smart Monitoring
The integration of IoT sensors and smart monitoring technologies enables real-time tracking of pipe wear, leakage, and pressure, allowing predictive maintenance and minimizing operational downtime, which is increasingly valued by mining operators.
Focus on Energy Efficiency and Cost Optimization
Lightweight polymer and composite pipes reduce energy consumption in pumping and lower operational expenses, making them attractive for large-scale mining operations aiming to improve productivity and sustainability.
Regulatory Push for Sustainable Materials
Stricter environmental regulations and sustainability goals are prompting mining companies to adopt recyclable, low-impact, and energy-efficient pipe materials, driving innovation and market growth in advanced mining pipe solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Global Mining Pipe Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Mining Pipe Market projected to grow between 2024 and 2032?
Which segment held the largest share of the Global Mining Pipe Market in 2024?
What are the primary factors fueling the growth of the Global Mining Pipe Market?
Who are the leading companies in the Global Mining Pipe Market?
Which region commanded the largest share of the Global Mining Pipe Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Pipe Size
- 1.2.1 Below 100 mm
- 1.2.2 100 to 500 mm
- 1.2.3 500 to 1,000 mm
- 1.2.4 Above 1,000 mm
- 1.3 By Application
- 1.3.1 Mineral Extraction
- 1.3.2 Mineral Processing
- 1.3.3 Water Management
- 1.3.4 Waste Disposal
- 1.3.5 Others
- 1.4 By Product Type
- 1.4.1 Seamless Pipes
- 1.4.2 Welded Pipes
- 1.4.3 Spiral Welded Pipes
- 1.4.4 Longitudinal Welded Pipes
- 1.4.5 Others
- 1.5 By Material Type
- 1.5.1 Steel Pipes
- 1.5.2 High-Density Polyethylene (HDPE)
- 1.5.3 Fiberglass Reinforced Pipes (FRP)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 4,955.75 million → 2032: USD 12,811.36 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Mining Pipe Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Mining Pipe Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Mining Pipe Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Mining Pipe Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Mining Pipe Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Mining Pipe Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Mining Pipe Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Mining Pipe Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 4,955.75 million → 2032: USD 12,811.36 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Mining Pipe Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Pipe Size - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Below 100 mm
- 12.3.7.2 100 to 500 mm
- 12.3.7.3 500 to 1,000 mm
- 12.3.7.4 Above 1,000 mm
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Mineral Extraction
- 12.4.7.2 Mineral Processing
- 12.4.7.3 Water Management
- 12.4.7.4 Waste Disposal
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Seamless Pipes
- 12.5.7.2 Welded Pipes
- 12.5.7.3 Spiral Welded Pipes
- 12.5.7.4 Longitudinal Welded Pipes
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Material Type - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Volume Forecast, 2018-2032
- 12.6.5 Base-Year Market Share, 2018
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Steel Pipes
- 12.6.7.2 High-Density Polyethylene (HDPE)
- 12.6.7.3 Fiberglass Reinforced Pipes (FRP)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Mining Pipe End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Mining Pipe Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Mining Pipe Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Mining Pipe Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Vallourec S.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Metalurgica Gerdau S.A.
- 18.4 Georg Fischer Ltd.
- 18.5 China National Petroleum Corporation (CNPC)
- 18.6 PSL Limited
- 18.7 Jindal Saw Ltd.
- 18.8 Welspun Corp Limited
- 18.9 Tenaris
- 18.10 Weir Group
- 18.11 AGRU
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

