
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Control Room Solution Market Size 2023 | USD 53,028.80 Million |
| Control Room Solution Market, CAGR | 6.59% |
| Control Room Solution Market Size 2032 | USD 95,237.99 Million |
Market Overview
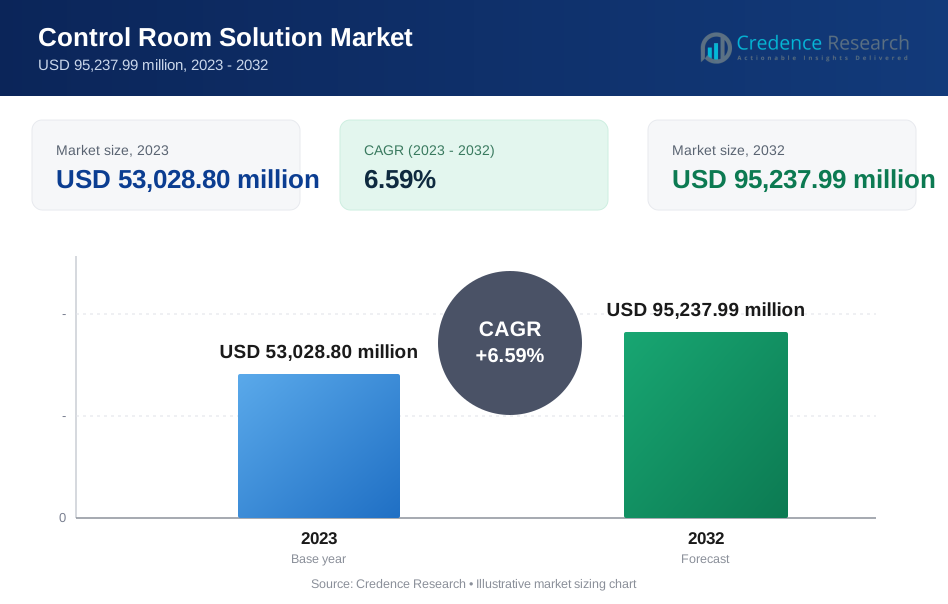
The global Control Room Solution Market is expected to grow from USD 53,028.80 million in 2023 to USD 95,237.99 million by 2032, at a compound annual growth rate (CAGR) of 6.59%.
The global control room solution market is driven by increasing demand for centralized monitoring systems across various industries, such as energy, transportation, and defense. The need for real-time data analysis, improved decision-making, and operational efficiency is fueling market growth. The rise in smart city initiatives, the adoption of Industry 4.0 technologies, and the growing importance of security and safety protocols are also contributing to the market’s expansion. Additionally, the integration of advanced technologies like AI, IoT, and machine learning in control room systems is enhancing automation, predictive analytics, and remote monitoring capabilities. As organizations prioritize streamlined operations, operational continuity, and risk mitigation, the demand for scalable and adaptable control room solutions is increasing. Furthermore, advancements in visualization technologies and user interfaces are driving the adoption of more sophisticated control room setups, offering better operational oversight and proactive decision-making capabilities.
The geographical analysis of the Global Control Room Solution market highlights the widespread adoption across key regions, driven by advancements in technology and increasing demand for operational efficiency and safety. Developed regions such as North America and Europe dominate the market due to their established infrastructure, focus on smart city initiatives, and high investment in modernizing control room solutions. Emerging economies in Asia-Pacific are experiencing rapid growth, fueled by industrial expansion, urbanization, and government initiatives for infrastructure development. Latin America and the Middle East & Africa are also gaining traction as industries in these regions adopt innovative solutions to enhance safety and operational management. Prominent market players, including Motorola Solutions, Hytera Communications, NEC Software Solutions, Christie Digital Systems, and Airbus, are actively introducing advanced technologies and tailored solutions to cater to diverse industry requirements. These players focus on innovation, strategic partnerships, and acquisitions to strengthen their market position globally.
Market Insights
- The Global Control Room Solution market is projected to grow from USD 53,028.80 million in 2023 to USD 95,237.99 million by 2032, at a CAGR of 6.59%.
- Increasing demand for operational efficiency and real-time monitoring drives the adoption of control room solutions across industries.
- Technological advancements, such as AI, IoT, and big data analytics, are transforming control room capabilities, enhancing decision-making and situational awareness.
- Key players like Motorola Solutions, NEC Software Solutions, and Airbus focus on innovation and strategic collaborations to expand their market presence.
- High initial investments and challenges in integrating diverse technologies act as restraints for market growth.
- North America and Asia-Pacific emerge as key regions due to advanced infrastructure and rapid urbanization, respectively.
- The market showcases a competitive landscape with players introducing tailored solutions to meet industry-specific and regional demands.
Market Drivers
Technological Advancements
Technological innovations are key drivers of growth in the global control room solution market. Artificial Intelligence (AI) and Machine Learning (ML) are revolutionizing operations by enabling predictive maintenance, advanced analytics, and automated decision-making. These technologies optimize workflows, reduce human error, and improve operational efficiency. The Internet of Things (IoT) plays a significant role by connecting an increasing number of devices, generating vast amounts of data that can be analyzed for actionable insights. Big Data Analytics further enhances decision-making by processing large datasets to identify trends, anomalies, and potential risks, allowing organizations to make informed decisions and improve overall performance.
Infrastructure Modernization and Smart City Initiatives
The need for infrastructure modernization is propelling the adoption of advanced control room solutions. Many critical infrastructure systems are aging and require upgrades to ensure reliability and efficiency. Additionally, the rise of smart city initiatives is driving the demand for control room solutions to manage urban infrastructure, transportation, and public safety. For instance, the Smart Cities Mission in India aims to develop urban areas with advanced technologies to improve quality of life. These solutions help optimize resource management, enhance the quality of services, and improve safety in urban environments, supporting the development of smarter, more efficient cities.
Rising Demand for Operational Efficiency and Safety
The demand for control room solutions is driven by the need for enhanced operational efficiency and safety across industries. These systems provide real-time visibility into operations, enabling proactive responses to incidents and potential threats. For instance, Yokogawa Electric Corporation emphasizes the importance of control room design in managing safety, health, and environmental risks. With advanced analytics and visualization tools, control rooms empower operators to make quick, accurate decisions, significantly improving decision-making processes. Furthermore, predictive maintenance helps identify issues before they escalate, reducing downtime, minimizing system failures, and leading to cost savings and increased productivity.
Growing Focus on Security and Surveillance
Security concerns are increasingly driving the adoption of advanced control room solutions. As security threats evolve, organizations require robust surveillance and monitoring systems to protect assets, personnel, and infrastructure. Industries like healthcare and finance, which face stringent regulatory requirements, rely heavily on these solutions to ensure compliance with industry standards and maintain security. Advanced control room solutions enable efficient monitoring, incident management, and reporting, addressing the growing need for security and surveillance in these sectors.
Market Trends
Integration of AI and Machine Learning
The integration of AI and Machine Learning is transforming control room operations, offering significant advancements in predictive analytics and automated decision-making. AI-powered systems can predict potential issues before they occur, enabling proactive maintenance and optimized operations. Additionally, AI algorithms analyze vast amounts of data, providing real-time insights that enhance situational awareness, allowing operators to respond swiftly and effectively to emerging situations. The ability to automate decision-making processes improves the speed and accuracy of decisions, ensuring more efficient control room management and reducing human error.
Rise of IoT and Big Data
The rise of the Internet of Things (IoT) and Big Data is playing a pivotal role in enhancing control room solutions. IoT devices are generating valuable data that allows for real-time monitoring and control, providing operators with instant visibility into operations and enabling quick response times. Coupled with Big Data analytics, these solutions offer data-driven insights that empower organizations to make more informed decisions, improving operational efficiency and productivity. Optimized resource allocation and streamlined workflows are further benefits, ensuring that control room operations run smoothly while minimizing operational costs.
Cybersecurity and Data Privacy
As control room systems become more interconnected and reliant on data, cybersecurity and data privacy have become top priorities. Ensuring robust security measures against cyber threats is crucial to protect sensitive data and maintain operational continuity. For instance, a review by SN Computer Science discusses the importance of cybersecurity and data privacy in interconnected systems, highlighting the need for robust measures to protect sensitive information. Organizations are also focusing on complying with data privacy regulations like GDPR and CCPA, safeguarding customer and organizational data. Incident response and recovery strategies are being implemented to minimize downtime and prevent data loss in the event of security breaches, ensuring that control room systems remain secure and resilient against evolving cyber threats.
Remote Monitoring and Control
The growing demand for flexibility and scalability is driving the adoption of remote monitoring and control solutions. The rise of remote work has further fueled the need for systems that enable remote access and collaboration, allowing operators to manage control room operations from anywhere. Cloud-based solutions are particularly beneficial, offering scalability, cost-effectiveness, and the ability to handle large amounts of data while maintaining security. Remote incident response capabilities enable organizations to manage and resolve issues without the need for on-site presence, improving operational efficiency and reducing the risk of disruptions.
Human-Machine Interface (HMI) Advancements
Advancements in Human-Machine Interface (HMI) technology are improving the way control room operators interact with systems. Intuitive user interfaces, designed for ease of use, streamline operations and enhance the user experience. The incorporation of Augmented Reality (AR) and Virtual Reality (VR) enables immersive visualization of data, aiding in better decision-making and situational awareness. Additionally, innovations like voice control are reducing cognitive load, allowing for hands-free operation that enhances productivity and reduces the chances of operator error.
Market Challenges Analysis
Technological and Integration Challenges
One of the primary challenges in the control room solution market is managing the vast amounts of data generated by IoT devices and other connected systems. The increasing volume of data can overwhelm control room systems, making it difficult to process and analyze the information effectively. As data overload becomes more common, there is a need for sophisticated systems that can filter and prioritize relevant data, ensuring operators can make informed decisions in real-time. Another significant challenge is cybersecurity. As control rooms become more connected, they become prime targets for cyberattacks. These threats can disrupt operations, compromise sensitive data, and lead to costly downtime. Protecting control room systems from such attacks requires robust cybersecurity measures, ongoing monitoring, and constant updates to stay ahead of evolving threats. Additionally, integrating various systems and technologies into a cohesive control room solution remains complex and resource-intensive. Disparate systems often have compatibility issues, making integration challenging and requiring specialized expertise and time-consuming efforts.
Human, Cost, and Compliance Challenges
Human factors also present notable challenges in control room operations. Operator fatigue is a significant concern, as long hours of constant monitoring of multiple screens can reduce alertness, increasing the likelihood of errors. This issue is compounded by the growing skill gap, as there is a shortage of skilled operators to manage increasingly complex systems. This shortage makes it harder to maintain operational efficiency and ensures that systems are run effectively. Furthermore, designing user-friendly interfaces in control rooms can be difficult, as systems become more sophisticated and require advanced functionality, which can overwhelm operators. On the cost side, the high initial investment needed to implement comprehensive control room solutions, including hardware, software, and installation, can deter many organizations from making the leap. Ongoing maintenance costs for updating and supporting control room systems further contribute to the financial burden. For instance, an Oracle survey found that cost reduction and improved remote work capabilities are significant drivers for EPM adoption. Additionally, demonstrating a solid return on investment (ROI) can be challenging, especially in industries where long-term investments are required. Compliance and regulatory issues add another layer of complexity, as different industries have specific regulations that must be adhered to when designing and implementing control room systems. Navigating data privacy and security regulations, such as GDPR and CCPA, can be costly and time-consuming, further complicating compliance efforts. Additionally, regular audits for compliance can drain resources and hinder operational focus.
Market Opportunities
The global control room solution market presents several growth opportunities driven by technological advancements and the increasing need for enhanced operational efficiency. The integration of AI, machine learning, and big data analytics offers a significant opportunity for control room solutions to provide predictive analytics, automate decision-making, and optimize operations. As industries continue to embrace digital transformation, the demand for advanced, data-driven solutions is on the rise. The increasing adoption of IoT devices also creates an opportunity to generate valuable real-time data, enabling better monitoring, predictive maintenance, and streamlined workflows. Organizations are looking to improve situational awareness and decision-making, further fueling the need for sophisticated control room systems.
Another key opportunity lies in the expansion of smart city initiatives and infrastructure modernization. As cities and critical infrastructure around the world undergo upgrades, there is a growing demand for control room solutions to manage urban environments, transportation, public safety, and utilities more effectively. These solutions help optimize resource management, improve safety, and enhance service delivery. Additionally, with the shift towards remote work and the growing need for flexible, cloud-based solutions, control room systems that enable remote monitoring and incident management are becoming increasingly popular. The emphasis on security and surveillance due to evolving threats also presents opportunities for control room solutions, as organizations seek to protect assets and comply with stringent regulations. These trends position the market for continued growth, with opportunities across various sectors, including energy, healthcare, transportation, and manufacturing.
Market Segmentation Analysis:
By End-user:
The end-user segment of the global control room solution market includes government, critical infrastructure, commercial/civil, and others. The government sector represents a significant share, driven by the increasing need for robust surveillance and monitoring systems to enhance public safety and national security. Critical infrastructure, such as energy, transportation, and utilities, is another key segment due to its reliance on real-time monitoring and predictive analytics for efficient operations and incident management. The commercial and civil sectors are witnessing growing adoption of control room solutions for applications like facility management, retail operations, and event security, ensuring streamlined operations and improved safety. Other sectors, including healthcare and education, also contribute to the market growth, leveraging control room solutions for operational efficiency and compliance.
By Enterprise Size:
The enterprise size segment categorizes control room solutions by their adoption in small, medium, large, and very large enterprises. Small enterprises, ranging from 1 to 99 employees, are increasingly adopting cost-effective and cloud-based control room solutions to improve operational efficiency. Medium-sized enterprises, with 100 to 499 employees, benefit from tailored solutions that support scaling operations and meeting industry-specific needs. Large enterprises, with over 500 employees, represent a significant market share due to their capacity to invest in advanced technologies, including integrated platforms and AI-driven analytics. Very large enterprises, with more than 1,000 employees, lead the adoption of control room solutions, leveraging sophisticated systems to manage complex operations, enhance security, and ensure regulatory compliance.
Segments:
Based on End-user:
- Government
- Critical Infrastructure
- Commercial/Civil
- Others
Based on Enterprise Size:
- Small Enterprises (1 to 9 employees)
- Small Enterprises (10 to 99 employees)
- Medium-Sized Enterprises (100 to 499 employees)
- Large Enterprises (500 to 999 employees)
- Very Large Enterprises (1000+ employees)
Based on Deployment:
- Cloud
- On-Premise
- Hybrid
Based on Solution:
- Integrated Control Room Platforms
- Standalone Software
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America holds the largest share in the global control room solution market, accounting for approximately 35%. The region's dominance is driven by rapid technological advancements and significant investments in infrastructure modernization. The presence of leading players and the high adoption of AI, IoT, and big data analytics contribute to the market's growth. The U.S. leads the region, with robust demand from sectors such as government, critical infrastructure, and healthcare. Additionally, the focus on cybersecurity and compliance with stringent regulations further drives the adoption of advanced control room solutions across various industries.
Europe is the second-largest market, with a share of around 28%, attributed to the increasing adoption of smart city initiatives and advancements in industrial automation. Countries like Germany, France, and the UK are at the forefront of implementing control room solutions in sectors such as energy, transportation, and manufacturing. The region also emphasizes sustainability, with a growing preference for energy-efficient systems. Furthermore, regulatory frameworks like GDPR drive investments in secure and compliant control room technologies, enhancing market growth across the region.
Asia-Pacific is emerging as a rapidly growing market, projected to witness the highest CAGR during the forecast period. With a market share of approximately 20%, the region benefits from increased infrastructure development, particularly in countries like China, India, and Japan. Government initiatives to enhance public safety, coupled with investments in transportation, utilities, and smart city projects, fuel the demand for control room solutions. Additionally, the rise of local players and the growing adoption of cloud-based solutions contribute to the region's significant growth potential.
Latin America and the Middle East & Africa (LAMEA) account for the remaining market share, collectively representing approximately 17%. Latin America shows promising growth due to urbanization and infrastructure upgrades, particularly in Brazil and Mexico. Similarly, the Middle East & Africa are adopting control room solutions to support large-scale projects in oil and gas, transportation, and smart city development. Countries such as the UAE and Saudi Arabia are spearheading adoption through investments in modern technologies to enhance operational efficiency and public safety. While challenges like limited technological infrastructure persist, these regions continue to present untapped opportunities for growth.
Key Player Analysis
- Motorola Solutions, Inc.
- Hytera Communications Corporation Limited
- NEC Software Solutions
- Christie Digital Systems USA, Inc.
- Regola
- Black Box
- Mauell GmbH
- 3tc Software
- Mistral Solutions Pvt. Ltd.
- Haivision
- ALE International
- IHM A/S
- Airbus
- Motilde
Competitive Analysis
The competitive landscape of the Global Control Room Solution market is marked by the presence of several prominent players, including Motorola Solutions, Hytera Communications Corporation Limited, NEC Software Solutions, Christie Digital Systems USA, Inc., Airbus, and Black Box. These companies focus on leveraging technological advancements such as artificial intelligence, IoT, and big data analytics to deliver innovative solutions tailored to diverse industries. Strategic partnerships, mergers, and acquisitions are key strategies adopted by leading players to enhance their market presence and broaden their product portfolios. For instance, collaborations with technology providers enable the integration of advanced analytics and visualization tools, improving efficiency and operational control. Additionally, companies emphasize investments in research and development to stay ahead in delivering state-of-the-art solutions that cater to modern infrastructure and smart city initiatives. For instance, a report by the International Federation of Automatic Control (IFAC) discusses the importance of research and development in shaping the future of control room technologies. Regional expansions also play a critical role in their growth strategies, targeting emerging markets in Asia-Pacific, Latin America, and the Middle East & Africa, where industrialization and infrastructure development are accelerating demand. Despite stiff competition, the market is characterized by a commitment to addressing challenges such as cybersecurity threats and integration complexities, ensuring robust and scalable solutions for end-users across industries.
Recent Developments
- In May 2024, Motorola Solutions unveiled several new innovations at Critical Communications World 2024 (CCW) in Dubai.
- In July 2024, Motorola Solutions announced the acquisition of Noggin, a global provider of critical event management software.
- In May 2024, Hytera won the ICCAs 2024 Award for its Interconnected MCS and TETRA Systems for Leading Steel Manufacturer.
- In August 2024, Black Box highlighted its next generation of AV and KVM solutions at Integrate Australia 2024.
- In December 2022, Hytera announced the commencement of its 30th anniversary with the first round of new product launches in 2023.
Market Concentration & Characteristics
The Global Control Room Solution market exhibits a moderately concentrated structure, with several prominent players driving innovation and competition. Key characteristics of this market include a strong focus on technological integration, such as artificial intelligence (AI), Internet of Things (IoT), and advanced analytics, to meet the increasing demand for operational efficiency and real-time monitoring across various industries. Leading companies, including Motorola Solutions, Hytera Communications, and Christie Digital Systems, maintain a significant market share due to their extensive product portfolios and robust research and development capabilities.
The market is characterized by a dynamic shift toward customizable and scalable solutions to cater to diverse end-user needs, such as government agencies, critical infrastructure, and commercial entities. Regional disparities in adoption rates also highlight the market’s global complexity, with mature markets like North America and Europe showcasing high adoption of cutting-edge technologies, while Asia-Pacific and Latin America are rapidly growing due to urbanization and smart city initiatives. Despite opportunities, the market faces challenges such as high initial costs, cybersecurity risks, and integration complexities. However, companies address these issues through strategic partnerships, enhanced cybersecurity measures, and continuous innovation. As digital transformation accelerates globally, the market is poised for steady growth, marked by increasing consolidation and heightened competition.
Report Coverage
The research report offers an in-depth analysis based on End-user, Enterprise Size, Deployment and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Global Control Room Solution market is expected to witness robust growth, driven by advancements in AI, IoT, and big data analytics.
- Integration of smart technologies will enhance operational efficiency and decision-making capabilities across industries.
- Increasing investments in smart cities and infrastructure modernization will fuel demand for advanced control room solutions.
- Rising cybersecurity concerns will drive the adoption of secure and resilient control room technologies.
- Customizable and scalable solutions will gain prominence to meet the diverse needs of various end-user industries.
- Cloud-based and hybrid control room solutions are anticipated to see significant adoption due to their flexibility and cost-effectiveness.
- Emerging economies will experience rapid growth in the control room market, supported by urbanization and digital transformation initiatives.
- Remote monitoring and control capabilities will remain crucial in addressing post-pandemic operational shifts.
- Industry players will continue to focus on innovation and partnerships to tackle challenges like integration complexity and high initial costs.
- Enhanced user experience through advancements in human-machine interfaces and immersive technologies like AR and VR will shape the market's future.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Control Room Solution market?
What factors are driving the growth of the Global Control Room Solution market?
What are the key segments within the Global Control Room Solution market?
What are some challenges faced by the Global Control Room Solution market?
Who are the major players in the Global Control Room Solution market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Control Room Solution Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Control Room Solution Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 53,028.80 million → 2032: USD 95,237.99 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Control Room Solution Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Control Room Solution Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Control Room Solution Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Control Room Solution Market Drivers
- 3.3 Control Room Solution Market Restraints & Challenges
- 3.4 Control Room Solution Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Control Room Solution Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Control Room Solution Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Control Room Solution category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Control Room Solution Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Control Room Solution Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Control Room Solution market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Control Room Solution Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Control Room Solution Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Control Room Solution Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Control Room Solution (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Control Room Solution Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Control Room Solution Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Control Room Solution Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Control Room Solution Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Control Room Solution Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Control Room Solution Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Control Room Solution Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Control Room Solution Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Control Room Solution Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
