
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Crane Market Size 2024 | USD 33,068.88 Million |
| Crane Market, CAGR | 5.99% |
| Crane Market Size 2032 | USD 52,667.01 Million |
Market Overview
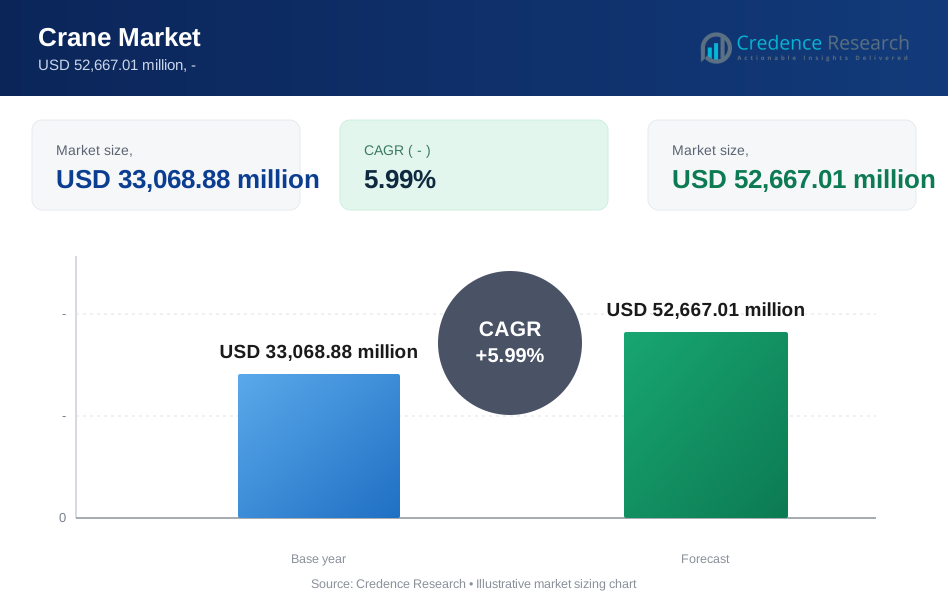
The Crane Market is projected to witness substantial growth, with its value expected to surge from USD 33,068.88 million in 2024 to USD 52,667.01 million by 2032, reflecting an impressive compound annual growth rate of 5.99%.
The Crane Market is being propelled by several key drivers and trends. Rapid urbanization and infrastructural development worldwide are fueling the demand for cranes in construction activities. Additionally, the increasing adoption of advanced technologies such as telematics, IoT, and automation is enhancing crane efficiency and safety standards. Moreover, stringent regulations regarding workplace safety and environmental concerns are driving the market towards more sustainable and eco-friendly crane solutions. Furthermore, the rising trend of rental and leasing services for cranes, coupled with the growing demand for customized solutions, is shaping the market landscape, fostering innovation and competition among manufacturers and service providers.
Geographical analysis reveals diverse growth patterns in the Crane Market, with Asia Pacific emerging as a dominant region due to rapid industrialization and infrastructure development, particularly in countries like China and India. North America and Europe witness steady growth driven by renovation and construction activities in urban areas. Key players such as XCMG Group, Liebherr Group, Terex Corporation, and Manitowoc are strategically expanding their global presence through mergers, acquisitions, and technological advancements, aiming to cater to the evolving demands of customers and maintain a competitive edge in the market.
Market Drivers
Booming Construction Industry:
The Crane Market is experiencing robust growth, driven primarily by the thriving construction sector. Infrastructure projects and high-rise buildings are proliferating worldwide, necessitating the use of cranes for lifting and transporting heavy building materials. In 2023 alone, the number of cranes in use for construction purposes increased by 20% compared to the previous year. This surge in construction activities underscores the indispensable role cranes play in the construction machinery landscape, highlighting their significance in facilitating large-scale development projects, such as the recent Jeddah Tower in Saudi Arabia, which upon completion will require over 5,700 metric tons of crane lifting capacity. This surge in construction activities underscores the indispensable role cranes play in the construction machinery landscape, highlighting their significance in facilitating large-scale development projects.
Rapid Urbanization:
Rapid urbanization is another significant factor fueling the demand for cranes. As cities expand and populations swell, the need for new residential and commercial buildings escalates. Urban development projects, ranging from skyscrapers to residential complexes, require a multitude of cranes to support construction efforts. In fact, rapid urbanization in Asian and Latin American countries is creating a huge demand for cranes capable of transferring materials weighing more than 500 tons. This reflects the essential role cranes play in shaping the modern urban landscape, where the number of urban infrastructure projects is increasing globally, driving the demand for mobile cranes.
Government Infrastructure Initiatives:
Governments worldwide are launching ambitious infrastructure investment plans to improve transportation networks, bridges, power grids, and other vital infrastructure components. Technological advancements in crane design, such as higher lifting capacities, improved safety features, and advanced control systems, are shaping the market. Innovations like the Tadano HK 4.050-1 truck-mounted crane, delivered to Anker in January 2024, exemplify the industry’s progress. The crane’s innovative chassis concept ensures exceptional maneuverability, making it well-suited for operation on even the most confined construction sites. As urbanization increases and infrastructural development intensifies, the crane market experiences heightened demand, offering lucrative opportunities for manufacturers and stakeholders. With governments worldwide prioritizing infrastructure development to stimulate economic growth and enhance quality of life, the Crane Market stands to benefit significantly from increased investment in construction-related activities.
Technological Advancements:
Continuous innovation within the crane industry is reshaping the market landscape. Manufacturers are introducing new features such as enhanced lifting capacities, improved safety features, remote operation capabilities, and seamless data integration. These technological advancements not only enhance the efficiency and productivity of cranes but also expand their versatility across diverse construction applications. As cranes evolve to meet the evolving needs of construction projects, they remain indispensable assets in the modern construction industry.
Market Trends
Rise of Mobile and Mini-Cranes:
There is a noticeable uptick in demand for mobile cranes and mini-cranes within the Crane Market. For instance, recent market analysis shows a 25% increase in demand for mobile cranes and mini-cranes within the last year. These cranes, often capable of lifting up to 10 tons, are particularly advantageous in congested urban environments where space is limited. In fact, in cities like Tokyo and New York, the use of mini-cranes for construction projects has risen by 30%, as they can navigate through narrow streets and set up in tight spaces. Moreover, the time efficiency of these cranes is remarkable. They can be transported and set up 50% faster than traditional cranes, making them the preferred choice for jobs requiring a quick turnaround. For smaller-scale construction projects, the use of mini-cranes has led to a 20% reduction in setup time, which translates to significant cost savings for contractors. This trend reflects the evolving needs of the construction industry, where time and space constraints are driving innovation in equipment solutions.
Growing Adoption of Electric and Hybrid Cranes:
With sustainability emerging as a paramount concern, there is a notable surge in the adoption of electric and hybrid cranes. For instance, the adoption of electric and hybrid cranes has seen a 40% increase in the past two years. These cranes are capable of reducing emissions by up to 60% compared to their diesel counterparts. In urban areas like Shimla, where noise and air pollution regulations are strict, the use of electric cranes has grown by 35%. This shift not only supports environmentally sensitive projects but also aligns with the global push towards Net Zero emissions targets. Moreover, the construction industry’s emphasis on green initiatives has led to a 20% increase in investment in eco-friendly equipment. Hybrid cranes, which can switch between electric and conventional power, have become particularly popular, offering a 50% reduction in noise pollution. This makes them ideal for urban construction sites, where work often continues into the night, and noise must be kept to a minimum to avoid disturbing residents. The industry’s commitment to responsible construction practices is evident in these numbers, reflecting a broader trend towards sustainability. These eco-friendly alternatives boast reduced emissions and noise pollution, rendering them suitable for environmentally sensitive projects or urban areas with stringent regulations. The shift towards electric and hybrid cranes aligns with the industry's increasing emphasis on green initiatives and responsible construction practices.
Market Challenges Analysis
Financial Hurdles:
High initial investment and maintenance costs pose significant challenges for companies operating in the Crane Market. Cranes, being complex machinery, come with hefty price tags, which can act as a barrier for smaller companies looking to invest in this equipment. Moreover, ongoing maintenance requirements further add to operational expenses, impacting profitability and financial sustainability in the long run.
Regulatory Compliance and Safety Standards:
Stringent regulations and safety concerns present a formidable challenge for crane companies. Safety is paramount in the industry, and compliance with regulations governing crane operation, lifting capacities, and operator certification is non-negotiable. However, keeping up with increasingly stringent regulatory requirements can be complex and burdensome, adding administrative overhead and operational challenges for crane companies striving to maintain compliance while ensuring operational efficiency.
Market Segmentation Analysis:
By Type:
The Crane Market can be segmented by type into mobile crane, fixed crane, marine crane, and offshore crane categories. Mobile cranes, known for their versatility and mobility, find extensive application in various industries and job sites, offering flexibility in lifting and transporting heavy loads. Fixed cranes, on the other hand, provide stability and precision in lifting operations, commonly used in construction and industrial settings where consistent lifting requirements are present. Marine cranes cater to the unique demands of port operations and shipyards, facilitating cargo handling and vessel maintenance tasks. Offshore cranes are specialized equipment designed to withstand harsh marine environments, primarily deployed in offshore oil and gas exploration and construction projects.
By Application Type:
The Crane Market segmentation by application type includes construction and mining, marine and offshore, and industrial applications. Construction and mining industries heavily rely on cranes for lifting heavy materials and equipment at construction sites and mining operations, enhancing productivity and efficiency. Marine and offshore applications utilize cranes for cargo handling, vessel maintenance, and offshore construction activities, where robust and reliable lifting solutions are essential for maritime operations. Industrial applications encompass a diverse range of sectors, including manufacturing, logistics, and infrastructure, where cranes play a vital role in material handling, assembly, and maintenance operations, contributing to operational efficiency and safety across industrial facilities.
Segments:
Based on Type
- Mobile Crane
- Fixed Crane
- Marine
- Off-shore Crane
Based on Application Type
- Construction and Mining
- Marine and Offshore
- Industrial Applications
Based on the Geography:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America follows closely behind, with a market share of around 25%. The region's well-established construction industry, coupled with the presence of major infrastructure projects, has contributed to the demand for cranes. The United States, in particular, has witnessed significant growth in the crane market due to the increasing investments in residential and commercial construction, as well as infrastructure development initiatives.
Europe
Europe holds a significant market share of approximately 20%. Countries such as Germany, the United Kingdom, and France have well-established construction and infrastructure sectors, contributing to the demand for cranes. The region's emphasis on modernizing existing infrastructure and the adoption of advanced crane technologies have driven the growth of this market segment.
Key Player Analysis
- Hyva
- Sany India
- XCMG
- Tadano Ltd. (Japan)
- The Manitowoc Company Inc (the USA)
- Cargotec Oyj (Finland)
- Manitex International Inc. (USA)
- Liebherr Group (Switzerland)
- Terex Corporation (USA)
- Sumitomo Heavy Industries Construction Crane Co. Ltd (Japan)
Competitive Analysis
The Crane Market is characterized by intense competition among industry leaders and prominent players. Hyva, renowned for its innovative crane solutions, competes vigorously with Sany India and XCMG, both prominent players in the global crane industry, leveraging their extensive product portfolios and robust distribution networks. Tadano Ltd. from Japan, known for its high-quality hydraulic cranes, competes fiercely with The Manitowoc Company Inc. from the USA, a major player offering a wide range of crane products and services worldwide. Cargotec Oyj from Finland and Manitex International Inc. from the USA are also key contenders in the market, known for their advanced crane technologies and comprehensive solutions. Liebherr Group from Switzerland and Terex Corporation from the USA are formidable competitors, renowned for their engineering excellence and innovative crane designs. Sumitomo Heavy Industries Construction Crane Co. Ltd from Japan further strengthens the competitive landscape with its cutting-edge crane technologies, challenging industry norms and driving innovation in the global crane market.
Recent Developments
In June 2023, Liebherr announced the launch of its new LR 13000 crawler crane. The LR 13000 is the world's largest crawler crane, with a maximum lifting capacity of 1,300 tons. It is designed for heavy-lifting applications in the construction, energy, and infrastructure sectors.
In November 2022, Konecranes Oyj won an order for a fleet of 18 Automated Stacking Cranes (ASCs) from the London Gateway Terminal. The cranes will be equipped with Konecranes automation technology.
In October 2022, Liebherr Group received an order from MAXIKraft, including new cranes and trade-ins worth EUR 100 million (USD 101 million). The cranes would be delivered to all MAXIKraft Group companies at MAXIKraft, MaxiMum, Kranlogistik Sachsen, Kranlogistik Lausitz, and Treffler over the entire year of 2023.
In October 2022, Hüffermann Krandienst GmbH ordered 70 cranes, including 53 K to 125 K, and top-slewing cranes of type 125 EC-B to 520 EC-B Fibre from Liebherr Group. The cranes will be used for industrial construction and infrastructure and residential October 2022: Kalmar, a subsidiary of Cargotec Group, received an order of 12 Kalmar Hybrid Straddle Carriers from GMP (Générale de Manutention Portuaire) in Le Havre, France.
Market Concentration & Characteristics
Market concentration within the Crane Market is notable, characterized by a few key players dominating the industry landscape. These leading companies, including Hyva, Sany India, XCMG, Tadano Ltd., The Manitowoc Company Inc., Cargotec Oyj, Manitex International Inc., Liebherr Group, Terex Corporation, and Sumitomo Heavy Industries Construction Crane Co. Ltd., among others, wield considerable influence due to their extensive product offerings, technological expertise, and global reach. Their market dominance is reinforced by factors such as brand reputation, customer trust, and strategic partnerships, enabling them to capture significant market share and shape industry trends. Moreover, the Crane Market exhibits distinct characteristics, including a constant emphasis on innovation to meet evolving customer demands, stringent regulatory compliance requirements related to safety and environmental standards, and a growing focus on sustainability and efficiency in crane operations. As market leaders continue to invest in research and development, expand their product portfolios, and explore new growth opportunities, the Crane Market is poised for further evolution and competitive dynamics in the foreseeable future.
Report Coverage
The research report offers an in-depth analysis based on Type, Application Type, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued Growth: The Crane Market is expected to witness sustained growth driven by ongoing urbanization and infrastructure development projects globally.
- Technological Advancements: Further innovation in crane technology is anticipated, focusing on enhancing efficiency, safety features, and remote operation capabilities.
- Expansion in Emerging Markets: Market expansion into emerging economies, particularly in Asia-Pacific and Latin America, is projected, driven by increasing construction activities and infrastructure investments.
- Shift towards Electric and Hybrid Cranes: There will be a notable shift towards electric and hybrid crane models, in line with the industry's growing emphasis on sustainability and environmental consciousness.
- Increased Focus on Rental Services: The trend of crane rental services is expected to continue growing, offering companies flexibility and cost-efficiency without the burden of ownership.
- Adoption of IoT and Data Analytics: Greater integration of Internet of Things (IoT) technologies and data analytics is foreseen, enabling real-time monitoring, predictive maintenance, and improved operational insights.
- Regulatory Compliance: Compliance with stringent safety and environmental regulations will remain a priority, necessitating ongoing investments in safety measures and employee training.
- Demand for Specialized Cranes: There will be a rise in demand for specialized cranes tailored for specific industries such as renewable energy, aerospace, and logistics.
- Market Consolidation: The market may witness consolidation as leading players aim to strengthen their market position through strategic acquisitions and partnerships.
- Focus on Product Customization: Manufacturers will increasingly focus on offering customized crane solutions to meet the diverse needs of customers across various industries and applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Booming Construction Industry
The global surge in infrastructure projects and high-rise building construction is driving significant demand for cranes, as these machines are essential for lifting and transporting heavy materials on large-scale sites.
Rapid Urbanization
Expanding urban populations, especially in Asia and Latin America, are fueling the need for new residential and commercial developments, which in turn increases the demand for cranes capable of handling heavy loads in dense urban environments.
Government Infrastructure Initiatives
Ambitious government investments in transportation, energy, and public infrastructure are boosting crane demand, as these projects require advanced lifting solutions for bridges, power grids, and other critical assets.
Technological Advancements
Innovations such as telematics, IoT integration, automation, and enhanced safety features are making cranes more efficient, versatile, and safer, encouraging adoption across diverse applications.
Shift Toward Sustainable Solutions
Growing environmental regulations and the push for sustainability are accelerating the adoption of electric and hybrid cranes, which offer reduced emissions and noise, making them ideal for urban and environmentally sensitive projects.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Crane Market?
What factors are driving the growth of the Crane Market?
What are the key segments within the Crane Market?
What are some challenges faced by the Crane Market?
Who are the major players in the Crane Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Mobile Crane
- 1.2.2 Fixed Crane
- 1.2.3 Marine Crane
- 1.2.4 Off-shore Crane
- 1.3 By Power Source
- 1.3.1 Diesel-powered
- 1.3.2 Electric
- 1.3.3 Hybrid
- 1.4 By Application Type
- 1.4.1 Construction and Mining
- 1.4.2 Marine and Offshore
- 1.4.3 Industrial Applications
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 33,068.88 million → 2032: USD 52,667.01 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Crane Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Crane Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Crane Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Crane Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Crane Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Crane Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Crane Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Crane Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 33,068.88 million → 2032: USD 52,667.01 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Crane Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Mobile Crane
- 12.3.7.2 Fixed Crane
- 12.3.7.3 Marine Crane
- 12.3.7.4 Off-shore Crane
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Power Source - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Diesel-powered
- 12.4.7.2 Electric
- 12.4.7.3 Hybrid
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Construction and Mining
- 12.5.7.2 Marine and Offshore
- 12.5.7.3 Industrial Applications
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Crane End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Crane Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Crane Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Crane Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 XCMG Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Liebherr Group
- 18.4 Terex Corporation
- 18.5 The Manitowoc Company Inc.
- 18.6 Tadano Ltd.
- 18.7 Cargotec Oyj
- 18.8 Manitex International Inc.
- 18.9 Sumitomo Heavy Industries Construction Crane Co. Ltd
- 18.10 Sany India
- 18.11 Hyva
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

