
Market Overview
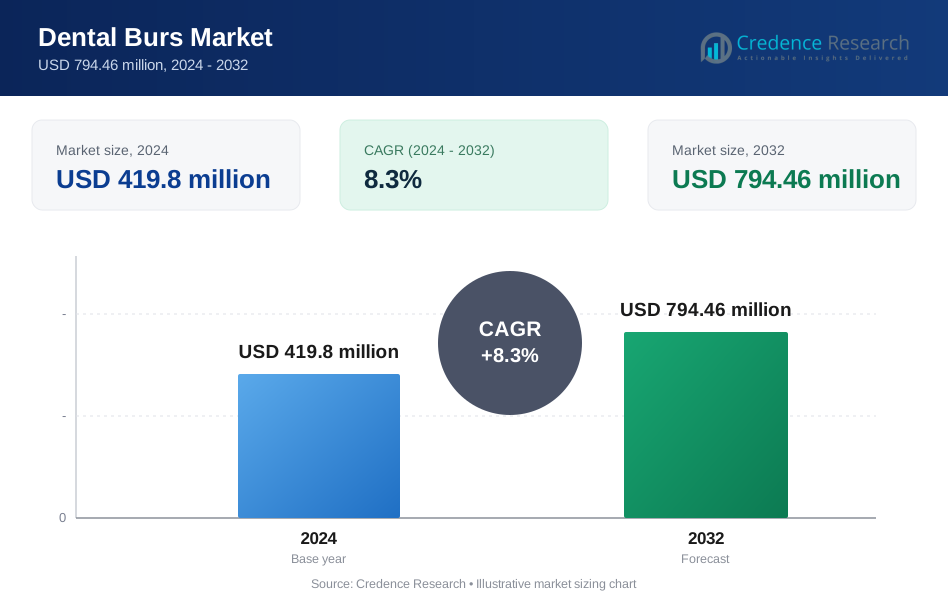
The dental burs market was valued at USD 419.8 million in 2024 and is expected to reach USD 794.46 million by 2032, growing at a CAGR of 8.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Dental Burs Market Size 2024 | USD 419.8 Million |
| Dental Burs Market, CAGR | 8.3% |
| Dental Burs Market Size 2032 | USD 794.46Million |
The dental burs market is led by key companies including Prima Dental, MANI INC, Diatech, COLTENE Inc, Envista, SHOFU INC, Brasseler USA, Dentsply Sirona, Komet Dental, and American Orthodontics. These players maintain strong market positions through advanced product portfolios, global distribution networks, and consistent innovation in diamond and carbide bur technologies. They focus on precision, durability, and compliance with international hygiene standards to meet the growing demand for aesthetic and restorative dental treatments. North America leads the market with a 36% share, supported by established dental infrastructure and high treatment adoption rates, while Asia-Pacific follows with 27%, driven by rapid dental tourism growth and expanding healthcare access.
Market Insights
- The dental burs market was valued at USD 419.8 million in 2024 and is projected to reach USD 794.46 million by 2032, growing at a CAGR of 8.3%.
- Rising prevalence of dental disorders, expanding cosmetic dentistry, and increasing awareness of oral hygiene drive overall market growth across global dental practices.
- Technological advancements in diamond and carbide burs, along with rising adoption of single-use sterilized products, shape current market trends.
- The market is moderately competitive, with key players such as Dentsply Sirona, Prima Dental, and MANI INC focusing on innovation, material durability, and expanding global presence.
- North America leads with 36% share, followed by Europe at 28% and Asia-Pacific at 27%; by material, diamond burs dominate with 43% share, while dental clinics account for 61% of total end-use demand.
Market Segmentation Analysis:
By Material
Diamond burs dominated the dental burs market in 2024 with a 43% share. Their leadership is driven by superior cutting precision, durability, and suitability for polishing hard tissues and enamel. Dentists prefer diamond burs for restorative and cosmetic procedures due to their high efficiency and smooth finishing capability. The rising adoption of advanced dental instruments for aesthetic treatments further supports this segment’s growth. Carbide burs follow closely, favored for their high-speed cutting and longevity in prosthodontic applications, while stainless steel burs maintain steady demand in cost-sensitive markets.
- For instance, Komet Dental manufactures DIAO diamond burs coated with over 200,000 synthetic diamond particles per instrument, ensuring consistent cutting performance and extended operational life. Each bur undergoes laser calibration with a precision tolerance of 0.002 mm, enabling high-speed rotation stability up to 450,000 rpm in turbine handpieces used for aesthetic restorations.
By Application
Oral surgery accounted for the largest 38% share of the dental burs market in 2024. This dominance results from rising demand for tooth extraction, cavity preparation, and crown removal procedures worldwide. Increasing prevalence of dental caries and periodontal diseases drives the use of precision burs in surgical operations. Implantology and orthodontics are growing rapidly as patient preference for cosmetic and corrective dental procedures rises. Manufacturers continue to develop specialized burs for minimally invasive surgeries and complex restorations, enhancing clinical efficiency and safety.
- For instance, Prima Dental’s tungsten carbide surgical burs are CNC-engineered to a concentricity accuracy of 0.003 mm and hardness exceeding 1,600 HV on the Vickers scale. The burs maintain optimal cutting sharpness for more than 20 clinical cycles, allowing precise crown sectioning and bone contouring with minimal heat generation during oral surgeries.
By End Use
Dental clinics held a leading 61% share of the market in 2024. Their dominance stems from a growing number of independent and chain dental practices adopting advanced rotary instruments for routine and cosmetic treatments. Clinics increasingly invest in high-speed handpieces and multi-use diamond burs to improve treatment outcomes and patient comfort. Hospitals represent a steady-growth segment due to their focus on complex oral surgeries and trauma cases. Expanding private dental networks and favorable insurance coverage in developed regions further drive demand from the clinical sector.
Market Overview
Key Growth Drivers
Rising Prevalence of Dental Disorders
The growing incidence of dental caries, periodontal diseases, and tooth decay is a major driver for the dental burs market. Increasing awareness about oral hygiene and the availability of advanced dental care solutions boost the demand for precision dental tools. The rise in dental visits among aging populations and children has accelerated restorative and preventive procedures. As a result, healthcare providers are investing in high-quality burs that ensure accuracy, efficiency, and reduced chair time, supporting consistent market expansion worldwide.
- For instance, MANI, Inc. produces DIA-BURS, which are equipped with diamond particles bonded using a multi-layer electroplating process that enhances cutting performance and durability. Each bur undergoes quality-control testing for precision and to minimize wobbling during restorative treatments.
Growth in Cosmetic and Aesthetic Dentistry
Cosmetic dentistry is expanding rapidly due to rising consumer preference for improved dental aesthetics. Procedures such as veneers, crowns, and teeth reshaping heavily depend on advanced burs for precision and smooth finishing. The growing influence of social media, coupled with increasing disposable income, fuels demand for aesthetic treatments in both developed and emerging economies. Dental professionals are adopting multi-grit diamond and carbide burs to meet patient expectations for high-quality cosmetic outcomes and enhanced procedural safety.
- For instance, SHOFU INC. develops diamond burs using high-precision, computer-automated robotic technology to ensure a uniform distribution of diamond particles. These burs feature a high-grade stainless steel shank for a precise fit and durability.
Technological Advancements in Dental Tools
Ongoing innovations in dental bur materials and designs significantly enhance cutting precision and longevity. Manufacturers are developing multi-layer diamond coatings and hybrid carbide compositions for superior performance and wear resistance. Computer-aided design and 3D manufacturing techniques allow for precise shaping, improving clinical efficiency. These technological upgrades support minimally invasive dental practices, reduce treatment time, and improve patient comfort. Integration of ergonomically designed and sterilizable burs further enhances usability, driving strong adoption across modern dental facilities.
Key Trends and Opportunities
Adoption of Single-Use and Sterile Burs
Rising infection control standards are promoting the use of single-use and pre-sterilized dental burs. Regulatory authorities emphasize cross-contamination prevention in clinical environments, leading to a shift from reusable to disposable tools. Manufacturers are responding with cost-efficient, sterile packaging and environmentally responsible materials. This trend enhances safety, improves workflow efficiency, and reduces sterilization costs for dental clinics. The move toward disposable products also aligns with global healthcare hygiene protocols, creating growth opportunities in developed and emerging markets alike.
- For instance, Dentsply Sirona produces sterile single-use carbide burs under ISO 13485-certified conditions. To ensure sterility and control infection risks, these burs are sold in individually wrapped sterile pouches.
Expansion of Digital and CAD/CAM Dentistry
The integration of digital tools and CAD/CAM systems in dental practices is transforming bur usage. Dentists now use digitally optimized burs for precise milling, crown shaping, and implant preparation. These tools improve treatment accuracy and shorten clinical turnaround times. The rising adoption of chairside milling units and 3D imaging technologies fuels demand for high-speed, compatible burs. Manufacturers that align bur design with digital workflows are well-positioned to benefit from this technological shift.
- For instance, COLTENE Inc. designs CAD/CAM-compatible diamond burs engineered for various materials, including zirconia and ceramics. The company produces different bur kits and individual instruments, some of which are designed for crown and bridge preparation.
Key Challenges
High Cost of Advanced Dental Equipment
The increasing cost of premium dental burs and related high-speed handpieces limits adoption among smaller dental practices. Advanced diamond or carbide burs, while offering superior durability and precision, often require higher investment and maintenance costs. Budget constraints in developing regions restrict access to high-end tools, slowing market penetration. Manufacturers are focusing on affordable alternatives and bulk supply programs to balance pricing and quality, but cost sensitivity remains a persistent challenge for broader adoption.
Limited Reimbursement and Regulatory Barriers
Stringent regulatory approvals and lack of reimbursement for elective dental procedures hinder market growth. Cosmetic and aesthetic treatments, which form a significant share of dental bur usage, are often not covered under insurance plans. Additionally, product approval processes in markets like the EU and U.S. increase compliance costs for manufacturers. These regulatory and financial limitations slow innovation and restrict small manufacturers from entering global markets, constraining the pace of overall industry expansion.
 Regional Analysis
North America
North America held a 36% share of the dental burs market in 2024. The region’s dominance stems from advanced dental infrastructure, high awareness of oral health, and rising cosmetic dentistry demand. The United States leads the market due to extensive insurance coverage and the growing number of dental clinics equipped with modern rotary instruments. Technological advancements and strong adoption of premium diamond and carbide burs enhance procedural efficiency. Continuous product innovation by local manufacturers and favorable reimbursement policies further support market growth across both preventive and restorative dental applications.
Europe
]Europe accounted for 28% of the global dental burs market in 2024. The region benefits from a growing focus on oral healthcare and the expansion of private dental practices. Germany, France, and the United Kingdom are key contributors, driven by high patient expenditure on cosmetic and restorative treatments. Stringent sterilization and hygiene regulations encourage the adoption of single-use burs. The strong presence of established dental product manufacturers and rising geriatric population with oral disorders continue to drive demand, supporting Europe’s position as a major hub for advanced dental care technologies.
Asia-Pacific
Asia-Pacific captured a 27% share of the dental burs market in 2024, emerging as one of the fastest-growing regions. The expansion of dental tourism in India, Thailand, and South Korea supports market growth. Increasing disposable income and government investment in oral health infrastructure promote wider adoption of advanced dental tools. Rapid urbanization and rising awareness about aesthetic dentistry also contribute to demand. Local manufacturing of affordable burs, coupled with growing partnerships with global dental brands, continues to strengthen the region’s position in both domestic and export markets.
Latin America
Latin America accounted for a 5% share of the global dental burs market in 2024. The region’s growth is driven by expanding dental education programs, improved healthcare access, and a rising number of private dental clinics. Brazil and Mexico are key markets due to increasing cosmetic procedures and government initiatives promoting oral health awareness. Imported dental burs dominate the market, as local manufacturing remains limited. Expanding dental tourism and affordable treatment options attract patients from North America and Europe, further boosting regional demand for precision dental instruments.
Middle East & Africa
The Middle East and Africa held a 4% share of the dental burs market in 2024. Market expansion is fueled by rising investments in healthcare infrastructure and growing awareness of dental hygiene. The UAE and Saudi Arabia lead regional demand, supported by the development of modern dental centers and growing adoption of cosmetic treatments. South Africa contributes steadily, driven by increasing access to oral care services. International manufacturers are partnering with local distributors to improve product availability, while government initiatives supporting healthcare modernization further drive gradual market growth.
Market Segmentations:
By Material
- Diamond Burs
- Stainless Steel
- Carbide
By Application
- Oral Surgery
- Implantology
- Orthodontics
- Others
By End Use
- Hospitals
- Dental clinics
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the dental burs market features key players such as Prima Dental, MANI INC, Diatech, COLTENE Inc, Envista, SHOFU INC, Brasseler USA, Dentsply Sirona, Komet Dental, and American Orthodontics. These companies compete through continuous innovation, product diversification, and global distribution networks. Leading manufacturers focus on advanced materials such as diamond and carbide to enhance cutting precision, durability, and performance across clinical applications. Strategic partnerships with dental institutions and distributors help expand their market reach. Many players invest in automated production and digital integration to support consistent quality and cost efficiency. The growing demand for single-use and sterilized burs has led manufacturers to develop eco-friendly and hygienic alternatives, aligning with global safety standards. Companies are also strengthening their presence in emerging markets through product localization and training initiatives for dental professionals.
Key Player Analysis
- Prima Dental
- MANI, INC
- Diatech
- COLTENE Inc
- Envista
- SHOFU INC.
- Brasseler USA
- Dentsply Sirona
- Komet Dental
- American Orthodontics
Recent Developments
- In April 2025, Brasseler USA introduced a dedicated Endodontist Specialty Sales Consultant Team and several new endodontic products.
- In March 2025, Prima Dental introduced advancements in its Prima Classic Carbide Operative Burs range, highlighting brazed carbide necks for optimum strength and concentricity.
- In March 2025, COLTENE Inc launched several innovations at the International Dental Show (IDS) 2025, including the Kenda ShapeGuard polishing system and BRILLIANT Lumina tooth whitening solution.
- In February 2025, Envista Holdings announced a set of dental innovations through its DEXIS brand, including the launch of the DEXIS Ti2 Intraoral Sensor and DEXIS Connect Pro monitoring suite.
Report Coverage
The research report offers an in-depth analysis based on Material, Application, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for dental burs will rise with increasing dental treatments and cosmetic procedures.
- Technological innovations will enhance precision, durability, and efficiency in bur design.
- Adoption of single-use and sterilized burs will expand due to stricter hygiene regulations.
- Growth in dental tourism will boost product demand in emerging markets.
- Manufacturers will focus on sustainable materials and eco-friendly production processes.
- Digital dentistry and CAD/CAM integration will drive demand for specialized burs.
- Expanding private dental clinics will increase global sales volume.
- Strategic collaborations between dental equipment makers and clinics will strengthen market presence.
- Automation in manufacturing will improve cost efficiency and production capacity.
- North America and Asia-Pacific will continue to lead market expansion with strong dental care infrastructure.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Dental Burs market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Dental Burs market projected to grow between 2025 and 2032?
Which Dental Burs market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Dental Burs market?
Who are the leading companies in the Dental Burs market?
Which region commanded the largest share of the Dental Burs market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Dental Burs Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Dental Burs Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 419.8 million → 2032: USD 794.46 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Dental Burs Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Dental Burs Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Dental Burs Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Dental Burs Market Drivers
- 3.3 Dental Burs Market Restraints & Challenges
- 3.4 Dental Burs Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Dental Burs Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Dental Burs Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Dental Burs category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Dental Burs Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Dental Burs Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Dental Burs market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Dental Burs Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Dental Burs Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Dental Burs Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Dental Burs (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Dental Burs Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Dental Burs Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Dental Burs Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Dental Burs Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Dental Burs Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Dental Burs Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Dental Burs Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Dental Burs Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Dental Burs Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
