
Steroid-free creams and pills reshape everyday skin care
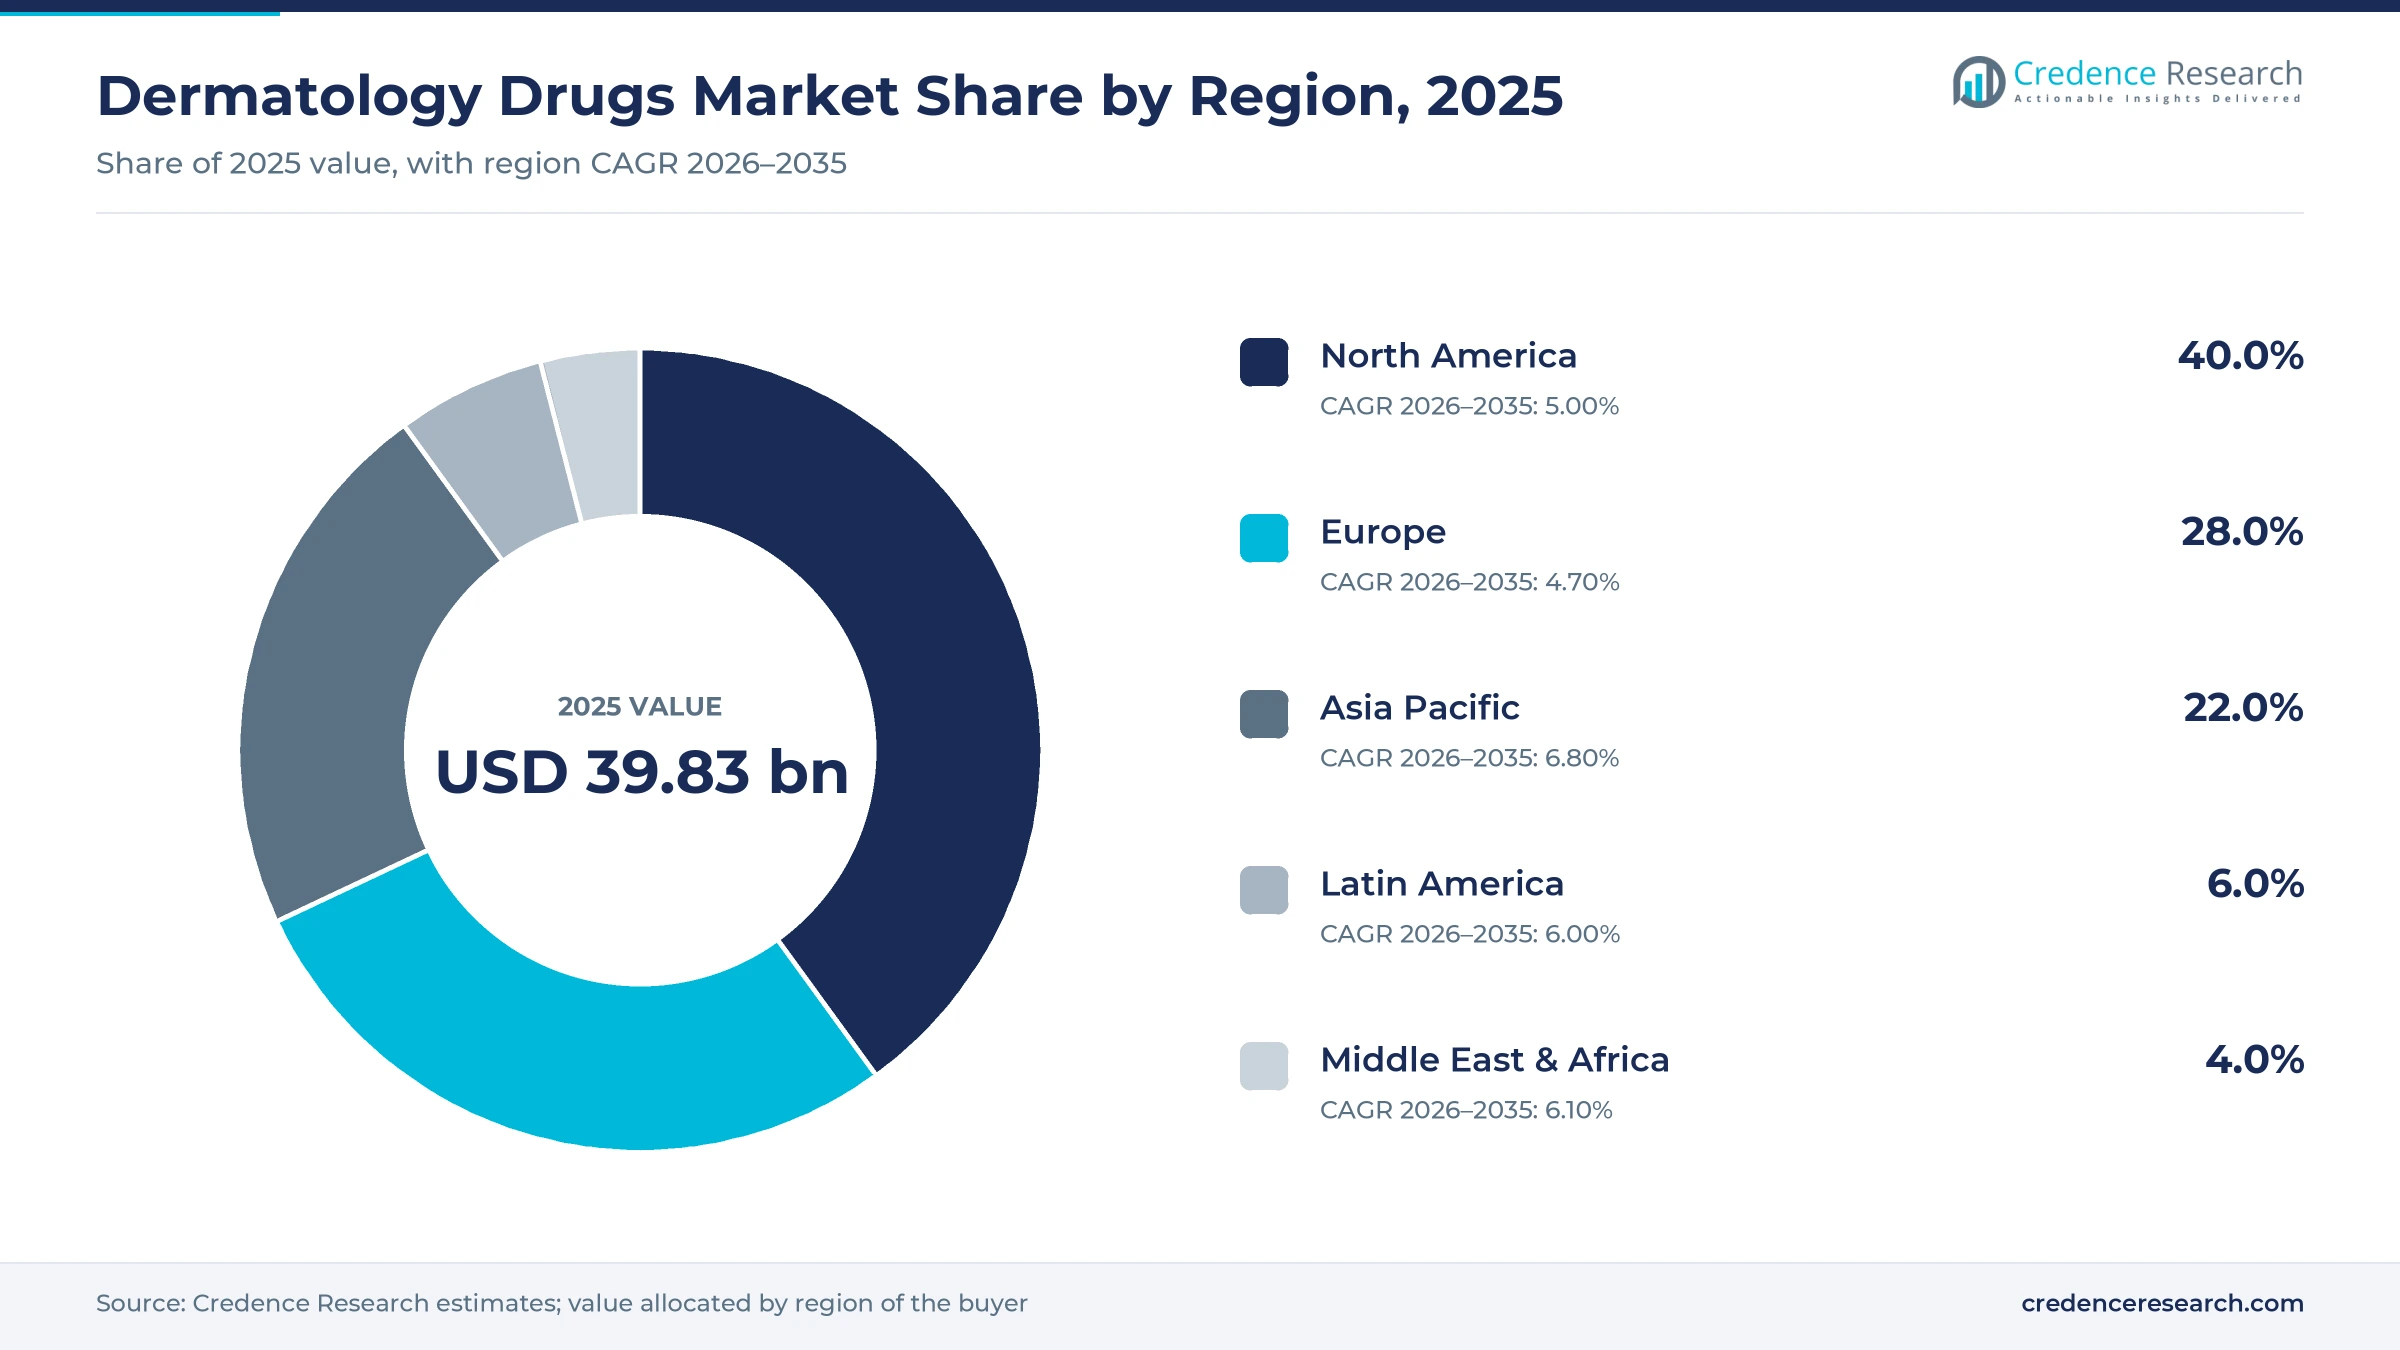
The global dermatology drugs market was valued at USD 39.83 billion in 2025 and is projected to increase from USD 41.99 billion in 2026 to USD 67.65 billion by 2035, registering a CAGR of 5.44% during 2026–2035. Demand comes from acne, eczema and other forms of dermatitis, psoriasis, fungal and bacterial skin infections and skin cancer, conditions treated by dermatologists, primary care doctors and pharmacists in every region. North America held the largest regional share, 40.0% in 2025, on high prescription use, broad insurance coverage and the earliest launches of new topical agents. Asia Pacific is the fastest-growing region at 6.80% a year, as India and China expand dermatology clinics, generic supply and online pharmacy access. The main change is the move from steroid creams toward steroid-free topical agents that block PDE4, the aryl hydrocarbon receptor or JAK enzymes, approved for eczema and hand eczema in 2024 and 2025.
What does the dermatology drugs market cover?
The market counts manufacturer revenue from prescription and over-the-counter medicines used to treat skin disease. It covers topical creams, gels, ointments and foams, oral tablets and capsules, and parenteral products given by injection or infusion, including medicines for skin cancer. Buyers include retail and hospital pharmacies, online pharmacies, dermatology clinics and public and private insurers.
The scope excludes cosmetic skin care without a drug claim, aesthetic toxins and fillers, medical devices such as lasers and phototherapy units, and wound dressings. Sunscreens are counted only where they are regulated and sold as drugs, and dietary supplements for skin are left out of the market value.
Dermatology Drugs Market Insights
- The dermatology drugs market grows from USD 39.83 billion in 2025 to USD 67.65 billion by 2035, a 5.44% CAGR over 2026–2035, as steroid-free topicals and skin cancer therapy add value.
- North America held 40.0% of global dermatology drug value in 2025, backed by high prescription use, insurance coverage and early topical launches.
- Dermatitis led disease areas with 30.0% of 2025 value, because eczema and contact dermatitis need repeated treatment across all ages.
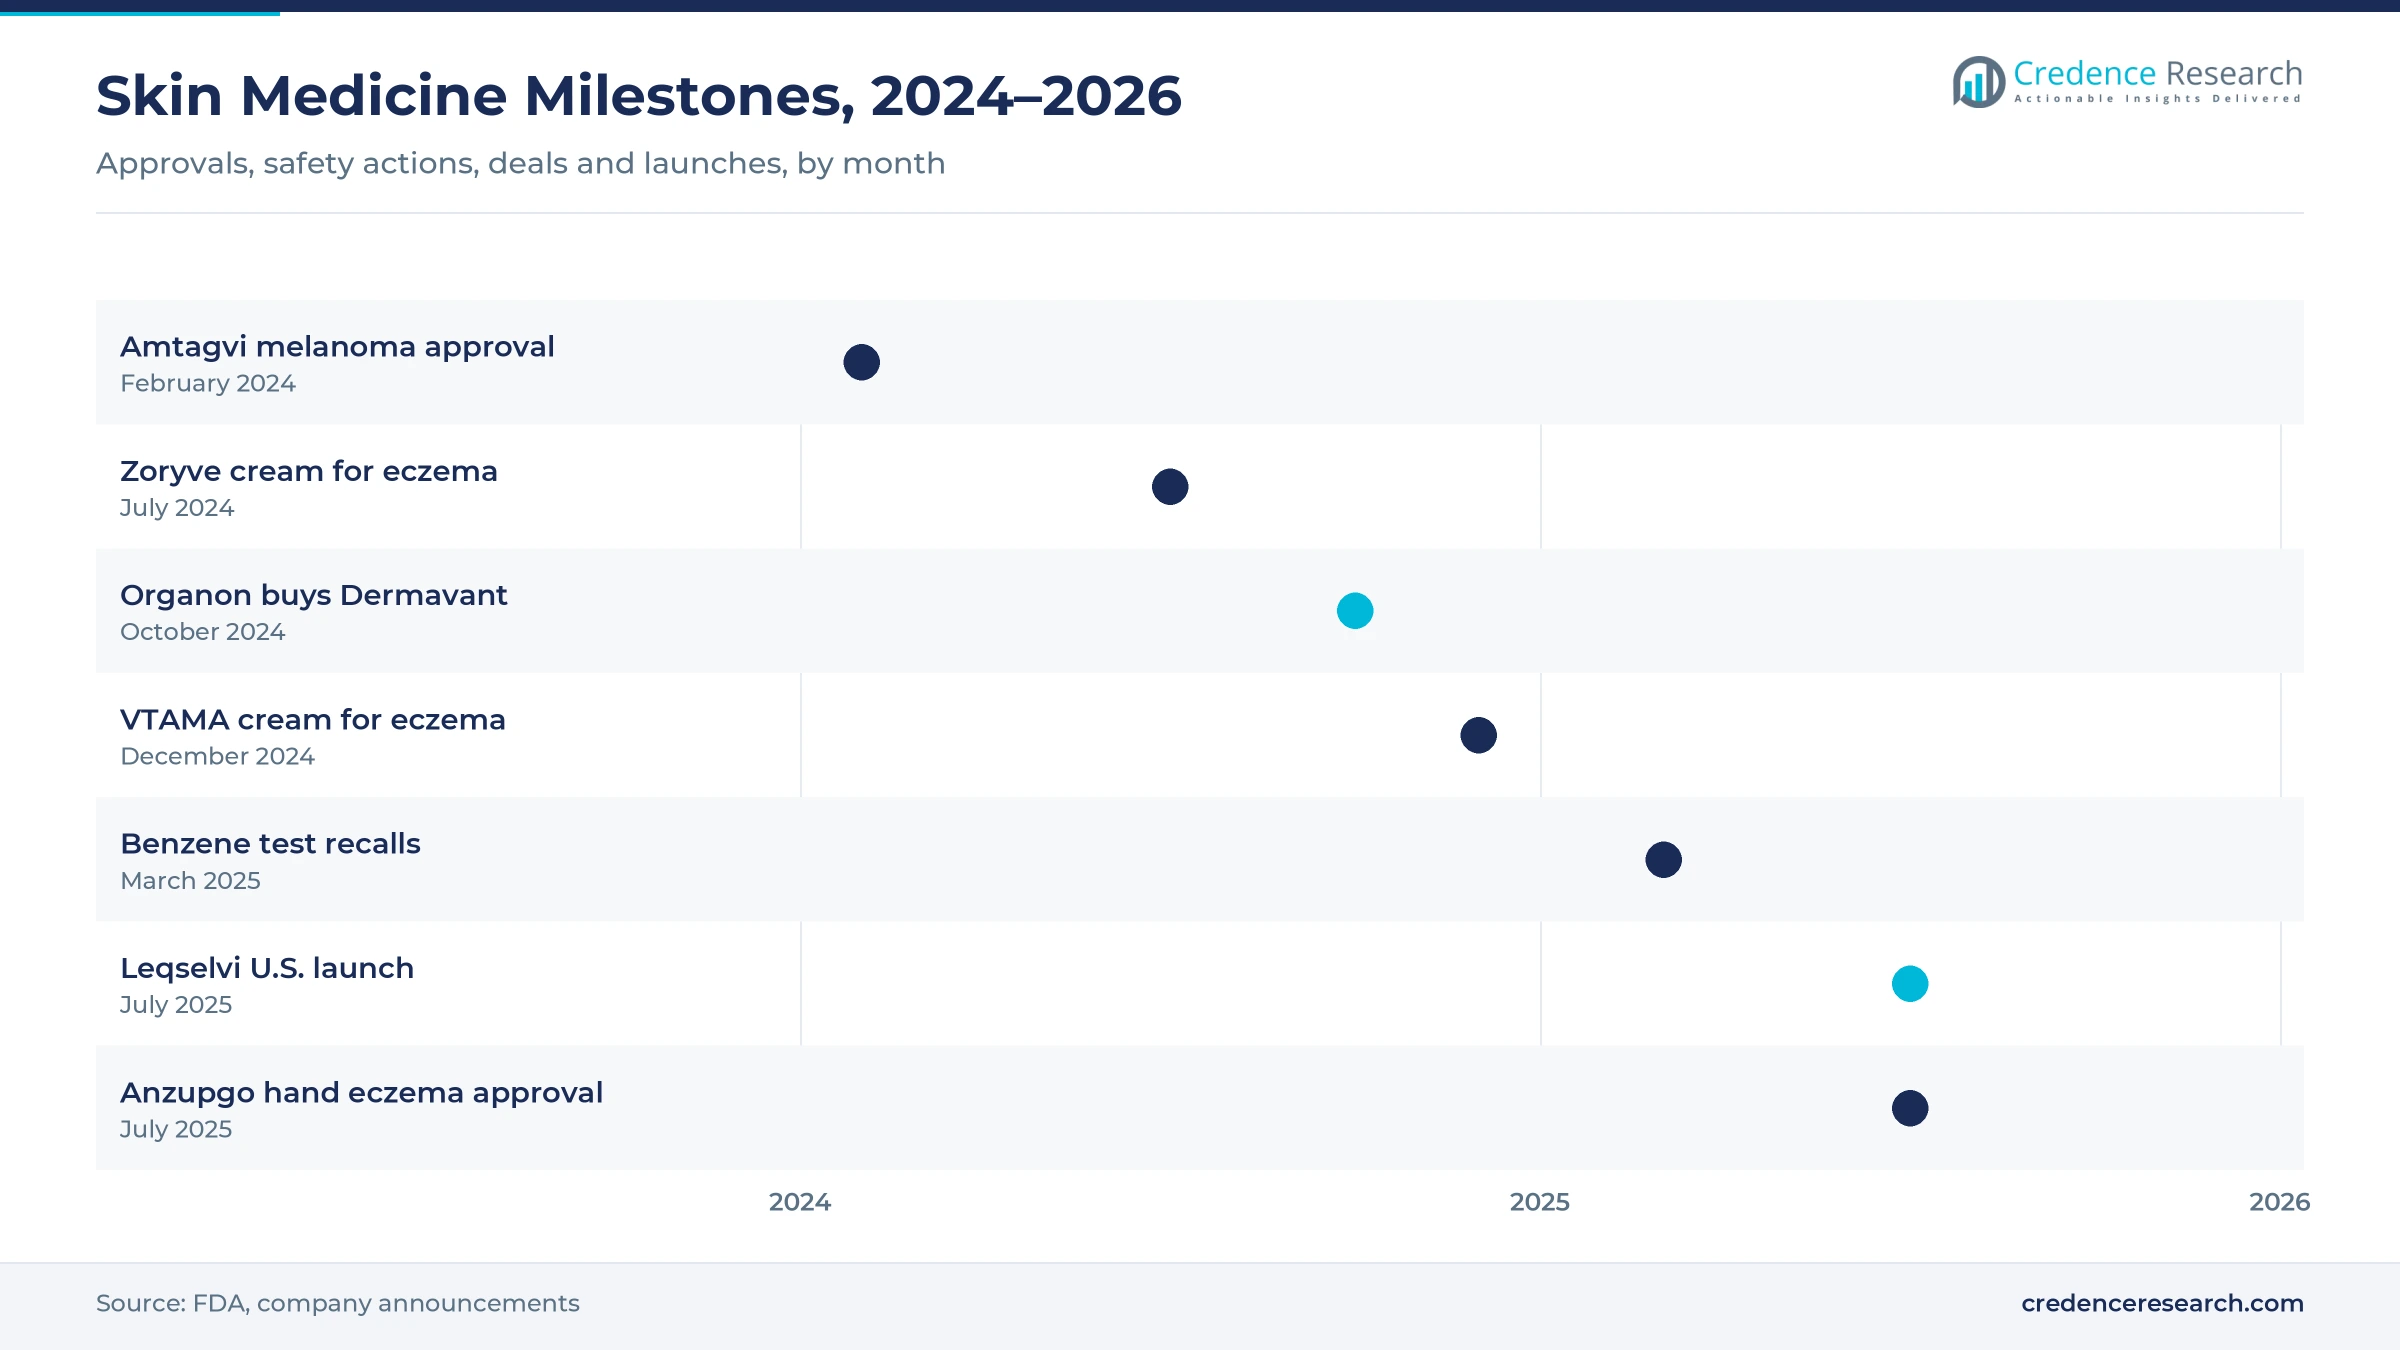
- The FDA approved VTAMA cream for atopic dermatitis in December 2024 and LEO Pharma's Anzupgo for chronic hand eczema in July 2025.
- Organon completed its purchase of Dermavant in October 2024, adding VTAMA and showing how established drugmakers buy into skin care.
Dermatitis and anti-inflammatories lead the skin drug mix
Why does dermatitis hold the largest share?
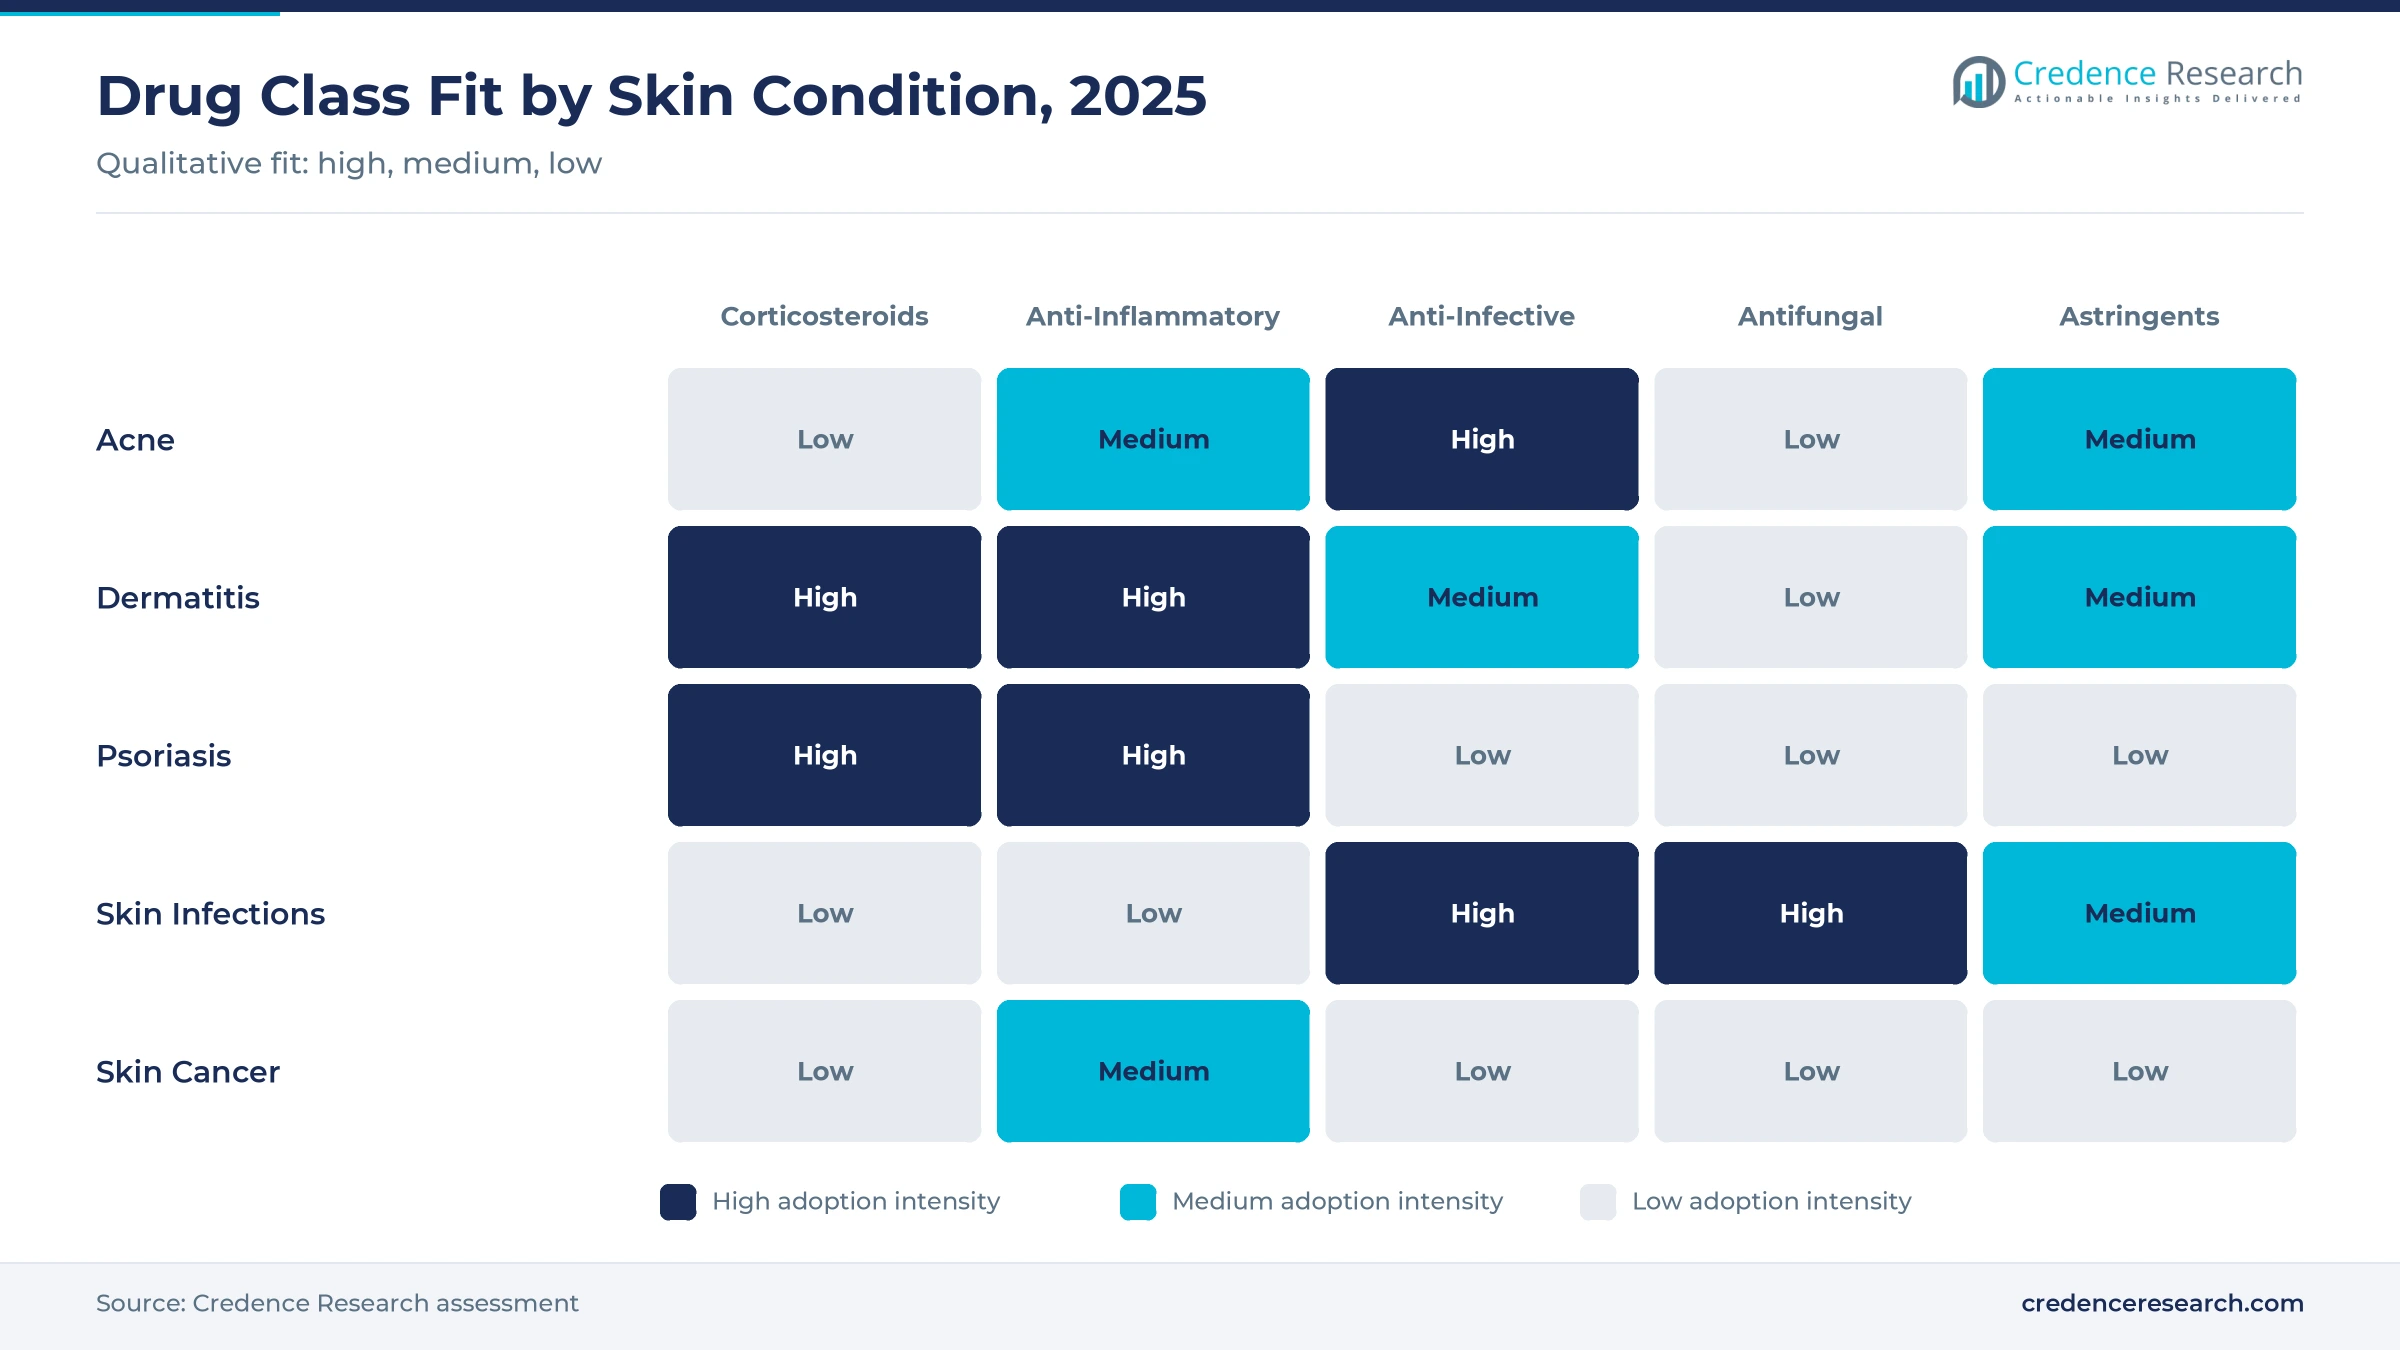
Based on dermatological diseases, the market is categorized into acne, dermatitis, psoriasis, skin cancer and others. Dermatitis led with a 30.0% share of 2025 value, because atopic, contact and hand eczema need long-term creams, pills and rescue steroids. Skin Cancer grows fastest at 6.92% a year, as melanoma cases rise and immunotherapy and cell therapy reach more patients with advanced disease.
Which drug classes lead and which grow fastest?
Based on drug classification, the market is categorized into corticosteroids, astringents, anti-inflammatory and antipruritic drugs, anti-infective and antibacterial drugs, and antifungal drugs. The anti-inflammatory and antipruritic class led with a 34.0% share of 2025 value and also grows fastest at 6.67% a year. This class includes the new PDE4, aryl hydrocarbon receptor and JAK topicals, which take patients from older steroid creams.
How do creams, pills and injections divide value?
Based on route of administration, the market is categorized into topical, oral and parenteral products. Topical products led with a 58.0% share of 2025 value, because most acne, eczema, fungal and mild psoriasis cases are treated with creams, gels and foams. Parenteral products grow fastest at 6.98% a year, as injected antibodies and cell therapy for melanoma raise spending per treated patient.
Where do patients fill skin prescriptions?
Based on distribution channel, the market is categorized into hospital pharmacies, retail pharmacies and online pharmacies. Retail Pharmacies led with a 56.0% share of 2025 value, because acne, eczema and fungal creams are refilled at drugstores, often without a prescription. Online Pharmacies grow fastest at 7.40% a year, as telehealth dermatology and home delivery make repeat prescriptions easier in the U.S., India and China.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Dermatological Diseases | Dermatitis | 30.0% | Skin Cancer | 6.92% |
| By Drug Classification | Anti-Inflammatory & Antipruritic Drugs | 34.0% | Anti-Inflammatory & Antipruritic Drugs | 6.67% |
| By Route of Administration | Topical | 58.0% | Parenteral | 6.98% |
| By Distribution Channel | Retail Pharmacies | 56.0% | Online Pharmacies | 7.40% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Common skin disease, new topicals and rising cancer cases
How does common skin disease sustain repeat demand?
Skin disease is among the most frequent reasons people see a doctor or buy medicine from a pharmacist, which keeps volume high. Acne affects most teenagers at some stage, while eczema, contact dermatitis and fungal infections recur across adult life. Because many of these conditions return after treatment stops, patients refill creams, gels and tablets several times a year. As a result, steady prevalence translates into recurring demand for acne treatment, antifungal creams and steroid ointments in every region.
Why do steroid-free topicals raise value per patient?
Long-term use of topical steroids can thin the skin, so doctors and parents look for steroid-free options for daily use. In December 2024, the FDA approved VTAMA (tapinarof) cream 1% for atopic dermatitis in adults and children two years of age and older, ahead of its March 2025 target date. Arcutis had gained U.S. approval for Zoryve cream 0.15%, a PDE4 inhibitor, for patients 6 and older in July 2024. These branded creams cost more than generic steroids, which lifts spending per eczema patient.
How are new indications opening untreated groups?
Regulators are approving drugs for skin conditions that previously had no specific treatment, which brings new patients into care. On July 23, 2025, LEO Pharma announced FDA approval of Anzupgo (delgocitinib) cream, the first treatment specifically approved for moderate to severe chronic hand eczema in adults. The steroid-free cream blocks four enzymes, JAK1, JAK2, JAK3 and TYK2, in the skin. In July 2025, Sun Pharma launched Leqselvi, an oral JAK inhibitor for severe alopecia areata, in the U.S. Each new label adds a premium prescription line.
Why does rising skin cancer add parenteral value?
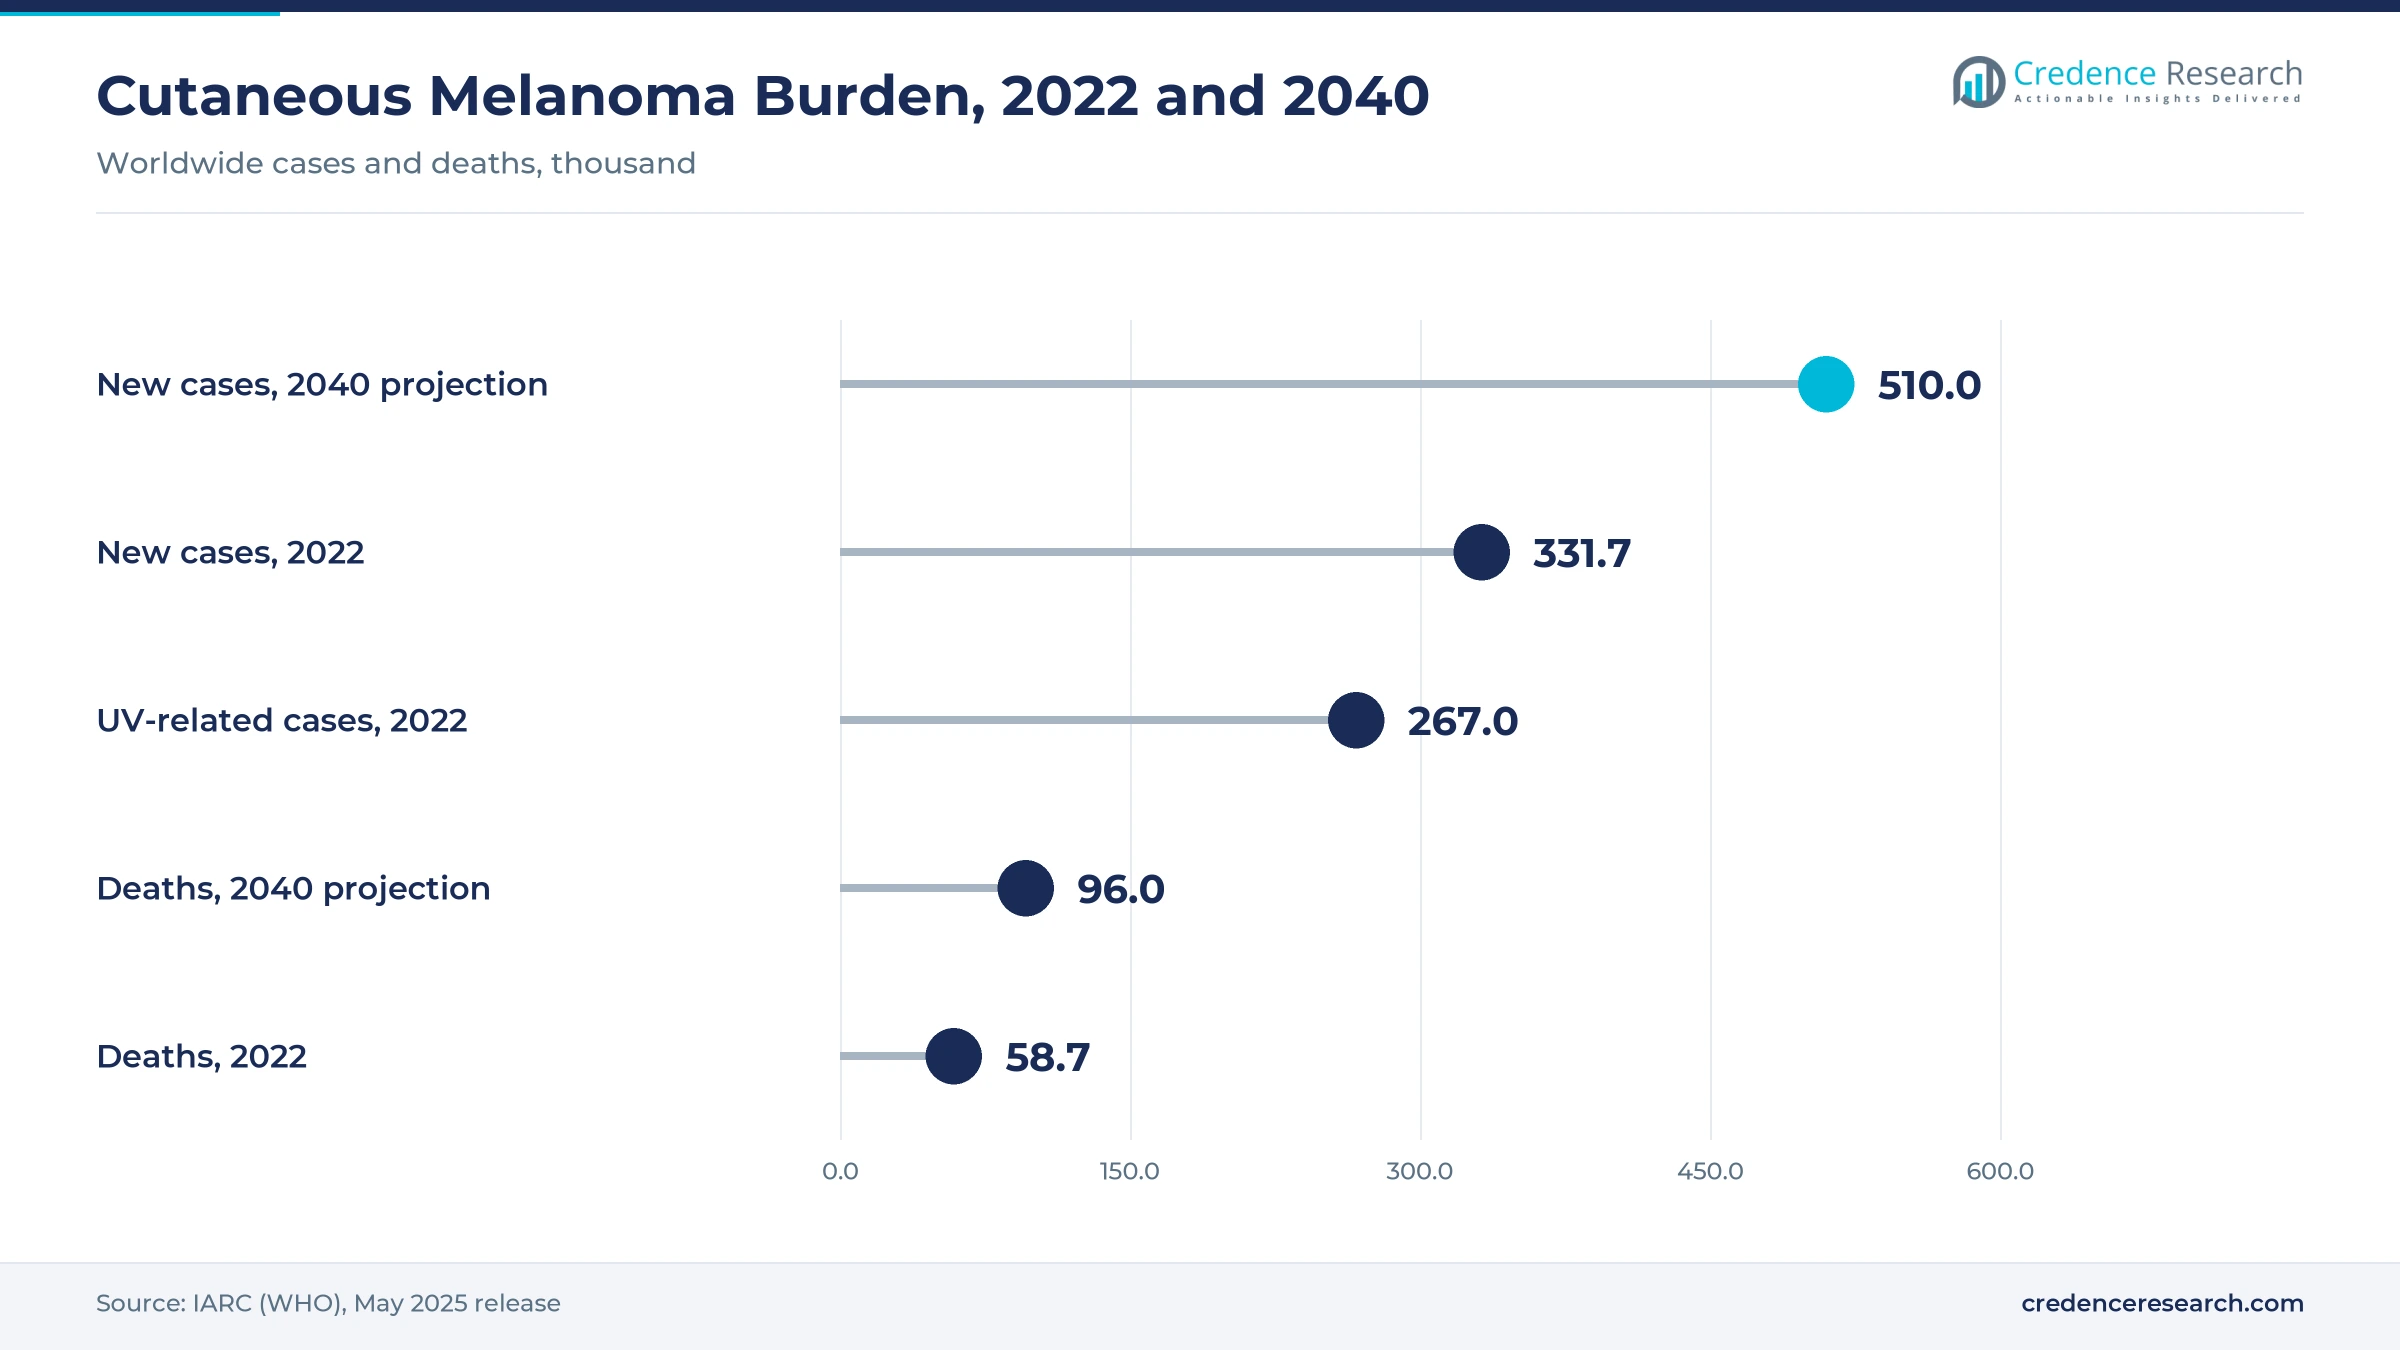
Melanoma cases continue to grow as populations age and lifetime sun exposure accumulates, which raises demand for cancer medicines given by infusion. The IARC estimates 331,700 new cutaneous melanoma cases and 58,700 deaths worldwide in 2022, and it projects more than 510,000 cases and 96,000 deaths in 2040. In February 2024, the FDA granted accelerated approval to Iovance's Amtagvi, the first T cell therapy from a patient's own tumor for advanced melanoma. This shift makes skin cancer the fastest-growing disease segment through 2035.
Non-steroidal creams, oral JAK pills and cell therapy
Why are non-steroidal creams gaining ground?
Dermatologists are shifting long-term eczema and psoriasis care from steroid creams to non-steroidal topicals that patients can use for longer periods. VTAMA works as an aryl hydrocarbon receptor agonist, Zoryve as a PDE4 inhibitor and Anzupgo as a topical pan-JAK inhibitor. These 3 creams, approved for eczema or hand eczema in 2024 and 2025, target inflammation without the skin thinning linked to steroids, which suits children and sensitive areas such as the face. As payers add them to formularies, the anti-inflammatory class takes share from corticosteroids.
How are pills and antibodies changing moderate disease?
Patients with moderate to severe skin disease are moving from creams alone to oral tablets and injected therapy, which raises spending per case. Oral JAK inhibitors now treat alopecia areata, while injectable antibodies for eczema and psoriasis serve patients who fail topical care. Telehealth visits make follow-up easier for patients on systemic therapy. This rise in systemic treatment lifts the oral and parenteral routes faster than topical products through 2035.
Where is the opening in skin cancer?
Skin cancer offers a clear opening, because advanced melanoma and keratinocyte cancers still have patients who fail first-line therapy. Cell therapy, checkpoint inhibitors and topical field treatments for precancerous lesions widen the options at each stage. Care for non-melanoma skin cancer also includes creams and photodynamic therapy for actinic keratosis. Companies that link early detection with treatment can capture a growing pool of patients as older populations expand in Europe, North America and Australia.
Can online pharmacies and Asia widen access?
Online pharmacies and fast-growing markets in Asia offer an opening for both branded and generic suppliers of skin medicines. In India, Cipla, Glenmark and Sun Pharma supply low-cost acne, antifungal and steroid creams through large pharmacy networks and e-pharmacies. Rising incomes and more dermatology clinics bring untreated patients into care across India, China and Southeast Asia. As a result, Asia Pacific offers volume growth even where prices stay low, especially for combination creams and branded generics.
Benzene recalls, resistant fungi and generic price cuts
What did benzene testing mean for acne products?
Product quality became a concern after independent tests found benzene in some acne products containing benzoyl peroxide. On March 11, 2025, the FDA reported that it tested 95 benzoyl peroxide acne products and found elevated benzene in six, leading to retail-level recalls. The agency advised consumers to discard products past their expiration date. This episode pushes makers to tighten stability testing and packaging, which raises costs for OTC acne brands and slows growth in the segment.
Why do resistant fungi complicate treatment?
Antifungal resistance is reducing the reliability of standard treatment for ringworm and related skin infections. The CDC reported the first U.S. cases of tinea caused by Trichophyton indotineae in May 2023, in two New York City women aged 28 and 47 whose rash did not improve on oral terbinafine. The report notes an epidemic of severe, antifungal-resistant tinea in South Asia. One rash cleared only after a 4-week itraconazole course, so longer courses raise costs, while over-the-counter antifungal creams may fail.
How does generic competition hold down prices?
Most corticosteroids, antibiotics, antifungals and retinoids used on the skin lost patent protection years ago and now sell as low-cost generics. Indian and other generic makers compete hard on price in the U.S., Europe and emerging markets, so revenue per tube keeps falling even as units grow. Branded makers must invest in new formulations to defend share. This price pressure is the main reason corticosteroids and astringents grow more slowly than the overall market.
Why do payer rules slow new topical uptake?
Branded non-steroidal creams and oral JAK pills cost far more than generic steroids, and insurers often require patients to try cheaper options first. Step therapy and prior authorization delay access for eczema, psoriasis and alopecia patients who could benefit from newer products. Public payers in Europe, Latin America and Asia may limit coverage to severe cases. These hurdles slow the pace at which new therapies replace older treatment, especially outside the U.S.
North America leads while Asia Pacific grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 15.93 | 40.0% | 5.00% |
| Europe | 11.15 | 28.0% | 4.70% |
| Asia Pacific | 8.76 | 22.0% | 6.80% |
| Latin America | 2.39 | 6.0% | 6.00% |
| Middle East & Africa | 1.59 | 4.0% | 6.10% |
North America leads on branded topicals
North America held a 40.0% share of 2025 value and grows at 5.00% a year through 2035. The U.S. leads spending, because new topicals such as VTAMA, Zoryve and Anzupgo, and new cancer therapy such as Amtagvi, reached U.S. patients first. Broad OTC access to acne, antifungal and hydrocortisone products adds steady volume at drugstores. However, generic competition, store brands and payer step therapy hold down value growth in older classes.
Europe balances specialists and generics
Europe held a 28.0% share of 2025 value and grows at 4.70% a year, the slowest pace among the five regions. Germany, France, Italy, Spain and the U.K. account for most regional demand, with LEO Pharma, Almirall and Galderma based in the region. Almirall reported that its eczema antibody Ebglyss reached 16 countries and more than 9,000 patients during 2025. However, reference pricing and generic substitution keep prices low for older creams.
Asia Pacific grows on access and generics
Asia Pacific held a 22.0% share of 2025 value and is the fastest-growing region at 6.80% a year. India is a major producer and user of dermatology generics, with Sun Pharma, Cipla and Glenmark supplying acne, antifungal and steroid products. China, Japan and Australia add demand for prescription eczema and psoriasis therapy and for skin cancer care. As dermatology clinics and online pharmacies expand, more patients receive treatment for chronic skin conditions.
Latin America relies on pharmacy access
Latin America held a 6.0% share of 2025 value and grows at 6.00% a year through 2035. Brazil and Mexico account for most demand, with pharmacies selling many antifungal, acne and steroid creams directly to patients. Currency swings and public budget limits slow the uptake of new branded topicals and systemic therapy.
Middle East and Africa start from a low base
The Middle East & Africa held a 4.0% share of 2025 value and grows at 6.10% a year. Gulf states such as Saudi Arabia and the United Arab Emirates lead regional spending, with growing private insurance and dermatology clinics. In much of Africa, access remains limited to basic antifungal, antibiotic and steroid creams.
Topical approvals and dermatology deals since 2024
| Development | Status and market relevance |
|---|---|
| In July 2024, Arcutis announced FDA approval of Zoryve (roflumilast) cream 0.15% for mild to moderate atopic dermatitis in patients 6 and older. | Approved. Adds a once-daily PDE4 cream for eczema. |
| In December 2024, Organon announced FDA approval of VTAMA cream 1% for atopic dermatitis in adults and children 2 and older. | Approved. Extends the aryl hydrocarbon receptor cream from psoriasis to eczema. |
| In March 2025, the FDA reported benzene test results for 95 benzoyl peroxide acne products, and retail-level recalls followed for six of them. | In force. Tightens quality scrutiny of OTC acne products. |
| In July 2025, Sun Pharma launched Leqselvi (deuruxolitinib), an oral JAK inhibitor for severe alopecia areata, in the U.S. | Launched. Adds an oral option for adults with severe hair loss. |
| In July 2025, LEO Pharma announced FDA approval of Anzupgo (delgocitinib) cream for moderate to severe chronic hand eczema in adults. | Approved. The first U.S. treatment specifically for chronic hand eczema. |
PDE4, AhR and JAK targets move into creams
- PDE4 inhibitor creams such as roflumilast calm skin inflammation without steroids and suit daily use on the face and in skin folds.
- Aryl hydrocarbon receptor agonists such as tapinarof switch on a skin pathway that reduces inflammation and supports the skin barrier.
- Topical JAK inhibitors such as delgocitinib block several JAK enzymes in the skin and treat hand eczema with little systemic exposure.
- Oral JAK pills such as deuruxolitinib treat severe alopecia areata and give patients a systemic option without an injection.
- Tumor-derived T cell therapy such as lifileucel expands a patient's own immune cells to attack advanced melanoma after other treatment fails.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Specialists and generic makers split the skin portfolio
Competition in skin medicines splits into three groups with different economics. Specialist dermatology companies such as Galderma, LEO Pharma and Almirall build portfolios around prescription creams, antibodies and medical skin care, and Galderma listed on the SIX Swiss Exchange in March 2024. Large drugmakers such as AbbVie, Pfizer and Novartis compete with systemic immunology products for psoriasis, eczema, alopecia and hives. Indian companies, including Sun Pharma, Cipla, Glenmark and Glamris Dermacare, supply generic and branded generic creams, gels and tablets across India and export markets, and Sun Pharma added Leqselvi in the U.S. in 2025. Organon entered the field by completing its purchase of Dermavant in October 2024. Because new steroid-free topicals carry higher prices, share in value shifts toward companies with novel targets, while generic makers keep most of the volume.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Galderma | Dermatology specialist | Prescription topicals, Nemluvio and medical skin care |
| AbbVie | Immunology | Systemic immunology therapy for skin disease |
| Pfizer | Diversified pharma | Inflammation and immunology portfolio |
| Novartis | Immunology | Rhapsido oral BTK inhibitor for chronic hives |
| Sun Pharma | Specialty and generics | Leqselvi oral JAK inhibitor and generic skin products |
| Cipla | Generics | Generic acne, antifungal and steroid products |
| Glenmark | Generics and specialty | Generic and branded generic dermatology products |
| Glamris Dermacare | Dermatology supplier | Dermatology formulations in India |
| LEO Pharma | Dermatology specialist | Anzupgo delgocitinib cream for chronic hand eczema |
| Almirall, S.A. | Dermatology specialist | Ebglyss in Europe and medical dermatology portfolio |
Novel topicals carry value while generics carry volume
Credence Research's view is that steroid-free topicals, oral targeted pills and skin cancer therapy will carry most of the value growth in skin medicines through 2035. Generic steroids, antibiotics and antifungals still supply the volume base, but price erosion keeps their value growth below the market average. Branded creams for eczema and hand eczema raise spending per patient where payers cover them. Companies that combine dermatologist relationships with new targets, and generic makers with wide pharmacy reach in Asia, are both well placed, although they win on different measures.
How the 2025 baseline and forecast were built
The report uses 2025 as the base year and forecasts market value to 2035, with growth rates stated for 2026–2035. Market values come from the Credence Research market model, which combines treated patient numbers by skin condition, typical therapy use and average selling prices by region and channel. Splits by disease, drug classification, route of administration, distribution channel and region are Credence Research estimates. Sources used include FDA approvals and safety notices, CDC and IARC disease data, and company press releases and filings. No primary interviews or surveys were used to build the estimates in this report.
Prescription innovation outpaces OTC creams by 2035
By 2035, the market reaches USD 67.65 billion, with prescription products growing faster than OTC creams. Dermatitis remains the largest disease area as steroid-free topicals and oral pills widen long-term care for eczema and hand eczema. Skin cancer gains share as melanoma cases rise and cell therapy and immunotherapy reach more patients. Online pharmacies take a larger part of repeat acne and eczema prescriptions. Generic steroids and antifungals keep volumes high in Asia Pacific and Latin America at low prices, while resistant fungal infections push demand toward newer agents.
Frequently Asked Questions
How big is the dermatology drugs market?
Which disease area leads the market?
Which disease area grows fastest?
Which region holds the largest share?
What new topical treatments have been approved?
How common is melanoma worldwide?
Who are the leading companies?
What are the main challenges?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Dermatological Diseases
- 1.2.1 Dermatitis
- 1.2.2 Acne
- 1.2.3 Psoriasis
- 1.2.4 Skin Cancer
- 1.2.5 Others
- 1.3 By Drug Classification
- 1.3.1 Anti-Inflammatory & Antipruritic Drugs
- 1.3.2 Corticosteroids
- 1.3.3 Anti-Infective/Antibacterial Drugs
- 1.3.4 Antifungal Drugs
- 1.3.5 Astringents
- 1.4 By Route of Administration
- 1.4.1 Topical
- 1.4.2 Oral
- 1.4.3 Parenteral
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 39.83 billion → 2035: USD 67.65 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dermatology Drugs Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dermatology Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dermatology Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dermatology Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dermatology Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dermatology Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dermatology Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dermatology Drugs Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 39.83 billion → 2035: USD 67.65 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dermatology Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Dermatological Diseases - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Dermatitis
- 12.3.7.2 Acne
- 12.3.7.3 Psoriasis
- 12.3.7.4 Skin Cancer
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Drug Classification - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Anti-Inflammatory & Antipruritic Drugs
- 12.4.7.2 Corticosteroids
- 12.4.7.3 Anti-Infective/Antibacterial Drugs
- 12.4.7.4 Antifungal Drugs
- 12.4.7.5 Astringents
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Route of Administration - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Topical
- 12.5.7.2 Oral
- 12.5.7.3 Parenteral
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dermatology Drugs Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2035
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Dermatology Drugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Dermatology Drugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Galderma
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 AbbVie
- 17.4 Pfizer
- 17.5 Novartis
- 17.6 Sun Pharma
- 17.7 Cipla
- 17.8 Glenmark
- 17.9 Glamris Dermacare
- 17.10 LEO Pharma
- 17.11 Almirall, S.A.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

