
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
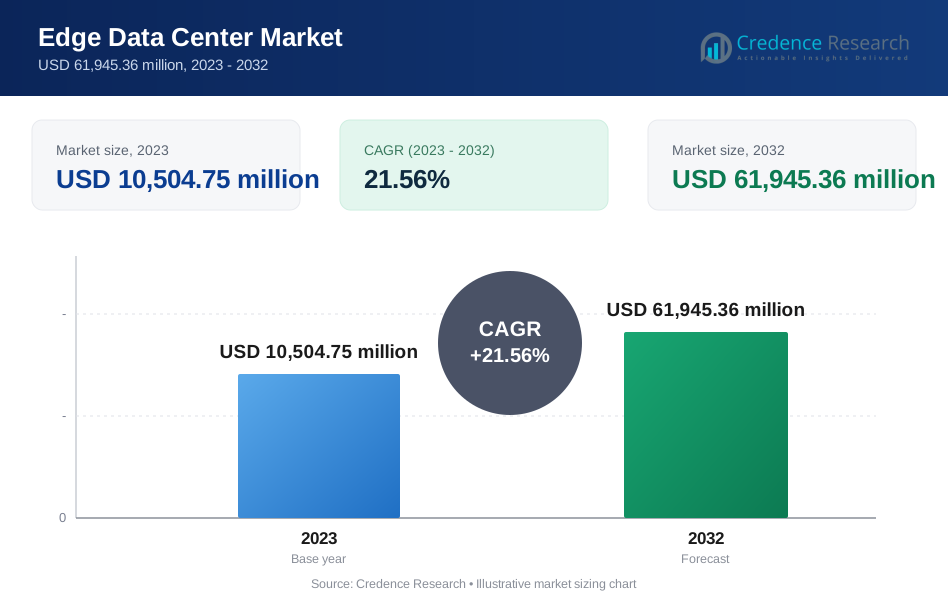
| Edge Data Center Market Size 2023 | USD 10,504.75 Million |
| Edge Data Center Market, CAGR | 21.56% |
| Edge Data Center Market Size 2032 | USD 61,945.36 Million |
Market Overview
The Edge Data Center Market is projected to grow from USD 10,504.75 million in 2023 to an estimated USD 61,945.36 million by 2032, registering a compound annual growth rate (CAGR) of 21.56% from 2024 to 2032. The market is witnessing robust growth driven by increasing demand for low-latency computing and data storage close to end-users, supporting advancements in technologies such as IoT, 5G, and AI.
The primary drivers of the edge data center market include the growing adoption of cloud services, the proliferation of smart devices, and the rise in data traffic. Trends such as the shift towards decentralization of data centers and advancements in AI-powered analytics are further fueling market growth. Businesses are increasingly focusing on edge computing to reduce latency and enhance real-time data processing capabilities.
Geographically, North America dominates the edge data center market due to early adoption of advanced technologies and strong infrastructure, followed by Europe and Asia Pacific. The Asia Pacific region is expected to witness the highest growth due to the increasing digitization and industrialization in countries like China and India. Key players in the market include EdgeConneX, Equinix, Inc., Vapor IO, Inc., Digital Realty, and Schneider Electric, driving innovation and expansion in this sector.
Market Drivers
Growing Demand for Low-Latency Computing and Real-Time Data Processing
As the number of connected devices continues to surge globally, the demand for faster and more efficient data processing is becoming increasingly critical. Edge data centers play a vital role in reducing latency by positioning data storage and computing power closer to end-users, allowing real-time data processing. This capability is essential for technologies such as the Internet of Things (IoT), autonomous vehicles, and augmented reality (AR), where milliseconds can make a significant difference. In traditional cloud computing environments, data often needs to travel to distant data centers, causing delays. Edge computing reduces this distance, thereby decreasing the time it takes for data to be processed and sent back. This low-latency environment is particularly critical in industries like healthcare, manufacturing, and telecommunications, where real-time decision-making is required. As a result, the increasing need for low-latency solutions is driving significant investment in edge data center infrastructure worldwide.
Expansion of IoT Devices and Smart Applications The rapid proliferation of IoT devices across various industries is one of the primary drivers for the growth of edge data centers. IoT devices generate massive amounts of data that need to be processed and analyzed quickly. From smart cities to industrial automation, IoT devices are being integrated into everyday processes, enabling efficient operations, predictive maintenance, and seamless connectivity. Traditional cloud data centers often struggle to handle this vast influx of data in real time, particularly when bandwidth limitations and latency issues arise. Edge data centers solve these challenges by processing data closer to the source, thereby reducing the load on central data centers and ensuring faster data insights. As industries like agriculture, energy, transportation, and retail increasingly adopt IoT technologies, the need for edge data centers is expected to grow exponentially. Additionally, the rise of smart applications, including smart homes, smart factories, and connected healthcare, further boosts the demand for localized data processing at the edge, creating a favorable environment for the expansion of edge data centers.
Increasing Adoption of 5G Networks The global rollout of 5G networks is a significant factor propelling the growth of the edge data center market. With 5G offering faster data transfer rates, lower latency, and higher network reliability, it is a key enabler of edge computing. 5G technology enhances the ability of edge data centers to deliver real-time processing and efficient data transmission. As businesses and consumers alike demand faster connectivity for applications such as autonomous vehicles, virtual reality (VR), and immersive gaming, edge data centers are positioned as critical infrastructure in the 5G ecosystem. The combination of 5G and edge computing reduces the reliance on centralized cloud data centers and enables ultra-fast data processing for applications requiring immediate responses. Furthermore, industries such as telecommunications, media and entertainment, and transportation are heavily investing in edge infrastructure to capitalize on the capabilities of 5G, driving the need for robust edge data center deployments. As 5G technology continues to expand across the globe, the synergy between 5G networks and edge data centers will play a pivotal role in driving the market’s growth. For instance, global 5G connections surged to 1.76 billion in 2023, adding 700 million connections in that year alone.
Shift Toward Decentralization and Edge-First Strategies As businesses move away from centralized data processing models, there is an increasing focus on decentralizing their IT infrastructure to meet the demands of distributed computing. Edge data centers enable this shift by supporting edge-first strategies, where data is processed closer to the source rather than relying solely on central cloud environments. This decentralized approach is particularly advantageous for industries that require real-time data analytics, low-latency responses, and improved operational efficiency. In sectors such as manufacturing, where smart factories use automation, sensors, and machine learning for predictive maintenance, edge computing ensures that data is processed at the source, allowing for real-time decision-making. Similarly, in the healthcare sector, edge data centers allow for faster processing of patient data, enabling immediate responses and improving patient care outcomes. The decentralization trend is also gaining momentum in the retail sector, where edge data centers provide localized processing for tasks like inventory management and personalized customer experiences. As more organizations embrace edge-first strategies to stay competitive and meet customer demands, the edge data center market is poised for rapid growth.
Market Trends
Increased Focus on Sustainable and Energy-Efficient Edge Data Centers One of the most notable trends in the global edge data center market is the growing emphasis on sustainability and energy efficiency. As data centers continue to expand globally, concerns over their environmental impact are increasing. Edge data centers, in particular, are becoming a focal point for companies seeking to reduce their carbon footprint. Many enterprises and data center operators are now prioritizing the use of renewable energy sources, such as solar and wind power, to reduce dependency on traditional energy grids. For instance, data centers have been integrating renewable energy sources and advanced cooling technologies to improve energy efficiency and reduce power consumption. Additionally, innovations in cooling technologies, such as liquid cooling systems and advanced airflow management, are being integrated to improve energy efficiency and reduce power consumption. The shift towards green data centers aligns with broader industry goals to meet global sustainability targets, which is becoming a key competitive advantage for businesses. Governments are also supporting this trend through regulations and incentives, driving further investment in energy-efficient edge data centers.
Growth of Edge Data Centers in Emerging Markets As industries in emerging markets like Asia-Pacific, Latin America, and Africa experience rapid digital transformation, there is a significant surge in the demand for localized data processing solutions. Edge data centers are becoming critical infrastructure in these regions due to the need for low-latency services and the rise of technologies such as IoT, AI, and 5G. In these emerging markets, traditional centralized cloud solutions often face challenges like bandwidth limitations and latency issues due to geographical distances from core data centers. Edge data centers address these concerns by enabling data processing closer to end-users, reducing delays and enhancing service quality. For instance, countries such as India, China, and Brazil are witnessing rapid expansion in the deployment of edge data centers, driven by increased internet penetration, mobile device usage, and the adoption of cloud-based services. Additionally, the growing demand for localized content, such as video streaming and online gaming, further contributes to the rise of edge data centers in these regions, shaping the global landscape of the market.
Market Restraints and Challenges
High Infrastructure and Maintenance Costs One of the major restraints in the global edge data center market is the high capital expenditure required for infrastructure deployment and ongoing maintenance. Unlike traditional centralized data centers, which benefit from economies of scale, edge data centers are smaller and need to be distributed across multiple locations, leading to increased costs for construction, hardware, and operational expenses. The need for specialized equipment, cooling solutions, and energy-efficient technologies further adds to the financial burden. For instance, the cumulative capital expenditures for new and replacement IT server equipment and edge computing facilities are estimated to reach significant amounts over the next decade. Additionally, managing multiple distributed data centers requires more resources for monitoring, maintenance, and upgrades, making operational efficiency a challenge. These financial hurdles can deter smaller enterprises and businesses with limited budgets from investing in edge computing solutions, thus slowing the market’s potential growth. Moreover, as the market continues to expand, ensuring the economic scalability of edge data centers remains a significant challenge for operators.
Security and Data Privacy Concerns Another critical challenge facing the edge data center market is ensuring robust security and data privacy measures. With the increased distribution of data across numerous edge locations, the risk of cyberattacks and data breaches also rises. Unlike centralized data centers, where security protocols are often more uniform and tightly controlled, edge data centers present a decentralized model that is more vulnerable to threats. Securing multiple small facilities, each with its own local network, increases the complexity of safeguarding sensitive information. For instance, edge data centers are prone to attacks due to their dispersed locations and lack of stringent measures for preventing intrusion. Additionally, as data privacy regulations become more stringent across different regions, ensuring compliance at the edge can be difficult, especially when data is processed in multiple jurisdictions with varying laws. Failure to adequately address these security and compliance concerns can lead to reputational damage, regulatory fines, and loss of consumer trust, posing a significant barrier to the wider adoption of edge data centers.
Market Segmentation Analysis
By Component
The component segment of the Global Edge Data Center Market encompasses both solutions and services essential for edge data center operations. The solution category includes hardware and software, where hardware components such as servers, storage systems, and networking equipment constitute the core infrastructure, enabling efficient data processing at the edge. This hardware sub-segment currently leads the market, driven by the increasing demand for advanced computing equipment to manage growing data volumes. For instance, companies like Schneider Electric introduced new edge data center solutions, including pre-integrated small data centers that are easy to set up and can be deployed in various settings. Concurrently, the software segment is gaining traction as businesses emphasize the need for efficiency, automation, and robust data security through edge-based applications for data management, security, and analytics. On the services front, the market is divided into professional and managed services. Professional services involve consulting, integration, and implementation support, helping organizations establish and optimize their edge data centers. Meanwhile, managed services, which include ongoing monitoring, maintenance, and support, are becoming increasingly popular as enterprises seek to simplify the complexity of operating distributed edge networks while ensuring optimal performance and security. This dual focus on comprehensive solutions and reliable services highlights the dynamic nature of the component segment, catering to the diverse needs of businesses adopting edge computing technologies.
By Facility Size
The global edge data center market is segmented into small and medium facilities and large facilities, each catering to distinct computing needs. Small and medium facilities, characterized by their smaller footprints, are typically deployed in remote locations, retail outlets, and urban settings to support localized computing requirements. These facilities facilitate real-time data processing for local applications, driven by the rapid proliferation of IoT devices and the increasing demand for low-latency data processing across various sectors. For instance, small and medium facilities can be defined with 1 to 12 racks with a power draw of 6 to 12 kW per cabinet. On the other hand, large edge data centers are designed to manage higher volumes of data and support more extensive networks. Positioned closer to central cloud data centers, these large facilities serve industries with substantial data processing needs, such as telecommunications, BFSI, and healthcare. As these industries continue to expand their edge computing capabilities, large edge data centers are becoming integral to their IT infrastructure, providing the necessary scalability and performance to handle complex and data-intensive operations. Large facilities can be defined as facilities with 12 to 49 racks with a power draw of 12 to 14 kW per cabinet.
Segments
Based on component
- Solution
- Hardware
- Software
- Service
- Professional
- Managed
Based on facility size
- Small and Medium Facility
- Large Facility
Based on end use industry
- IT and Telecom
- BFSI
- Healthcare and Lifesciences
- Gaming and Entertainment
- Others
Regional Analysis
North America (38%):
North America holds the largest market share in the global edge data center market, accounting for approximately 38% of the total revenue in 2023. The region's dominance can be attributed to the early adoption of edge computing, widespread implementation of 5G technology, and a well-established IT and telecom infrastructure. The United States, in particular, leads the market, with significant investments from major technology companies such as Google, Amazon, and Microsoft. These companies are rapidly expanding their edge data center footprints to enhance cloud and IoT services, offering lower latency and faster data processing for industries such as gaming, healthcare, and finance.
Europe (28%):
Europe holds the second-largest market share, contributing around 28% of the global edge data center market in 2023. The region is witnessing a surge in demand due to growing digitization efforts across industries and government initiatives promoting cloud services, IoT adoption, and smart city projects. Countries like Germany, the UK, and France are leading in edge computing deployments, particularly in the manufacturing and automotive sectors, where real-time data processing is crucial. Additionally, data privacy regulations such as GDPR have encouraged businesses to adopt localized data centers to comply with stringent data protection laws.
Key players
- ATC IP LLC
- Cisco Systems Inc.
- Dell Inc.
- Eaton
- EdgeConneX Inc.
- Endeavor Business Media, LLC.
- Fujitsu
- Hewlett Packard Enterprise Development LP
- Huawei Technologies Co., Ltd.
- IBM
- NVIDIA Corporation
- Schneider Electric
- Vertiv Group Corp.
- CommScope
- 365 Data Centers
Competitive Analysis
The global edge data center market is highly competitive, featuring a mix of established technology giants and specialized service providers. Companies like Cisco Systems Inc., Dell Inc., and Hewlett Packard Enterprise Development LP leverage their extensive experience and robust infrastructure to offer comprehensive edge computing solutions. These firms invest heavily in research and development to stay ahead in technology advancements and meet diverse customer needs. Specialized players such as EdgeConneX Inc. and 365 Data Centers focus on providing tailored edge data center services, emphasizing scalability and localized data processing. Additionally, companies like Schneider Electric and Vertiv Group Corp. differentiate themselves through innovative power and cooling solutions essential for efficient edge data center operations. Collaboration and strategic partnerships are common strategies employed by key players to enhance their service offerings and expand their geographical presence. Overall, the competitive landscape is driven by continuous innovation, strategic investments, and the ability to adapt to the evolving demands of edge computing.
Recent Developments
- In July 2024, American Tower announced the launch of Aggregation Edge Data Centers to extend cloud benefits to the edge
- In June 2024, Cisco revealed the Nexus HyperFabric AI Clusters, a new simplified data center infrastructure solution with NVIDIA for generative AI.
- In May 2024, Cisco expanded its cloud data center footprint in Indonesia with the launch of new Cisco Edge Data Centers.
- In April 2024, Eaton launched modular data centers for edge computing, machine learning, and AI.
- In September 2023, Eaton introduced a new software platform to help data center operators accelerate their digital transformation journey.
- In July 2024, EdgeConneX announced a major hyperscale data center development in Atlanta, with the first phase expected to be operational by 2026.
- In February 2024, Edged Energy, a subsidiary of Endeavour, launched four ultra-efficient, AI-ready data centers in the U.S., delivering 300+ MW and saving 1.2 billion gallons of water each year.
- In February 2024, Fujitsu announced a new AI strategy, including the launch of Fujitsu Data Intelligence PaaS and Fujitsu Kozuchi, a dedicated AI platform.
- In June 2024, HPE and NVIDIA announced the NVIDIA AI Computing by HPE, a portfolio of co-developed AI solutions to accelerate the adoption of generative AI.
- In June 2023, IBM announced the construction of its first European Quantum Data Center in Ehningen, Germany, expected to be operational in 2024.
- In June 2024, NVIDIA collaborated with HPE to launch the NVIDIA AI Computing by HPE, a portfolio of AI solutions.
Market Concentration and Characteristics
The global edge data center market is characterized by moderate to high concentration, with a few key players dominating the landscape while numerous smaller companies and new entrants contribute to growth and innovation. Major players such as Equinix, Digital Realty, and NTT Communications lead in terms of market share and infrastructure capabilities, offering extensive services that include colocation, cloud services, and interconnectivity. The market exhibits increasing competition driven by the rising demand for low-latency services, IoT applications, and data processing at the network edge. Additionally, regional players are emerging, focusing on localized services to meet specific customer needs. Overall, the market's characteristics reflect a dynamic environment shaped by technological advancements and the growing importance of edge computing in various sectors, including telecommunications, retail, and healthcare.
Report Coverage
The research report offers an in-depth analysis based on Component, Facility size, end use industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The rise of IoT devices and real-time applications will drive demand for edge data centers, enabling faster data processing and reduced latency.
- The deployment of 5G technology will facilitate the growth of edge data centers, enhancing connectivity and allowing for more efficient data management at the edge.
- Industries such as healthcare, automotive, and retail will increasingly adopt edge computing solutions, necessitating more localized data processing capabilities.
- As cyber threats evolve, edge data centers will implement advanced security protocols to protect sensitive data and maintain compliance with regulations.
- Edge data centers will focus on energy efficiency and renewable energy sources, addressing environmental concerns and reducing operational costs.
- The integration of AI and machine learning technologies will optimize data management and processing at the edge, improving overall system efficiency.
- Major technology companies will invest heavily in edge infrastructure to enhance their service offerings and meet the growing demand for edge computing solutions.
- Partnerships between telecommunications companies and cloud service providers will accelerate the deployment of edge data centers, enhancing network capabilities and service delivery.
- Organizations will increasingly focus on compliance with data sovereignty regulations, driving the need for localized edge data centers that can meet these requirements.
- The combination of on-premises edge data centers and cloud services will become prevalent, providing organizations with flexible and scalable solutions tailored to their specific needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Global Edge Data Center Market?
What are the primary drivers of the edge data center market?
Which regions are leading the Global Edge Data Center Market?
What are the key challenges faced by the edge data center market?
Who are the major players in the Global Edge Data Center Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Edge Data Center Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Edge Data Center Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 10,504.75 million → 2032: USD 61,945.36 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Edge Data Center Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Edge Data Center Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Edge Data Center Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Edge Data Center Market Drivers
- 3.3 Edge Data Center Market Restraints & Challenges
- 3.4 Edge Data Center Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Edge Data Center Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Edge Data Center Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Edge Data Center category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Edge Data Center Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Edge Data Center Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Edge Data Center market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Edge Data Center Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Edge Data Center Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Edge Data Center Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Edge Data Center (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Edge Data Center Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Edge Data Center Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Edge Data Center Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Edge Data Center Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Edge Data Center Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Edge Data Center Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Edge Data Center Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Edge Data Center Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Edge Data Center Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
