
Market Overview
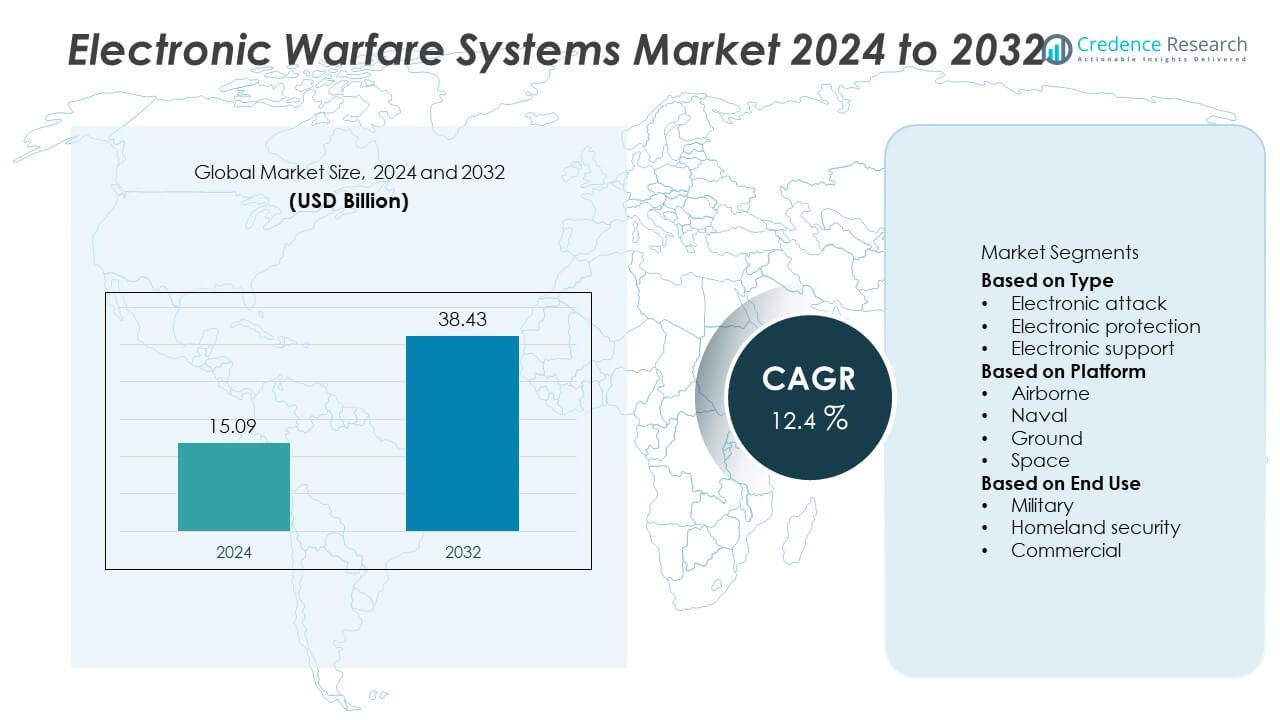
The global electronic warfare systems market was valued at USD 15.09 billion in 2024 and is projected to reach USD 38.43 billion by 2032, growing at a CAGR of 12.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electronic Warfare Systems Market Size 2024 | USD 15.09 Billion |
| Electronic Warfare Systems Market, CAGR | 12.4% |
| Electronic Warfare Systems Market Size 2032 | USD 38.43 Billion |
The electronic warfare systems market is led by major players such as Elbit Systems, China Electronics Technology Group, ASELSAN, Bharat Electronics, IAI, Hanwha Systems, Indra Sistemas, Hensoldt, EDGE Group, and BAE Systems. These companies dominate through advanced research, integrated defense technologies, and strong government partnerships. North America led the market in 2024 with a 37% share, driven by high defense budgets and modernization of air and naval fleets. Europe followed with a 29% share, supported by collaborative defense programs and indigenous technology development, while Asia-Pacific accounted for a 25% share, propelled by increased regional defense spending and growing adoption of AI-driven electronic warfare systems.
Market Insights
- The global electronic warfare systems market was valued at USD 15.09 billion in 2024 and is projected to reach USD 38.43 billion by 2032, growing at a CAGR of 12.4% during 2025–2032.
- Rising defense modernization programs, cross-border conflicts, and increased investment in signal intelligence and radar countermeasure technologies are driving market growth.
- Key trends include AI and machine learning integration, development of space-based EW platforms, and focus on cyber-resilient electronic protection systems.
- Leading players such as Elbit Systems, BAE Systems, Hensoldt, Bharat Electronics, and ASELSAN are expanding portfolios through partnerships and next-generation EW solutions.
- North America led with a 37% share, followed by Europe at 29% and Asia-Pacific at 25%, while the electronic attack segment dominated with a 46% share, supported by growing demand for advanced jamming and countermeasure technologies across air, land, and naval platforms.
Market Segmentation Analysis:
By Type
The electronic attack segment dominated the electronic warfare systems market in 2024, holding a 46% share. This dominance is driven by the growing need to disrupt, deceive, or disable enemy radar and communication systems in modern combat. Increasing adoption of jamming, spoofing, and directed-energy technologies enhances the effectiveness of electronic attack operations. Defense forces worldwide are investing in next-generation electronic attack suites to strengthen offensive capabilities and counter radar-guided threats. Continuous advancements in signal processing and electronic countermeasures are further boosting demand for these systems across both airborne and ground-based defense platforms.
- For instance, BAE Systems developed the AN/ASQ-239 electronic warfare suite for the F-35 Lightning II. The advanced system integrates wideband radar jamming and geolocation functions, providing offensive and defensive electronic attack capability across 360 degrees for enhanced situational awareness.
By Platform
The airborne segment led the market in 2024 with a 41% share, supported by the rising use of advanced aircraft-mounted EW systems for surveillance, jamming, and radar suppression. Modern fighter jets, UAVs, and military helicopters are increasingly integrated with sophisticated EW suites to enhance survivability and mission success in contested airspace. Nations such as the U.S., Russia, and China are investing heavily in airborne EW capabilities to gain tactical superiority. The segment benefits from growing adoption of next-generation radar warning receivers, electronic countermeasures pods, and cyber-resilient avionics.
- For instance, Elbit Systems equipped the Israeli Air Force's F-16I aircraft with an advanced airborne self-protection suite featuring an electronic warfare system, an electro-optical passive missile warning and launch detection system (PAWS), and a chaff and flare dispensing system.
By End Use
The military segment accounted for a 78% share of the electronic warfare systems market in 2024, dominating due to extensive defense modernization and battlefield digitization initiatives. Global armed forces are prioritizing EW technologies to protect communication networks, detect enemy signals, and counter electronic threats in real time. The increasing use of electronic protection and support systems for intelligence, surveillance, and reconnaissance (ISR) further strengthens military dominance. Rising defense budgets in the U.S., China, India, and NATO countries continue to drive large-scale EW system procurement and integration across multiple platforms.
Key Growth Drivers
Increasing Global Defense Modernization and Military Spending
Rising geopolitical tensions and the growing sophistication of electronic threats are driving defense modernization efforts worldwide. Countries such as the U.S., China, and India are heavily investing in electronic warfare systems to enhance battlefield situational awareness and counter radar or communication disruptions. The focus on multi-domain operations-combining air, land, sea, and space-further supports adoption. Integration of advanced sensors, AI-enabled analytics, and networked EW suites strengthens defense forces’ ability to detect and neutralize hostile signals, ensuring operational dominance across evolving combat environments.
- For instance, RTX subsidiary Raytheon developed the AN/ALQ-249 Next Generation Jammer Mid-Band (NGJ-MB) system, which delivers significantly enhanced power through an active electronically scanned array (AESA) architecture.
Advancements in Signal Intelligence and Radar Countermeasure Technologies
Continuous advancements in signal intelligence (SIGINT) and radar countermeasure technologies are major growth drivers for the electronic warfare systems market. Modern EW platforms are increasingly equipped with adaptive jammers, frequency-hopping systems, and cognitive electronic attack tools to counter dynamic radar threats. These innovations improve mission accuracy and resilience against next-generation guided weapons. Governments and defense contractors are developing multi-spectral and digital radio frequency memory (DRFM) systems to enable faster, more efficient electronic responses, ensuring stronger protection and tactical superiority during high-intensity conflicts.
- For instance, HENSOLDT developed the Kalaetron Attack electronic countermeasure system, which uses artificial intelligence and a fully digitized, broadband sensor to quickly detect and counter a wide spectrum of modern radar threats.
Rising Demand for Integrated and Cyber-Resilient EW Solutions
The growing convergence of cyber warfare and electronic warfare has accelerated demand for integrated and cyber-resilient EW systems. Defense forces seek solutions capable of real-time signal interception, data analysis, and protection against electromagnetic and cyber attacks. Integrated platforms combining electronic attack, support, and protection capabilities offer comprehensive situational control. Major defense suppliers are emphasizing network security, encryption, and AI-based decision-making within EW frameworks. This integration ensures interoperability across command systems and provides enhanced protection against both electronic and digital threats in modern defense networks.
Key Trends & Opportunities
Emergence of AI and Machine Learning in EW Operations
Artificial intelligence and machine learning are transforming electronic warfare efficiency by enabling autonomous signal detection, classification, and response. AI-driven EW systems can rapidly analyze large electromagnetic datasets to identify threats and initiate countermeasures without manual intervention. This trend enhances operational speed and decision accuracy in dynamic combat environments. Defense organizations are partnering with tech companies to develop adaptive AI algorithms for next-generation EW platforms. As automation increases, AI integration presents opportunities for faster threat response and greater survivability across electronic battlefields.
- For instance, L3Harris Technologies is developing the AN/ALQ-249(V)2 Next Generation Jammer-Low Band (NGJ-LB) system, which will augment and eventually replace the AN/ALQ-99 Tactical Jamming System on the EA-18G Growler aircraft.
Expansion of Space-Based and Unmanned EW Platforms
Space-based and unmanned platforms are creating new growth opportunities for electronic warfare applications. Satellites and UAVs equipped with EW payloads offer enhanced surveillance, jamming, and communication disruption capabilities over large operational areas. Nations are developing space-enabled EW architectures to strengthen strategic defense postures. The integration of EW payloads on drones and small satellites enables persistent coverage, reduced operational risk, and cost efficiency. This shift toward unmanned and orbital EW systems represents a major evolution in future warfare capabilities and global defense strategy.
- For instance, Israel Aerospace Industries (IAI) developed the Scorpius-G electronic warfare system, a powerful ground-based platform mounted on a rugged all-terrain vehicle and deployable in network mode to protect a wide geographic area.
Key Challenges
High Development Costs and System Complexity
Developing advanced electronic warfare systems involves significant investment in R&D, specialized technology, and skilled personnel. The complexity of integrating multiple sensors, software, and communication modules into a single platform drives up costs. Smaller defense economies struggle to match the rapid pace of innovation due to limited budgets. Additionally, ensuring interoperability between legacy and modern EW systems adds further technical challenges. High production and maintenance expenses remain a key barrier to wider adoption, especially among developing nations and mid-tier defense contractors.
Vulnerability to Emerging Cyber and Electronic Countermeasures
As EW systems become more connected and data-driven, they face growing risks from cyberattacks and electronic countermeasures. Adversaries are developing advanced techniques to jam signals, spoof sensors, or infiltrate EW networks. These vulnerabilities can compromise operational integrity and battlefield communications. Ensuring data encryption, secure networks, and resilience against signal interference is increasingly critical. Defense organizations must continuously upgrade EW frameworks to stay ahead of evolving threats. The rising sophistication of enemy countermeasures poses an ongoing challenge for system reliability and defense readiness.
Regional Analysis
North America
North America held a 37% share of the electronic warfare systems market in 2024, driven by strong defense budgets and continuous modernization of military infrastructure. The U.S. Department of Defense remains the primary contributor, focusing on integrating advanced electronic attack and countermeasure systems into air, land, and naval fleets. The region benefits from a robust presence of key defense contractors such as BAE Systems, Northrop Grumman, and Raytheon. Increased investments in AI-powered threat detection and electronic protection systems strengthen operational readiness. Ongoing geopolitical focus on electronic dominance continues to support sustained market growth across North America.
Europe
Europe accounted for a 29% share of the global market in 2024, fueled by defense collaborations and modernization efforts across NATO member countries. Nations like the UK, France, and Germany are deploying advanced electronic support and protection systems to enhance situational awareness. The European Defence Fund supports joint research programs focusing on next-generation EW technologies. Regional defense firms such as Hensoldt, Indra Sistemas, and BAE Systems are leading innovations in radar countermeasures and signal intelligence. Growing tensions in Eastern Europe and regional security initiatives are further accelerating electronic warfare system adoption.
Asia-Pacific
Asia-Pacific captured a 25% share in 2024, reflecting rapid expansion of defense capabilities and increasing regional security concerns. China, India, Japan, and South Korea are investing heavily in indigenous EW development to strengthen air and maritime defense. China dominates regional production with advanced jamming and interception systems, while India’s “Make in India” program supports localized manufacturing. Japan and South Korea are adopting EW systems integrated with stealth aircraft and naval platforms. Rising defense budgets, cross-border tensions, and technological collaborations continue to position Asia-Pacific as a fast-growing hub for EW advancements.
Latin America
Latin America accounted for a 5% share of the electronic warfare systems market in 2024, supported by gradual modernization of defense capabilities. Brazil leads the region with significant investments in radar surveillance and electronic protection systems for its air and naval forces. Mexico and Chile are also enhancing border and communication security using EW technologies. Despite limited budgets, partnerships with international defense firms are facilitating access to advanced technologies. The growing need for intelligence and counter-threat operations is slowly driving adoption of electronic warfare solutions across the region.
Middle East & Africa
The Middle East & Africa region held a 4% share in 2024, driven by rising geopolitical tensions and strategic defense investments. Countries such as Israel, Saudi Arabia, and the UAE are leading adopters of advanced EW systems for air and missile defense. Israel continues to dominate regional exports through technologies in radar jamming, signal interception, and electronic protection. The UAE’s focus on domestic production through partnerships with EDGE Group enhances regional self-reliance. In Africa, modernization of defense communication networks and counterterrorism operations are gradually increasing demand for electronic warfare capabilities.
Market Segmentations:
By Type
- Electronic attack
- Electronic protection
- Electronic support
By Platform
- Airborne
- Naval
- Ground
- Space
By End Use
- Military
- Homeland security
- Commercial
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the electronic warfare systems market is characterized by leading players such as Elbit Systems, China Electronics Technology Group, ASELSAN, Bharat Electronics, IAI, Hanwha Systems, Indra Sistemas, Hensoldt, EDGE Group, and BAE Systems. These companies maintain strong global positions through continuous innovation, strategic partnerships, and defense modernization programs. Major players focus on developing integrated EW suites combining electronic attack, protection, and support capabilities across airborne, naval, and ground platforms. Investments in AI-based signal processing, cyber-resilient communication, and radar countermeasure technologies are enhancing operational precision. Companies are also pursuing government contracts and multinational defense collaborations to expand their market reach. With rising geopolitical tensions, leading firms are prioritizing R&D in advanced jamming, directed-energy systems, and multi-domain electronic warfare to strengthen national defense capabilities and gain a competitive edge in global military technology markets.
Key Player Analysis
- Elbit Systems
- China Electronics Technology Group
- ASELSAN
- Bharat Electronics
- IAI
- Hanwha Systems
- Indra Sistemas
- Hensoldt
- EDGE Group
- BAE Systems
Recent Developments
- In October 2025, HENSOLDT announced expansion of its production capacity at its Ulm facility to develop and produce radars and EW systems with around 3,000 employees to support increased demand.
- In August 2025, Elbit Systems secured an $80 million contract to supply advanced self-protection suites for F-16I aircraft, enhancing EW and protection capabilities for Israel’s air force.
- In January 2025, HENSOLDT and Airbus Defence and Space equipped the German Airborne Weapon Systems Electronic Warfare Centre with new hardware and software updates for mission data processing for A400M aircraft.
- In 2025, BAE Systems signed a contract with Hanwha Aerospace to integrate next-generation anti-jamming GPS technology into Hanwha’s Deep Strike capability precision-guided weapons, enhancing resistance to EW threats.
Report Coverage
The research report offers an in-depth analysis based on Type, Platform, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand steadily with rising global defense modernization programs.
- Integration of AI and machine learning will enhance signal detection and analysis.
- Space-based and unmanned EW platforms will gain greater military adoption.
- Nations will invest more in cyber-resilient and networked EW systems.
- Demand for multi-domain and integrated electronic warfare suites will increase.
- AI-driven autonomous response systems will improve real-time battlefield effectiveness.
- Partnerships between defense firms and governments will accelerate technology development.
- Miniaturized and modular EW components will support tactical and mobile deployments.
- Asia-Pacific will emerge as a key production and deployment hub for EW systems.
- Continuous R&D in radar countermeasures and directed-energy systems will shape future advancements.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Electronic Warfare Systems market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Electronic Warfare Systems market projected to grow between 2025 and 2032?
Which Electronic Warfare Systems market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Electronic Warfare Systems market?
Who are the leading companies in the Electronic Warfare Systems market?
Which region commanded the largest share of the Electronic Warfare Systems market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 15.09 billion → 2032: USD 38.43 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electronic Warfare Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electronic Warfare Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electronic Warfare Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electronic Warfare Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electronic Warfare Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electronic Warfare Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electronic Warfare Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electronic Warfare Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 15.09 billion → 2032: USD 38.43 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electronic Warfare Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electronic Warfare Systems Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Electronic Warfare Systems Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Electronic Warfare Systems Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

