
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Emission Control Catalyst Market Size 2024 | USD 42945 million |
| Emission Control Catalyst Market, CAGR | 7.1% |
| Emission Control Catalyst Market Size 2032 | USD 74341 million |
Market Overview:
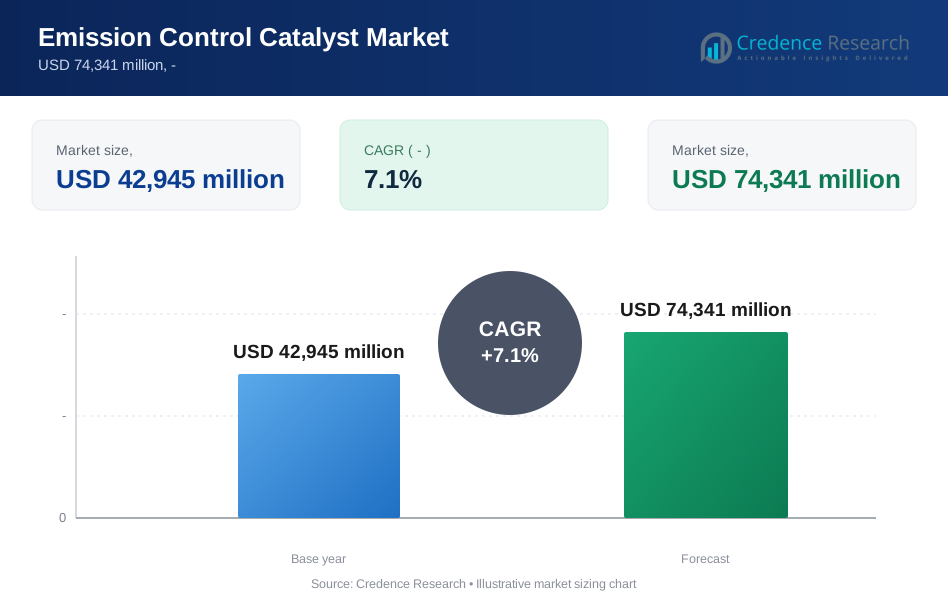
The Emission Control Catalyst Market is projected to grow from USD 42945 million in 2024 to an estimated USD 74341 million by 2032, with a compound annual growth rate (CAGR) of 7.1% from 2024 to 2032.
The primary drivers of the emission control catalyst market are increasingly stringent environmental regulations and a heightened awareness of air quality. Governments across the globe have implemented rigorous standards to reduce pollutants like nitrogen oxides (NOx), hydrocarbons, and particulate matter, especially in transportation and heavy industrial sectors. This regulatory push has led to widespread adoption of emission control catalysts, particularly in automotive applications where diesel and gasoline engines require advanced catalytic converters to meet compliance. Technological advancements in catalyst composition and design, such as improved catalytic efficiency and enhanced durability, further support market expansion by enabling longer-lasting and more effective emission control solutions. Additionally, the surging global vehicle fleet, with increased motorization in developing economies, as well as an intensified focus on sustainable practices, is driving demand for more robust emission control systems. These factors collectively fuel continuous innovation and investment in the emission control catalyst industry, addressing both environmental and economic goals.
Regionally, North America and Europe lead the market due to comprehensive regulatory frameworks and well-established automotive and industrial sectors. In Europe, nations like Germany, France, and the UK are key markets, spurred by the European Union’s stringent emission reduction mandates, which have propelled substantial advancements in emission control technologies. The North American market, particularly the U.S., is driven by similar regulatory pressures, along with incentives for cleaner technologies. In contrast, the Asia-Pacific region is experiencing the fastest growth rate due to rapid industrialization, urbanization, and rising vehicular emissions in countries such as China and India. In these regions, government initiatives aimed at combating severe air pollution issues and improving air quality standards are driving significant investments in emission control solutions. Together, these dynamics highlight a varied yet vigorous demand for emission control catalysts across major global markets, each shaped by unique regulatory, environmental, and industrial factors.
Market Drivers:
Stringent Environmental Regulations and Emission Standards:
The primary driver of the emission control catalyst market is the global push for stricter environmental regulations aimed at reducing harmful emissions. Governments and regulatory bodies worldwide have implemented stringent standards to curb pollutants such as nitrogen oxides (NOx), sulfur oxides (SOx), hydrocarbons, and particulate matter, particularly from transportation and industrial sectors. For instance, the OECD Environmental Policy Stringency (EPS) index shows that a one-unit increase in policy stringency is associated with a 4% reduction in CO2 emissions in sectors with median fossil fuel intensity after two years, and a 12% reduction after ten years. Compliance with these standards is not optional, as non-compliance often results in significant fines or restrictions. As regulations continue to tighten, industries are increasingly turning to emission control catalysts to meet these regulatory requirements, driving the market forward.
Automotive Industry Growth and Focus on Cleaner Emissions:
The automotive sector, a major contributor to emissions, is a key area where emission control catalysts are widely adopted. With a growing global vehicle fleet, especially in emerging markets where urbanization and rising disposable incomes are fueling vehicle demand, there is an urgent need for effective emission control solutions. Modern catalytic converters and diesel oxidation catalysts, which significantly reduce harmful emissions from engines, have become essential components in both passenger and commercial vehicles. Additionally, the shift towards more stringent emission standards in countries worldwide, including the Euro 6 standard in Europe and Tier 3 standards in the U.S., has intensified the demand for high-performance catalysts. As automakers increasingly prioritize compliance with these emission norms, the market for emission control catalysts in the automotive sector continues to expand.
Industrialization and Increased Energy Production:
Rapid industrialization, particularly in developing regions, has led to an increase in power generation and industrial output, both of which contribute to significant emissions. Sectors such as power generation, petrochemicals, cement, and steel production are known for releasing large volumes of pollutants, creating an urgent need for emission control measures. In response, many of these industries are implementing emission control catalysts to reduce their environmental impact and adhere to both national and international environmental standards. Furthermore, energy production from fossil fuels remains a significant contributor to NOx and SOx emissions, and the need for cleaner energy solutions is further driving the demand for emission control technologies. As industries work to mitigate their environmental footprint, the emission control catalyst market is positioned for steady growth.
Technological Advancements in Catalyst Efficiency:
Advancements in catalyst technology have further fueled the growth of the emission control catalyst market. Innovations in catalyst design and materials have led to the development of more efficient, durable, and cost-effective catalysts capable of performing under various conditions while reducing maintenance costs. For example, the introduction of novel materials, including zeolites and nano-based catalysts, has enhanced the performance of emission control systems, allowing them to function effectively at lower temperatures and over extended periods. These advancements not only improve the effectiveness of emission reduction but also meet the evolving demands of industries striving to comply with increasingly stringent standards. As technology continues to evolve, the emission control catalyst market will likely see further adoption across sectors, driven by the need for high-efficiency and sustainable solutions.
Market Trends:
Rising Demand for Sustainable and Eco-Friendly Catalysts:
A key trend in the emission control catalyst market is the increasing focus on sustainable and eco-friendly solutions. With rising environmental awareness and the need to reduce the carbon footprint, manufacturers are exploring alternatives to traditional catalytic materials. Research is focused on developing catalysts that use fewer rare and precious metals, such as platinum, palladium, and rhodium, which are costly and have environmental extraction impacts. The adoption of advanced materials, including metal oxides, zeolites, and nano-based materials, has gained traction as they offer similar efficiency with reduced reliance on scarce resources. As sustainability becomes a priority for both manufacturers and end-users, the market for emission control catalysts is seeing a shift towards green and more resource-efficient options.
Growth in the Adoption of Hybrid and Electric Vehicles:
While traditional internal combustion engine (ICE) vehicles still dominate, the shift towards hybrid and electric vehicles (EVs) is gradually influencing the emission control catalyst market. Hybrid vehicles, which combine ICE with electric power, still require emission control systems to meet regulatory standards. This demand is fostering the development of specialized catalysts for hybrid engines, which operate differently compared to conventional engines. Although fully electric vehicles do not require emission control catalysts, the hybrid segment’s growth presents a new market opportunity. For instance, Umicore reported that volumes in 2021 for proton-exchange-membrane (PEM) fuel cell catalysts used in hydrogen powered transportation almost doubled compared to 2020, positioning Umicore now at 40% global market share in the mobility segment. Additionally, as more countries impose future bans on ICE vehicles and push towards electrification, the emission control catalyst market is evolving to focus on industries beyond automotive, such as heavy machinery and industrial applications, where demand for catalytic solutions remains strong.
Increased Investment in Research and Development:
Another prominent trend in the emission control catalyst market is the surge in investment toward research and development. Companies are increasingly prioritizing R&D to create more effective, longer-lasting, and cost-efficient catalysts to meet the evolving regulatory standards. For example, Corning Incorporated invested approximately $1 billion in research, development and engineering in 2021, with a significant portion dedicated to environmental technologies like emission control products. Breakthroughs in nanotechnology, molecular engineering, and advanced coating technologies have led to the creation of catalysts that function efficiently under a broader range of conditions and reduce maintenance requirements. Innovations such as selective catalytic reduction (SCR) systems and three-way catalytic converters are results of intensive R&D efforts aimed at meeting strict emission targets. This focus on R&D has not only enhanced catalyst performance but has also opened up possibilities for tailored solutions for different applications, allowing companies to better serve diverse industries.
Regional Diversification and Expanding Applications:
As global demand for emission control catalysts grows, regional diversification and the expansion of applications are becoming key trends. Europe and North America remain significant markets due to stringent emission regulations, but the Asia-Pacific region is expected to witness the highest growth rate due to rapid industrialization, urbanization, and increasing pollution levels in countries like China and India. Furthermore, the application of emission control catalysts is expanding beyond traditional sectors like automotive and power generation into areas such as marine, aerospace, and residential heating systems, where emissions regulations are also tightening. This broadening of application areas reflects the rising global emphasis on emission reduction, positioning the emission control catalyst market for sustained, diversified growth across multiple regions and industries.
Market Restraints and Challenges:
High Cost of Precious Metals and Raw Materials:
A major restraint in the emission control catalyst market is the high cost associated with the precious metals used in catalyst manufacturing, such as platinum, palladium, and rhodium. These metals are critical for catalytic processes but are costly and subject to significant price volatility due to limited supply and high demand in various industries. The dependence on such expensive materials increases production costs, impacting the profitability of manufacturers and limiting adoption among cost-sensitive industries. Efforts to reduce reliance on these metals through alternative materials are ongoing but are yet to fully mitigate the cost impact, posing a persistent challenge.
Complexity of Regulatory Compliance and Regional Variability:
Another challenge for the emission control catalyst market is the complex and varied regulatory landscape across different regions. While stringent emission standards are beneficial for driving market demand, compliance requires continuous updates and adjustments to catalyst technologies to meet evolving standards. The differences in regulatory requirements across regions, such as Europe, North America, and Asia-Pacific, add to the complexity, as manufacturers must tailor their products to align with local standards. This regulatory fragmentation can slow market entry and increase operational costs for companies aiming to expand globally, posing a significant barrier to growth.
Competition from Electric Vehicles and Alternative Technologies:
The increasing shift toward electric vehicles (EVs) and alternative fuel technologies represents a potential challenge to the emission control catalyst market, particularly in the automotive sector. As governments promote EV adoption through incentives and phase-out plans for internal combustion engine vehicles, the demand for traditional emission control catalysts could decline over time. Additionally, alternative technologies, such as hydrogen fuel cells and renewable energy sources, are being developed to reduce emissions in sectors like power generation, which could further limit the growth of the emission control catalyst market if these alternatives gain widespread adoption.
Market Segmentation Analysis:
The emission control catalyst market is segmented by type, application, catalytic converter, and end-user industry, each playing a unique role in emission reduction across various sectors.
By Type: The market is dominated by palladium, platinum, and rhodium-based catalysts due to their high efficacy in reducing pollutants. Palladium-based catalysts are widely used in gasoline vehicles, while platinum finds extensive application in both automotive and industrial sectors due to its stability and versatility. Rhodium, crucial for NOx reduction, is essential in three-way catalytic converters. Other metals, such as vanadium, ruthenium, and iridium, are used in specific applications where durability and specialized properties are required.
By Application: Emission control catalysts serve both mobile and stationary sources. Mobile sources include on-road and off-road vehicles, with catalysts needed for both light and heavy-duty vehicles. Stationary sources, such as power plants and industrial facilities, rely on emission control catalysts to meet strict pollution control standards and reduce their environmental impact.
By Catalytic Converter: Key converter types include diesel oxidation catalysts (DOC), selective catalytic reduction (SCR), lean NOx traps (LNT), three-way catalytic converters (TWC), and four-way catalytic converters. Each type is designed to target specific pollutants, with SCR and TWC widely used for NOx reduction in diesel and gasoline engines, respectively.
By End-User Industry: The automotive sector is the largest consumer of emission control catalysts, driven by strict emission standards for vehicles. The industrial sector, including power generation and manufacturing, also employs these catalysts to reduce emissions from large-scale operations. Other industries, such as marine and aerospace, contribute to demand as regulations expand across sectors.
Segmentation:
By type
- Palladium based
- Platinum based
- Rhodium based
- Others (vanadium, ruthenium, and irirdium)
By application
- Mobile sources (off road, and on road)
- Stationary sources
By catalytic converter
- Diesel oxidation catalyst
- Selective catalytic reduction
- Lean NOx trap
- Three-way catalytic converter
- Four-way catalytic converter
By End-user Industry
- Automotive
- Industrial
- Others
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The emission control catalyst market is geographically segmented into North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. Each region exhibits unique market dynamics based on regulatory frameworks, industrial growth, and environmental concerns, influencing their respective market shares.
North America: North America holds a significant share of the emission control catalyst market, driven primarily by stringent environmental regulations from agencies such as the U.S. Environmental Protection Agency (EPA). The automotive and industrial sectors in the U.S. and Canada are major consumers, using catalysts to meet high standards for emissions reduction. The region accounts for approximately 25% of the global market. Additionally, the strong presence of leading catalyst manufacturers and continuous R&D investments further boost North America's position in the global market.
Europe: Europe is another prominent region, holding around 30% of the global market share. The European Union has imposed some of the world’s strictest emissions regulations, such as Euro 6 standards, which mandate low emissions for vehicles. These regulations have led to widespread adoption of advanced emission control technologies. Countries like Germany, France, and the UK drive the European market due to their extensive automotive manufacturing bases and a high focus on environmental sustainability. Europe’s commitment to reducing carbon footprints across industries, along with growing demand for sustainable transportation, is expected to sustain its market share in the coming years.
Asia-Pacific: Asia-Pacific is the fastest-growing region in the emission control catalyst market, with a current market share of approximately 35%. The rapid industrialization and urbanization in emerging economies such as China and India are major contributors to the region’s growth. Governments in these countries have introduced stricter emission norms to address severe pollution levels, especially in densely populated urban centers. The automotive industry’s expansion, particularly in China, Japan, and India, also drives demand for emission control catalysts, as manufacturers must comply with regional emission standards. Asia-Pacific’s growth potential remains high, as rising environmental concerns and regulatory pressure will likely drive further adoption of emission control technologies.
Latin America and the Middle East & Africa: Latin America and the Middle East & Africa collectively hold a smaller share, around 10% of the global market. However, they represent emerging opportunities due to increasing regulatory frameworks and industrial growth. In Latin America, Brazil and Mexico are seeing gradual adoption of emission control technologies in response to environmental policies aimed at improving air quality. The Middle East & Africa region, driven by industrial activities, particularly in oil and gas, is witnessing a growing need for emission control solutions. Despite their smaller market share, both regions are expected to see moderate growth as emission standards become more stringent and industrialization continues.
Key Player Analysis:
- Aerinox-Inc.
- BASF SE
- CDTi Advanced Materials Inc.
- Clariant
- CORMETECH
- DCL International Inc.
- Evonik Industries AG
- Haldor Topsoe A/S
- Hitachi Zosen Corporation
- IBIDEN Ceram GmbH
- JGC C&C
Competitive Analysis:
The emission control catalyst market is highly competitive, with a few key players holding significant market share and driving innovation through extensive R&D. Major companies, including BASF SE, Johnson Matthey, Umicore, and Tenneco Inc., dominate the market by offering a wide range of catalyst products tailored to meet stringent regulatory standards across automotive and industrial sectors. These players leverage advanced technologies, such as nano-based catalysts and multi-functional catalysts, to improve emission reduction efficiency and durability. Smaller and regional companies also contribute to market competition by focusing on niche applications and cost-effective solutions, particularly in emerging economies. Strategic partnerships, acquisitions, and expansion into high-growth regions like Asia-Pacific are common among leading companies to strengthen their market position. As regulatory pressures increase globally, companies continue investing in sustainable and eco-friendly catalyst technologies to stay competitive and meet evolving industry demands.
Recent Developments:
- In May 2024, a team of researchers from Northern Illinois University, Valparaiso University, and the U.S. Department of Energy’s Argonne National Laboratory announced the development of a new family of catalysts capable of efficiently converting CO₂ from industrial emissions into widely used chemicals, aiming to reduce environmental impact.
- In November 2023, the CHASS project was launched to extend the lifespan and efficiency of Cu-CHA catalysts, specifically to improve the environmental performance of diesel vehicles.
- In July 2023, Dr. Le Minh Thang, a researcher specializing in vitamin-based catalysts, investigated a cost-effective catalytic converter capable of reducing carbon emissions by 90%. This converter treats toxic exhaust gases from factories, transforming them into harmless components, and offering a promising solution for industrial emission control.
Market Concentration & Characteristics:
The emission control catalyst market is moderately concentrated, with key players like BASF SE, Johnson Matthey, and Umicore holding significant market shares. This market is driven by stringent environmental regulations and the increasing demand for cleaner technologies. Emission control catalysts are essential in reducing harmful pollutants from automotive and industrial emissions, making them crucial for compliance with global emission standards. The market is characterized by the dominance of platinum-based catalysts, which are highly effective in enhancing combustion and reducing emissions. Technological advancements and innovations in catalyst design are expected to further drive market growth. The Asia-Pacific region, particularly China and India, is a major consumer due to rapid industrialization and stringent emission norms. Overall, the market is poised for steady growth, supported by ongoing regulatory pressures and the global focus on sustainability.
Report Coverage:
The research report offers an in-depth analysis based on By type, By application, By catalytic converter and By End-user Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing global emissions regulations will drive steady demand for advanced catalyst solutions across industries.
- Increasing adoption of hybrid vehicles will sustain market relevance, even as electric vehicles gain market share.
- Innovations in catalyst materials, like nano-based and non-precious metal catalysts, will reduce costs and improve efficiency.
- Expanding industrialization in Asia-Pacific will fuel demand, with China and India emerging as key growth markets.
- Rising focus on sustainability will lead to a shift toward eco-friendly and resource-efficient catalyst alternatives.
- Development of multi-functional catalysts will address diverse pollutant types, meeting stricter emission standards.
- Demand for retrofit emission control solutions will grow as governments enforce stricter regulations on older equipment.
- Collaborative R&D among universities, industries, and research labs will accelerate catalyst advancements.
- Increasing government incentives for emission reduction in power generation will boost catalyst adoption in the energy sector.
- Growth in alternative sectors, such as marine and aerospace, will diversify catalyst applications and broaden market opportunities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Emission Control Catalyst Market?
What are the main drivers of this market?
Which regions dominate the emission control catalyst market?
Are there challenges facing the emission control catalyst market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Emission Control Catalyst Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Emission Control Catalyst Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 42,945 million → forecast year: USD 74,341 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Emission Control Catalyst Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Emission Control Catalyst Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Emission Control Catalyst Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Emission Control Catalyst Market Drivers
- 3.3 Emission Control Catalyst Market Restraints & Challenges
- 3.4 Emission Control Catalyst Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Emission Control Catalyst Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Emission Control Catalyst Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Emission Control Catalyst category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Emission Control Catalyst Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Emission Control Catalyst Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Emission Control Catalyst market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Emission Control Catalyst Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Emission Control Catalyst Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Emission Control Catalyst Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Emission Control Catalyst (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Emission Control Catalyst Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Emission Control Catalyst Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Emission Control Catalyst Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Emission Control Catalyst Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Emission Control Catalyst Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Emission Control Catalyst Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Emission Control Catalyst Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Emission Control Catalyst Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Emission Control Catalyst Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
