
Market Overview:
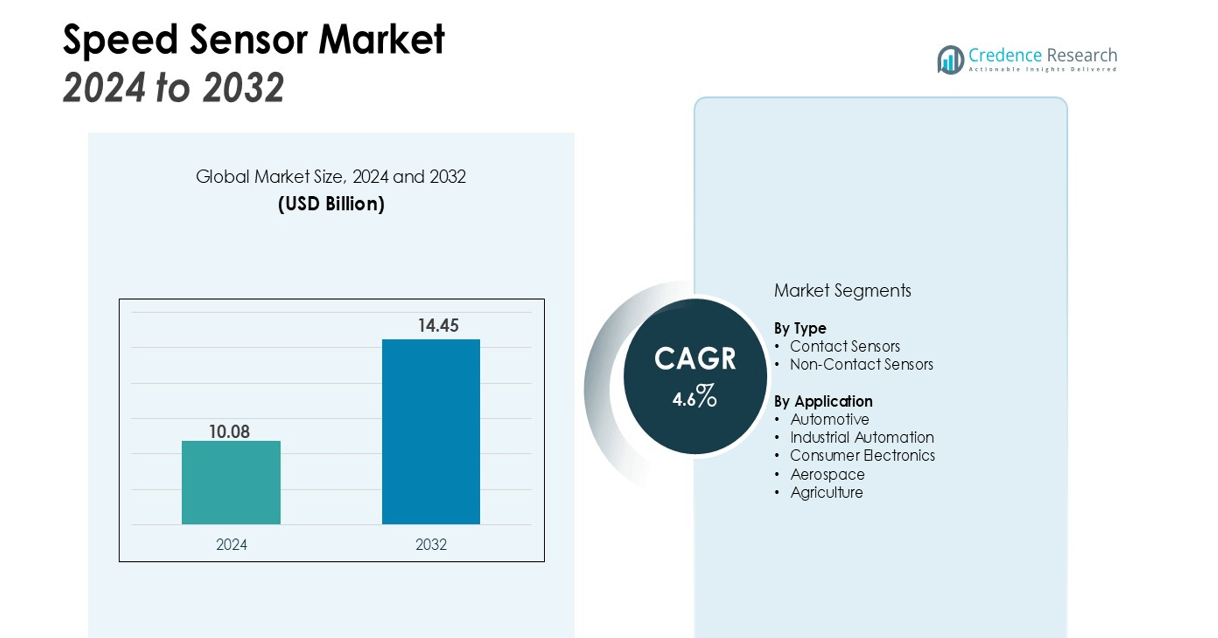
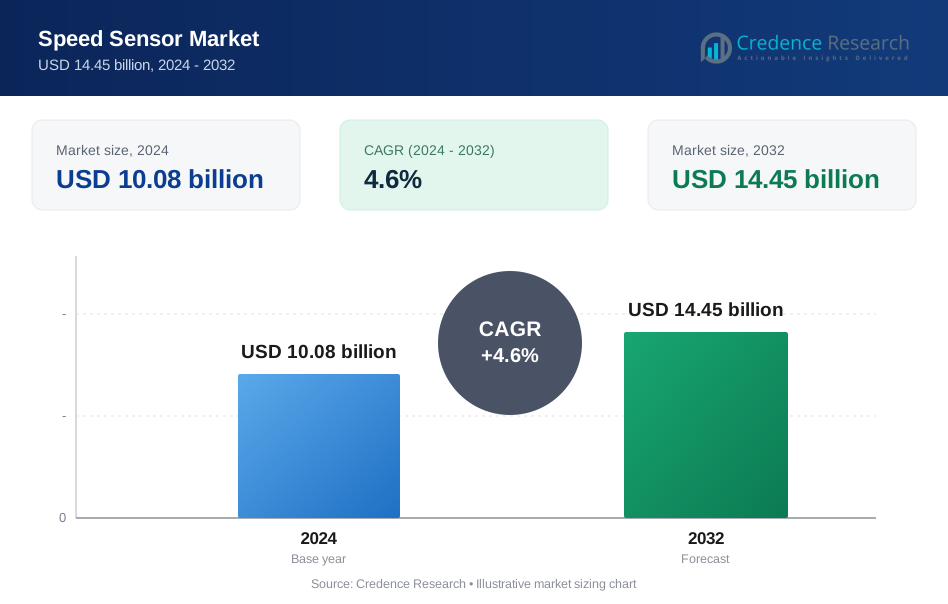
The Speed Sensor Market size was valued at USD 10.08 billion in 2024 and is anticipated to reach USD 14.45 billion by 2032, at a CAGR of 4.6% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Speed Sensor Market Size 2025 | USD 10.08 billion |
| Speed Sensor Market, CAGR | 4.6% |
| Speed Sensor Market Size 2032 | USD 14.45 billion |
Key drivers fueling market expansion include the rising adoption of electric vehicles (EVs), advancements in automotive safety systems, and the growing need for industrial automation. Speed sensors play a crucial role in enhancing vehicle performance, improving fuel efficiency, and ensuring safety by providing real-time data for control systems. Furthermore, the integration of Internet of Things (IoT) technology and smart sensors in industries to monitor equipment performance is contributing to the demand for speed sensors in industrial automation.
Regionally, North America dominates the speed sensor market, supported by strong automotive and industrial sectors. The presence of key manufacturers and advancements in autonomous vehicle technologies are driving growth in this region. Europe follows closely due to the increasing demand for speed sensors in electric vehicles and stringent safety regulations. The Asia Pacific region is expected to experience the highest growth, driven by rapid industrialization, automotive advancements, and the expansion of manufacturing facilities.
Market Insights:
- The Speed Sensor Market was valued at USD 10.08 billion in 2024 and is projected to reach USD 14.45 billion by 2032, with a CAGR of 4.6%.
- The rising adoption of electric vehicles (EVs) drives significant demand for high-precision speed sensors for motor control and performance monitoring.
- Automotive safety systems, including ADAS technologies, increase the demand for speed sensors to enable features like collision avoidance and adaptive cruise control.
- Industrial automation continues to grow, with speed sensors enhancing machinery efficiency, reducing downtime, and enabling predictive maintenance in manufacturing.
- Technological advancements, such as wireless connectivity and IoT integration, improve the performance and versatility of speed sensors across various sectors.
- North America holds a 38% market share, driven by its strong automotive and industrial sectors, particularly with EVs and autonomous driving technologies.
- Asia Pacific, with a 28% market share, is set to experience the highest growth due to rapid industrialization, automotive production, and smart manufacturing advancements.
Market Drivers:
Rising Demand for Electric Vehicles (EVs)
The increasing adoption of electric vehicles (EVs) is a significant driver for the speed sensor market. EVs require advanced control systems for efficient operation, where speed sensors play a crucial role in monitoring vehicle speed, performance, and energy consumption. The need for precision and reliability in electric motors further enhances the demand for high-quality speed sensors, as they help in optimizing power usage and maintaining smooth driving experiences. As EV adoption continues to rise globally, it will further drive the demand for speed sensors in the automotive sector.
- For instance, in July 2025, Bosch released a software update for its Performance Line CX Gen 5 motors used in e-bikes. This update increased the motor's maximum torque to 100 Nm, enhancing the performance and responsiveness for riders.
Growth of Industrial Automation and Smart Manufacturing
The ongoing trend toward industrial automation is contributing to the market’s growth. Speed sensors are essential for monitoring the performance of machinery and equipment in automated production lines. They enable real-time data collection and performance monitoring, helping industries enhance productivity and reduce downtime. It improves the efficiency of operations in sectors like manufacturing, aerospace, and energy, where machinery operates at varying speeds. The shift towards smart manufacturing technologies increases the reliance on sensors to monitor key parameters, including speed, across production environments.
- For instance, Honeywell enhanced its industrial sensor portfolio with the DG Smart Sensor for optimizing combustion systems. This device provides precise monitoring with a 4-20mA NAMUR Analog output and features MODBUS TCP digital communication to improve integration within smart factory ecosystems.
Advancements in Automotive Safety Systems
Automotive safety systems are another key factor fueling demand for speed sensors. With the rise of autonomous driving technologies and advanced driver assistance systems (ADAS), the need for precise and reliable speed sensors is critical. These sensors monitor and adjust vehicle speed to enhance safety by integrating with other systems like collision avoidance, adaptive cruise control, and stability control. It contributes to improving vehicle performance and driver safety, which increases the demand for innovative speed sensor technologies in the automotive sector.
Technological Advancements in Sensor Technologies
Technological advancements in sensor technologies have made speed sensors more accurate, durable, and adaptable to a wide range of applications. The development of smart sensors that offer wireless connectivity, IoT integration, and high-resolution data processing has enhanced their performance in various sectors, including automotive and industrial equipment. It allows for better integration with other systems, offering enhanced functionality and reliability. As sensor technologies evolve, it supports the growing adoption of speed sensors in modern machines and vehicles, further expanding the market.
Market Trends:
Integration of Speed Sensors with IoT and Smart Technologies
The integration of speed sensors with Internet of Things (IoT) technologies and smart systems is a notable trend in the market. By connecting speed sensors to cloud-based platforms, industries can gather real-time data, analyze performance metrics, and make informed decisions for maintenance and operation optimization. This trend is particularly prominent in industrial automation and automotive applications, where real-time data monitoring enhances the efficiency of operations. IoT-enabled speed sensors improve predictive maintenance, reduce downtime, and help in optimizing vehicle and machine performance. The growing adoption of smart manufacturing technologies further pushes the demand for interconnected, high-performance speed sensors, particularly in sectors like automotive, aerospace, and energy.
- For instance, New York City implemented a real-time traffic monitoring solution by deploying an IoT communication backbone to 14,000 intersections.
Miniaturization and Improved Sensor Performance
Another significant trend is the miniaturization of speed sensors while maintaining or enhancing their performance. The growing demand for compact, lightweight, and high-performance sensors is driven by the need for more efficient space utilization, especially in automotive and consumer electronics applications. Smaller, more efficient speed sensors enable their use in various applications, from electric vehicles to mobile devices, without compromising their accuracy or durability. Improved sensor performance, including higher resolution and faster response times, makes them increasingly valuable in precision monitoring systems, where reliable data is crucial for operational success. The continued development of miniaturized and high-performance speed sensors is expected to drive innovation across a wide range of industries.
- For instance, Race Technology’s SPEEDBOX MINI, a high-accuracy non-contact speed sensor, achieves a speed accuracy of 0.02m/s, this compact sensor is designed for professional automotive testing and utilizes a 20Hz PurePhase GPS solution for its precise measurements.
Market Challenges Analysis:
High Costs of Advanced Speed Sensors
One of the primary challenges facing the speed sensor market is the high cost of advanced sensors. These sensors, particularly those with high precision and additional features such as wireless connectivity or integration with IoT systems, tend to be more expensive. The cost of raw materials, development, and manufacturing processes significantly impacts the price of these sensors. Smaller manufacturers, particularly in emerging markets, may struggle to afford these high-end solutions, which limits market access. Balancing performance with affordability remains a critical challenge, especially as industries seek cost-effective solutions without compromising on quality.
Varying Standards and Compatibility Issues
The lack of standardized regulations and compatibility issues between different sensor models present challenges in the speed sensor market. Variations in sensor specifications, design, and communication protocols across manufacturers can create difficulties in ensuring seamless integration with existing systems. The absence of industry-wide standards complicates the widespread adoption of speed sensors, especially in industries like automotive and industrial automation. For many organizations, integrating sensors with legacy systems without disruptions remains a hurdle. Addressing these compatibility issues requires both technical innovation and the development of global standards to ensure smooth market expansion.
Market Opportunities:
Expansion in Electric Vehicle and Autonomous Driving Applications
The rapid growth of the electric vehicle (EV) market presents a significant opportunity for the speed sensor industry. EVs rely heavily on accurate speed monitoring for efficient power management, vehicle performance, and safety features. Speed sensors play an essential role in controlling the motor speed, regenerative braking, and overall energy efficiency in electric drivetrains. As the demand for EVs continues to rise, there will be an increasing need for advanced speed sensors that can meet the performance and durability requirements of these vehicles. Autonomous driving technology further expands the market for these sensors, as they are crucial for the precise operation of control systems in self-driving vehicles.
Growth of Industrial Automation and Smart Manufacturing
The industrial automation sector offers significant growth opportunities for the speed sensor market. As industries continue to adopt smart manufacturing solutions, the need for accurate, real-time data becomes increasingly important. Speed sensors enable precise control of machinery and equipment, helping to optimize production processes, reduce downtime, and enhance overall efficiency. As manufacturers strive for more advanced and automated systems, the demand for high-performance speed sensors that integrate with IoT platforms and support predictive maintenance will continue to rise. This trend will open new avenues for growth across various industries, including automotive, aerospace, and energy.
Market Segmentation Analysis:
By Type
The Speed Sensor market is primarily divided into two types: contact and non-contact sensors. Contact sensors are widely used in automotive applications for monitoring wheel speed, engine speed, and transmission speed. These sensors rely on physical contact with rotating parts, offering precise measurements. Non-contact sensors, on the other hand, use technologies like optical or magnetic sensing and are increasingly favored for their durability and longer lifespan. Non-contact sensors are preferred in harsh industrial environments due to their ability to measure speed without physical wear and tear, making them ideal for applications where reliability is crucial.
- For instance, Honeywell's SNDH-T Series Hall-effect speed sensors are designed for high-resolution applications, featuring an operational air gap of up to 2 mm for enhanced performance and accuracy in automotive environments.
By Application
In terms of application, the Speed Sensor market spans across automotive, industrial, and consumer electronics sectors. In the automotive sector, speed sensors are essential for monitoring vehicle speed, engine performance, and safety systems such as adaptive cruise control and stability control. In industrial automation, speed sensors are critical for monitoring machinery, ensuring operational efficiency, and preventing equipment failures. In consumer electronics, these sensors are integrated into devices like smartphones and wearables to track movement and speed. The growing demand for automation and smart devices continues to drive the need for accurate and reliable speed sensors across all sectors.
- For instance, the Siemens SITRANS WM100 non-contact speed sensor is built for harsh industrial use, operating reliably in temperatures from -40°C to +60°C and monitoring equipment with a dynamic range of up to 3,000 pulses per minute.
Segmentations:
By Type
- Contact Sensors
- Non-Contact Sensors
By Application
- Automotive
- Industrial Automation
- Consumer Electronics
- Aerospace
- Agriculture
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a market share of 38% in the speed sensor industry. The region’s advanced automotive and industrial sectors drive strong demand for speed sensors. The U.S. automotive industry, in particular, heavily relies on these sensors for vehicle performance, safety, and efficiency. With the growing adoption of electric vehicles (EVs) and autonomous driving technologies, the need for advanced sensors continues to increase. The presence of key players and the region’s focus on technological advancements, such as IoT integration, further contribute to its market leadership. Robust infrastructure and high adoption of industrial automation support steady growth in North America.
Europe
Europe commands a market share of 30% in the speed sensor industry. Significant demand arises from both the automotive and industrial automation sectors. The region’s strong automotive manufacturing base, with investments in EVs and smart technologies, increases the need for precision sensors. Stringent vehicle safety and emissions regulations in the European Union further drive demand for advanced speed sensors. The emphasis on Industry 4.0 and the digitalization of manufacturing processes also supports the growing demand for automation solutions. Key markets like Germany, France, and the UK continue to lead the growth due to their established industrial and automotive sectors.
Asia Pacific
Asia Pacific accounts for 28% of the global market share in the speed sensor industry. The region is poised for the highest growth, driven by rapid industrialization and increased automotive production. Countries like China, Japan, and India are seeing substantial growth in both traditional and electric vehicle markets, driving demand for speed sensors. The adoption of industrial automation in China and South Korea further accelerates the need for high-performance sensors. Government investments in infrastructure development and smart manufacturing solutions enhance market growth potential. The Asia Pacific region is expected to be a key player in the speed sensor market's future expansion.
Key Player Analysis:
- Allegro MicroSystems, Inc
- TE Connectivity, Inc
- Sensoronix, Inc
- Infineon Technologies AG
- SICK AG
- Petasense
- Sensor Solutions Corporation
- SPECTEC
- Robert Bosch GmbH
- NXP Semiconductors N.V
Competitive Analysis:
The Speed Sensor market is highly competitive, with key players such as Honeywell International Inc., Bosch, Continental AG, and Delphi Technologies leading the way. These companies focus on enhancing sensor performance and expanding product portfolios to meet the rising demand from automotive and industrial automation sectors. They invest in research and development to improve accuracy, durability, and integration with emerging technologies like IoT and advanced driver-assistance systems (ADAS). Strategic partnerships with OEMs and automakers help integrate speed sensors into electric vehicles and autonomous driving systems. Companies also target expansion in regions like Asia Pacific, driven by growing automotive production and industrial automation. This competitive landscape continues to evolve, with advancements in sensor technology shaping future market trends.
Recent Developments:
- In September 2025, SICK AG expanded its digital portfolio with the introduction of new sensor models for simulation within the NVIDIA Omniverse platform.
- In May 2025, Allegro MicroSystems and Wodeer signed a strategic partnership to co-develop technology and pursue joint growth in the automotive and industrial sectors.
- In February 2025, NXP Semiconductors N.V. announced a definitive agreement to acquire Kinara, Inc., a specialist in discrete neural processing units (NPUs), for $307 million in an all-cash deal.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for speed sensors will continue to grow due to the increasing adoption of electric vehicles (EVs) and autonomous driving technologies.
- Technological advancements, such as IoT integration and wireless connectivity, will enhance the functionality and efficiency of speed sensors.
- The automotive sector will remain the largest application area, with a focus on enhancing vehicle performance, safety, and energy efficiency.
- Industrial automation will increasingly rely on speed sensors for real-time monitoring, predictive maintenance, and optimizing machinery performance.
- Demand for non-contact speed sensors will rise due to their durability, precision, and suitability for harsh industrial environments.
- The growing trend of smart manufacturing and Industry 4.0 will create new opportunities for speed sensors in automated production lines.
- Asia Pacific will continue to experience the highest growth, driven by rapid industrialization and expanding automotive markets in China, India, and Japan.
- Europe and North America will remain key markets, supported by advancements in automotive technologies and strong industrial sectors.
- The integration of speed sensors with advanced driver assistance systems (ADAS) and autonomous vehicles will spur innovations in automotive safety.
- Increased focus on sustainability and energy efficiency will push for the development of eco-friendly, high-performance speed sensors in various applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Speed Sensor, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Speed Sensor projected to grow between 2024 and 2032?
Which Speed Sensor segment held the largest share in 2024?
What are the primary factors fueling the growth of the Speed Sensor?
Who are the leading companies in the Speed Sensor?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Speed Sensor Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Speed Sensor Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 10.08 billion → 2032: USD 14.45 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Speed Sensor Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Speed Sensor Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Speed Sensor Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Speed Sensor Market Drivers
- 3.3 Speed Sensor Market Restraints & Challenges
- 3.4 Speed Sensor Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Speed Sensor Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Speed Sensor Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Speed Sensor category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Speed Sensor Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Speed Sensor Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Speed Sensor market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Speed Sensor Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Speed Sensor Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Speed Sensor Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Speed Sensor (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Speed Sensor Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Speed Sensor Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Speed Sensor Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Speed Sensor Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Speed Sensor Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Speed Sensor Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Speed Sensor Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Speed Sensor Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Speed Sensor Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
