
Market Overview
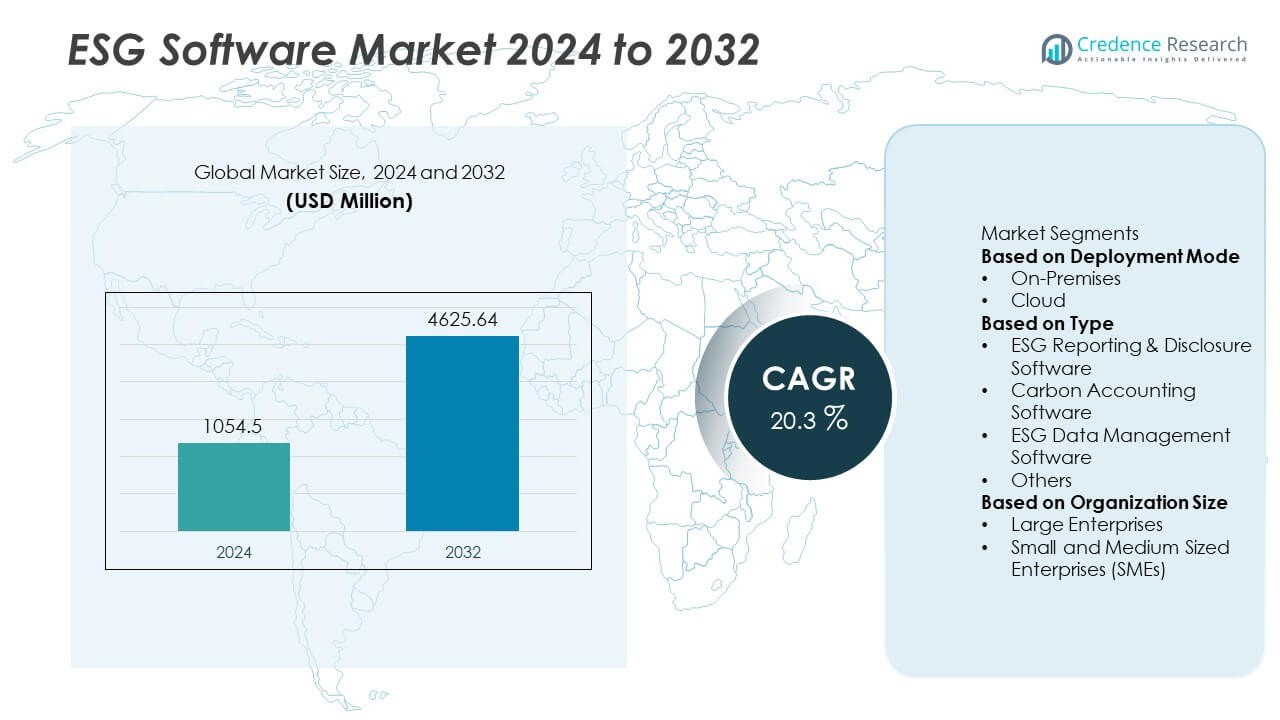
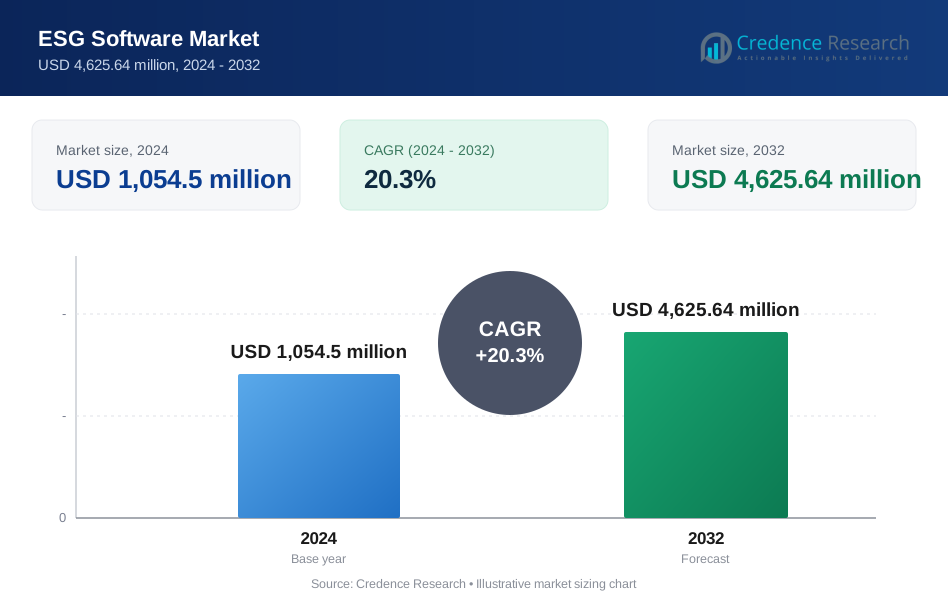
The ESG Software market size was valued at USD 1,054.5 million in 2024 and is projected to reach USD 4,625.64 million by 2032, growing at a CAGR of 20.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| ESG Software Market Size 2024 | USD 1,054.5 Million |
| ESG Software Market, CAGR | 20.3% |
| ESG Software Market Size 2032 | USD 4,625.64 Million |
The ESG software market is led by prominent players including LogicManager Inc., Enablon SA, Novisto Inc., ESG Enterprise Inc., Intelex Technologies Inc., Nasdaq Inc., IsoMetrix Software (Pty) Ltd, Envizi Pty Ltd, Diligent Corporation, and Benchmark Gensuite Inc. These companies drive innovation through AI-enabled reporting, cloud deployment, and integrated sustainability solutions to meet evolving disclosure and compliance demands. North America emerged as the leading region in 2024, holding 38% of the total market share, supported by strong regulatory frameworks and early technology adoption. Europe followed closely with 32% share, driven by the EU’s stringent ESG disclosure mandates. Asia-Pacific accounted for 20% share, reflecting rapid adoption fueled by regulatory alignment and investor expectations.
Market Insights
- The ESG software market was valued at USD 1,054.5 million in 2024 and is projected to reach USD 4,625.64 million by 2032, expanding at a CAGR of 20.3% during the forecast period.
- Rising regulatory mandates such as EU CSRD and SEC climate disclosure rules are fueling demand for ESG reporting and carbon accounting platforms, with large enterprises driving over 70% of adoption.
- AI-driven automation, cloud-based deployment capturing 65% share, and expansion into supply chain sustainability represent the key trends shaping future opportunities in the market.
- Leading players including LogicManager Inc., Enablon SA, Novisto Inc., and Nasdaq Inc. are focusing on partnerships, acquisitions, and product enhancements to strengthen their global presence amid increasing competition.
- North America leads with 38% share, followed by Europe at 32% and Asia-Pacific at 20%, while ESG reporting software dominates by type with 40% market share in 2024.
Market Segmentation Analysis:
By Deployment Mode
The cloud-based deployment segment dominated the ESG software market in 2024, accounting for nearly 65% of total share. Its growth is driven by scalability, cost efficiency, and ease of integration with enterprise systems. Companies increasingly prefer cloud platforms to support real-time ESG data reporting and global accessibility, aligning with regulatory requirements and sustainability disclosures. On-premises solutions, holding the remaining share, remain relevant in organizations with strict data security mandates. However, the flexibility and faster implementation cycles of cloud-based ESG solutions reinforce its leading position across industries.
- For instance, Envizi, integrated within IBM's cloud ecosystem, supports sustainability reporting for a range of companies, including Digital Realty, across their global facilities. Envizi is also used by other major companies like Microsoft, Cigna, and Unilever, with IBM having acquired the software in 2022.
By Type
ESG reporting and disclosure software emerged as the leading type in 2024, representing around 40% of the market share. The dominance reflects rising global regulations, such as EU CSRD and SEC climate disclosure rules, which mandate transparent ESG reporting. Companies are investing in advanced reporting platforms to manage compliance, improve investor relations, and enhance stakeholder trust. Carbon accounting software and ESG data management tools also gained momentum due to climate goals and pressure to monitor supply chain impacts. Still, reporting and disclosure solutions remain the most widely adopted, driving compliance-led growth.
- For instance, Novisto's ESG reporting platform manages disclosures for global enterprises, processing large amounts of structured and unstructured data to help clients align with CSRD and ISSB standards.
By Organization Size
Large enterprises held the dominant share of over 70% of the ESG software market in 2024. Their leadership comes from stronger regulatory exposure, broader sustainability commitments, and higher budgets to adopt advanced ESG platforms. These organizations prioritize robust ESG frameworks to address investor expectations and achieve net-zero goals. Small and medium-sized enterprises (SMEs), while holding a smaller share, are steadily adopting ESG tools to enhance competitiveness and meet supply chain requirements set by larger corporations. Growing demand for affordable, user-friendly platforms supports SME adoption, though large enterprises continue to drive the bulk of market revenues.
Key Growth Drivers
Regulatory Compliance and Disclosure Mandates
Global regulatory frameworks are the primary driver of ESG software adoption. Rules such as the EU Corporate Sustainability Reporting Directive (CSRD) and proposed SEC climate disclosure mandates require organizations to track, measure, and publish ESG performance. This increasing regulatory scrutiny compels enterprises to adopt software solutions for structured reporting, audit-ready documentation, and compliance alignment. The pressure to demonstrate transparency and accountability strengthens demand for ESG platforms that streamline data collection, verification, and disclosure across diverse operational and supply chain environments.
- For instance, Enablon supports hundreds of leading enterprises with ESG compliance tools for reporting, aligning with frameworks like CSRD and SASB. Novisto processes ESG disclosures for numerous enterprises, ensuring compliance with standards from the IFRS Foundation and EU directives, including CSRD.
Rising Investor and Stakeholder Demand
Growing emphasis from investors and stakeholders on ESG performance significantly drives software adoption. Asset managers, rating agencies, and institutional investors rely on ESG data to assess company resilience and long-term value creation. Companies are leveraging ESG platforms to improve ratings, attract green capital, and strengthen reputational standing. Transparent disclosure enabled by advanced ESG software enhances credibility and trust. As investor focus on ESG-linked financial performance intensifies, businesses increasingly adopt reporting and management platforms to meet expectations and ensure continuous access to sustainable funding sources.
- For instance, Diligent provides ESG and governance tools to more than 750,000 board members and executives worldwide, ensuring transparency for investors across 25,000 organizations.
Corporate Sustainability and Net-Zero Goals
Commitments toward sustainability and net-zero targets are fueling ESG software demand. Large enterprises and multinational corporations set ambitious goals for reducing emissions, improving social responsibility, and ensuring governance excellence. ESG platforms help organizations measure progress against science-based targets, manage energy usage, and assess supplier sustainability performance. By integrating ESG metrics into corporate strategy, companies gain actionable insights to achieve long-term sustainability goals. The need to demonstrate tangible progress toward net-zero and broader ESG commitments further accelerates adoption of software-driven ESG management frameworks.
Key Trends & Opportunities
Integration of AI and Automation
AI-driven analytics and automation are reshaping the ESG software landscape. Platforms increasingly integrate machine learning for predictive insights, anomaly detection, and automated reporting. This trend reduces manual errors, enhances efficiency, and supports real-time ESG tracking. Automated solutions also enable companies to map supplier risks and track carbon footprints at scale. The rising adoption of AI in ESG platforms represents a strong opportunity for vendors to differentiate their solutions, offering advanced analytics and strategic decision support to businesses navigating complex sustainability landscapes.
- For instance, LogicManager applies machine learning across datasets, enhancing automated risk identification and predictive compliance monitoring.
Expansion of ESG in Supply Chain Management
Supply chain sustainability is emerging as a critical opportunity area for ESG software. Companies face growing pressure to monitor supplier practices, carbon intensity, and labor conditions. ESG platforms now include tools for mapping risks, assessing compliance, and managing supplier disclosures. This expansion aligns with regulatory and stakeholder expectations that extend beyond company boundaries. Vendors offering supply chain-focused ESG solutions can capture strong growth, as businesses prioritize full value chain accountability. This shift creates new opportunities in sectors like manufacturing, retail, and logistics.
- For instance, Benchmark Gensuite manages ESG and supply chain sustainability reporting for over 1.5 million users, covering 400 enterprises across manufacturing and logistics.
Key Challenges
Data Fragmentation and Standardization Issues
A major challenge in the ESG software market is fragmented and inconsistent data. Companies struggle to align ESG reporting with multiple frameworks such as GRI, SASB, and TCFD, leading to duplication and inefficiencies. Variations in regional regulations further complicate reporting. Inconsistent supplier disclosures and limited access to reliable ESG data add complexity. Vendors must develop solutions that streamline data collection, enable cross-framework reporting, and enhance comparability. Overcoming these issues is critical for ensuring credible ESG insights and achieving scalable adoption across industries.
High Implementation Costs and SME Barriers
The high cost of ESG software adoption creates barriers, especially for small and medium-sized enterprises. Comprehensive platforms require investment in licenses, integration, training, and maintenance, which often exceed SME budgets. While large enterprises can absorb these costs, smaller firms struggle to justify spending amid competing priorities. The lack of tailored, cost-effective solutions restricts SME adoption and slows overall market penetration. Vendors need to address this challenge by offering modular, scalable platforms or subscription-based pricing to make ESG solutions more accessible.
Regional Analysis
North America
North America held the largest share of the ESG software market in 2024, accounting for 38% of total revenue. The region’s dominance is driven by strong regulatory frameworks, including SEC climate disclosure proposals, and significant adoption by large enterprises. U.S.-based corporations are investing heavily in ESG reporting platforms to align with investor demands and sustainability goals. Canada also contributes to growth, particularly with its carbon accounting initiatives and renewable energy transition policies. High penetration of cloud-based ESG solutions and advanced technology infrastructure ensure North America remains a leading market throughout the forecast period.
Europe
Europe accounted for 32% of the ESG software market share in 2024, making it the second-largest region. The European Union leads ESG adoption with binding frameworks such as the Corporate Sustainability Reporting Directive (CSRD) and the EU Taxonomy. These policies mandate detailed ESG disclosures, accelerating adoption across industries. Companies in Germany, France, and the Nordics actively integrate ESG platforms to strengthen compliance, investor relations, and net-zero commitments. The region’s focus on carbon neutrality, supply chain sustainability, and social governance accountability further drives demand. Europe’s mature sustainability ecosystem positions it as a key growth hub for ESG solutions.
Asia-Pacific
Asia-Pacific captured 20% of the ESG software market share in 2024, supported by rapid digital transformation and rising sustainability initiatives. Countries such as Japan, Australia, and China are adopting ESG frameworks to align with global reporting standards. Large enterprises in the region increasingly use ESG platforms to attract foreign investments and strengthen global competitiveness. Regulatory momentum, such as Japan’s corporate governance codes and China’s carbon neutrality pledges, further accelerates adoption. SMEs are also showing growing interest, supported by affordable, cloud-based platforms. Asia-Pacific is projected to be the fastest-growing regional market, driven by regulatory and investor pressures.
Latin America
Latin America represented 6% of the ESG software market share in 2024, with adoption concentrated in Brazil, Mexico, and Chile. Growing regulatory pressure, rising ESG-linked financing, and sustainability initiatives in extractive industries are key drivers. Multinational corporations in the region demand ESG platforms to meet global supply chain and investor requirements. Brazil is advancing climate reporting frameworks, while Mexico and Chile are enhancing corporate governance standards. Limited digital infrastructure in smaller economies poses challenges, yet increased adoption of cloud-based solutions provides opportunities. Regional growth is strongly tied to sustainability in mining, energy, and agriculture sectors.
Middle East & Africa
The Middle East & Africa accounted for 4% of the ESG software market share in 2024, emerging as a developing but strategic region. ESG adoption is accelerating in Gulf Cooperation Council (GCC) countries, driven by diversification agendas and net-zero commitments, particularly in the UAE and Saudi Arabia. South Africa leads in ESG integration within Africa, with growing demand from the mining and energy industries. The region faces challenges in regulatory standardization and data availability, yet rising investor pressure and the need for transparency are driving uptake. Cloud-based ESG platforms are gaining traction as cost-efficient solutions in this market.
Market Segmentations:
By Deployment Mode
- On-Premises
- Cloud
By Type
- ESG Reporting & Disclosure Software
- Carbon Accounting Software
- ESG Data Management Software
- Others
By Organization Size
- Large Enterprises
- Small and Medium Sized Enterprises (SMEs)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the ESG software market is characterized by the presence of leading players such as LogicManager Inc., Enablon SA, Novisto Inc., ESG Enterprise Inc., Intelex Technologies Inc., Nasdaq Inc., IsoMetrix Software (Pty) Ltd, Envizi Pty Ltd, Diligent Corporation, and Benchmark Gensuite Inc. These companies focus on offering advanced ESG reporting, disclosure, and data management solutions to meet the rising demand for compliance, transparency, and sustainability performance. Strategic initiatives such as partnerships, acquisitions, and product innovations remain central to strengthening market positions. Vendors are increasingly integrating AI, automation, and cloud-based models to enhance real-time data analysis and improve user experience. The push for alignment with global frameworks like CSRD, TCFD, and SASB is further driving innovation and competitiveness. Growing demand from both large enterprises and SMEs encourages players to develop scalable, cost-effective platforms, ensuring their relevance in an evolving regulatory and sustainability-driven landscape.
Key Player Analysis
- LogicManager Inc.
- Enablon SA
- Novisto Inc.
- ESG Enterprise Inc.
- Intelex Technologies Inc.
- Nasdaq Inc.
- IsoMetrix Software (Pty) Ltd
- Envizi Pty Ltd
- Diligent Corporation
- Benchmark Gensuite Inc.
Recent Developments
- In 2025, Egnyte / IBM Envizi (via Envizi, now part of IBM) is cited in ESG software comparisons as powering its Sustainability Reporting Manager with support for multiple frameworks (CDP, GRI, IFRS, SASB).
- In 2025, Novisto partnered with Broadridge Financial Solutions to roll out an integrated ESG data management and reporting platform to 500 pilot firms initially.
- In 2025, Novisto said it had nearly tripled its revenue since its Series B round, showing rapid growth in its ESG software adoption.
Report Coverage
The research report offers an in-depth analysis based on Deployment Mode, Type, Organization Size and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The ESG software market will continue to expand rapidly driven by stricter global disclosure regulations.
- Companies will adopt advanced ESG tools to strengthen transparency and investor trust.
- Cloud deployment will remain dominant as enterprises prefer scalability and real-time accessibility.
- AI and automation will enhance predictive insights and streamline reporting processes.
- Supply chain sustainability integration will emerge as a major growth driver.
- Large enterprises will sustain leadership, while SME adoption will grow through affordable platforms.
- Vendors will focus on aligning solutions with evolving global frameworks like CSRD and TCFD.
- Partnerships and acquisitions will intensify as players expand geographic reach and capabilities.
- Europe and North America will remain core markets, while Asia-Pacific records fastest growth.
- Demand for standardized, comparable ESG data will shape innovation and product development strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Regulatory Compliance and Disclosure Mandates
Stricter global regulations such as the EU CSRD and SEC climate disclosure rules require organizations to track, measure, and publish ESG performance, driving widespread adoption of ESG software for structured reporting and compliance.
Rising Investor and Stakeholder Demand
Investors and stakeholders increasingly demand transparent ESG data to assess company resilience and long-term value, prompting companies to adopt ESG platforms to improve ratings, attract green capital, and enhance reputational standing.
Corporate Sustainability and Net-Zero Goals
Ambitious sustainability and net-zero commitments by large enterprises and multinationals are fueling demand for ESG software to measure progress, manage energy usage, and assess supplier sustainability performance.
Integration of AI and Automation
The adoption of AI-driven analytics and automation in ESG software enables predictive insights, real-time tracking, and automated reporting, reducing manual errors and enhancing efficiency for compliance and strategic decision-making.
Expansion of ESG in Supply Chain Management
Growing pressure to monitor supplier practices, carbon intensity, and labor conditions is leading companies to adopt ESG platforms with supply chain sustainability tools, expanding the market into manufacturing, retail, and logistics sectors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for ESG Software market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the ESG Software market projected to grow between 2025 and 2032?
Which ESG Software market segment held the largest share in 2024?
What are the primary factors fueling the growth of the ESG Software market?
Who are the leading companies in the ESG Software market?
Which region commanded the largest share of the ESG Software market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 ESG Reporting & Disclosure Software
- 1.2.2 Carbon Accounting Software
- 1.2.3 ESG Data Management Software
- 1.2.4 Others
- 1.3 By Deployment Mode
- 1.3.1 Cloud
- 1.3.2 On-Premises
- 1.4 By Organization Size
- 1.4.1 Large Enterprises
- 1.4.2 Small and Medium Sized Enterprises (SMEs)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,054.5 million → 2032: USD 4,625.64 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global ESG Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global ESG Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global ESG Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global ESG Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global ESG Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global ESG Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global ESG Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global ESG Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,054.5 million → 2032: USD 4,625.64 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global ESG Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 ESG Reporting & Disclosure Software
- 12.3.6.2 Carbon Accounting Software
- 12.3.6.3 ESG Data Management Software
- 12.3.6.4 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Deployment Mode - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Cloud
- 12.4.6.2 On-Premises
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Organization Size - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Large Enterprises
- 12.5.6.2 Small and Medium Sized Enterprises (SMEs)
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global ESG Software Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global ESG Software Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global ESG Software Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 LogicManager Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Enablon SA
- 17.4 Novisto Inc.
- 17.5 ESG Enterprise Inc.
- 17.6 Intelex Technologies Inc.
- 17.7 Nasdaq Inc.
- 17.8 IsoMetrix Software (Pty) Ltd
- 17.9 Envizi Pty Ltd
- 17.10 Diligent Corporation
- 17.11 Benchmark Gensuite Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

