
Market Overview
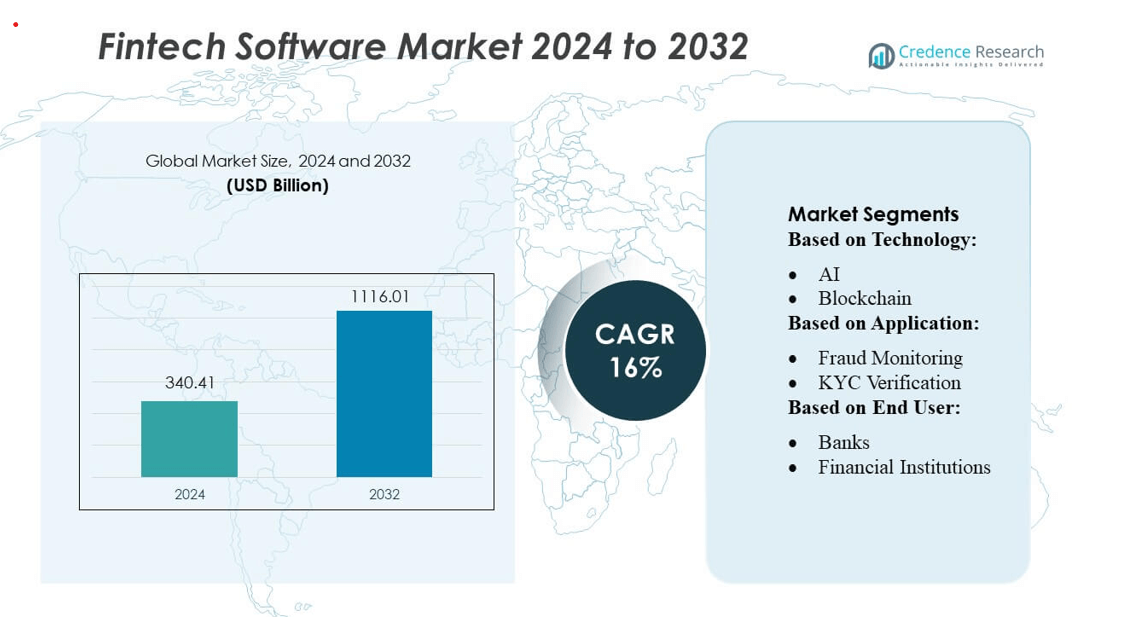
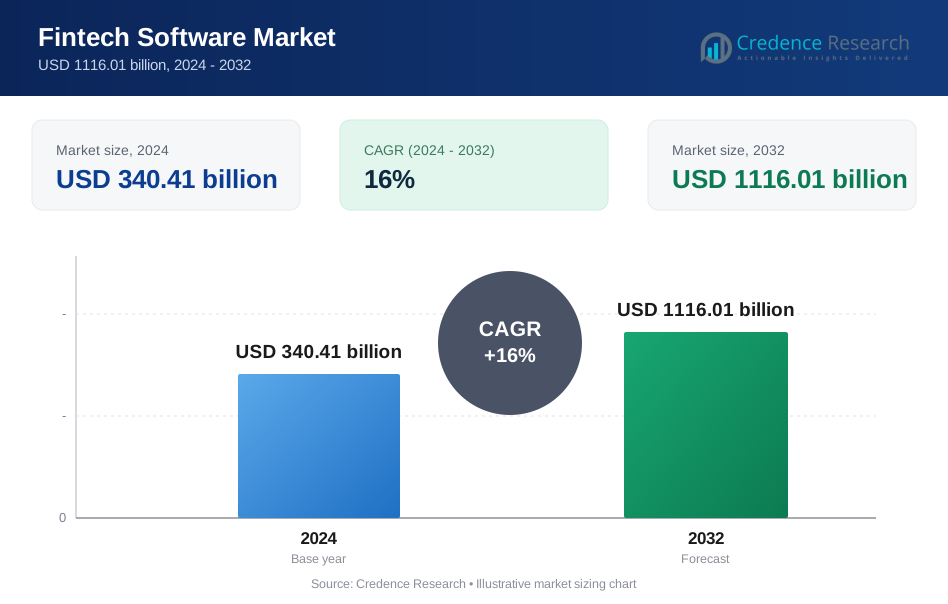
Fintech Software Market size was valued USD 340.41 billion in 2024 and is anticipated to reach USD 1116.01 billion by 2032, at a CAGR of 16% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Fintech Software Market Size 2024 | USD 340.41 billion |
| Fintech Software Market, CAGR | 16% |
| Fintech Software Market Size 2032 | USD 1116.01 billion |
The fintech software market is dominated by leading innovators such as PayPal Holdings, Inc., Mastercard Incorporated, Block, Inc., Upstart Holdings, Inc., Rapyd Financial Network, Railsbank Technology Ltd., Synctera Inc., Braintree, Envestnet, Inc., and Solid Financial Technologies, Inc., which together drive platforms for payments, embedded banking, AI-powered underwriting and infrastructure-as-a-service. These companies continually expand their global footprints through partnerships, API-first architectures, and cloud-native stacks. Regionally, North America leads the market with an estimated 38 % share, leveraging its mature financial ecosystem, strong regulatory support, and advanced technology adoption to sustain dominance.
Market Insights
- The Fintech Software Market, valued at USD 340.41 billion in 2024, is projected to reach USD 1116.01 billion by 2032 at a 16% CAGR, supported by rapid digitization, strong investment flows, and rising enterprise adoption of cloud-based financial solutions.
- Growing demand for real-time payments, embedded finance, and AI-driven credit analytics drives sustained market expansion as organizations prioritize automation, cost efficiency, and integrated financial workflows.
- Market trends highlight the acceleration of open banking, expansion of Banking-as-a-Service models, and increasing deployment of API-first platforms that enhance interoperability across financial ecosystems.
- Competitive intensity remains high as global and emerging players invest in product innovation, cybersecurity, and international partnerships, while regulatory complexities and data-security concerns act as key restraints in several regions.
- North America maintains 38% regional share due to advanced digital infrastructure, while payment software continues to hold the dominant segment share, driven by high transaction volumes and strong merchant adoption.
Market Segmentation Analysis:
By Technology
Artificial Intelligence (AI) dominates the Fintech Software Market technology segment with an estimated over 40% market share, driven by its central role in real-time decision automation, fraud detection, and predictive analytics. AI-powered credit scoring, underwriting automation, and conversational banking significantly enhance operational efficiency and customer engagement. RPA follows with strong adoption in back-office automation, while blockchain gains traction for secure transaction processing and decentralized identity solutions. Overall demand accelerates as financial institutions prioritize intelligent automation, cost reduction, and improved risk management.
- For instance, Solid Financial Technologies’ platform has processed over 11 billion API calls and handled more than 11 billion dollars in transactions, demonstrating the scale and robustness of its AI-powered infrastructure.
By Application
Fraud Monitoring leads the application segment with approximately 45% market share, supported by rising digital transaction volumes and increasingly sophisticated cyber threats. Financial enterprises deploy advanced anomaly-detection engines, AI-driven transaction scoring, and biometric authentication to reduce fraud-related losses. KYC Verification grows rapidly as regulators enforce stricter identity and customer-risk standards, boosting adoption of e-KYC, digital onboarding, and document-verification tools. Compliance & Regulatory Support remains essential as institutions seek automated reporting, AML alert management, and real-time rule-change tracking to maintain regulatory consistency.
- For instance, Rapyd’s Protect solution uses machine-learning models that process risk signals in real time and supports more than 900 payment methods across 100+ countries, allowing it to generate a dynamic risk score that determines automatic approval, manual review, or outright decline.
By End User
Banks hold the dominant position in the end-user segment with more than 50% market share, fueled by large-scale digital transformation initiatives, modernization of core banking systems, and increased adoption of AI and analytics for risk assessment. Financial institutions-including payment providers, lending platforms, and wealth-management firms-expand fintech software usage to enhance customer experience and operational agility. Insurance companies accelerate investment in digital claims handling, automated underwriting, and fraud analytics. The “Others” category, comprising fintech startups and non-bank entities, grows steadily due to rising use of embedded finance solutions.
Key Growth Drivers
Rising Digital Payments and Real-Time Transaction Processing
The rapid expansion of digital payments, fueled by mobile wallets, instant transfers, and contactless transactions, drives strong demand for fintech software. Banks and payment providers deploy real-time processing engines, automated settlement systems, and secure transaction monitoring tools to handle growing volumes. Increasing adoption of ISO 20022 standards and unified payment interfaces further accelerates modernization. As consumers expect seamless, fast, and low-cost payment experiences, enterprises invest heavily in scalable platforms that improve efficiency, minimize downtime, and support cross-border transactions, making payments a major market catalyst.
- For instance, Upstart’s Credit Decision API powers instant, real-time underwriting using more than 2,500 variables per applicant, returning risk-based pricing and term options while estimating probability and timing of default.
Strong Regulatory Push for Compliance Automation
Tightening global regulations in areas such as AML, KYC, data governance, and consumer protection strengthen the need for automated compliance systems. Financial institutions adopt fintech software to streamline identity verification, automate risk scoring, and ensure accurate regulatory reporting. AI-enabled compliance tools reduce manual workloads, minimize false positives, and support real-time rule updates. Regulatory technology (RegTech) integration enables institutions to maintain audit readiness, improve transparency, and prevent financial crime. This ongoing regulatory shift positions compliance automation as a core growth driver for fintech software adoption across markets.
- For instance, Braintree enforces PCI DSS compliance by integrating with SecurityMetrics-its merchants can undergo annual SAQ validation or Level 3/4 assessments via a pre-arranged Qualified Security Assessor.
Growing Integration of AI, Analytics, and Cloud-Native Platforms
Increasing demand for intelligent, data-driven decision-making accelerates deployment of AI, machine learning, and cloud-native fintech solutions. Enterprises leverage predictive analytics for credit scoring, fraud detection, and personalized financial services, enhancing both efficiency and customer experience. Cloud-native architecture reduces operational costs, improves scalability, and enables faster product deployment. The shift toward API-driven ecosystems, open banking frameworks, and microservices further supports innovation. As firms prioritize agility and automation, advanced analytics and cloud integration serve as major enablers of fintech software market growth.
Key Trends & Opportunities
Expansion of Embedded Finance and Banking-as-a-Service (BaaS)
Embedded finance emerges as a major opportunity as non-financial enterprises integrate payment, lending, and insurance capabilities directly into their platforms. Retailers, e-commerce companies, and mobility providers increasingly adopt BaaS solutions to offer seamless financial experiences without building infrastructure from scratch. Fintech software providers benefit from rising demand for API-based onboarding, KYC, and transaction-processing modules. This shift supports new revenue streams for both banks and fintechs, while enabling hyper-personalized financial services. The increasing maturity of open banking accelerates broader adoption of embedded finance models.
- For instance, Railsbank (now Railsr) supports more than 250 B2B customers and has enabled 5.5 million embedded accounts across its platform, allowing brands to deploy financial products such as wallets, cards, and credit using its APIs.
Rapid Growth of Digital Identity, E-KYC, and Authentication Solutions
As digital transactions surge, strong identity verification becomes essential. Fintech software vendors expand capabilities in e-KYC, biometric authentication, document verification, and risk-based scoring. Governments and regulators worldwide promote digital identity frameworks, creating opportunities for compliant verification platforms. Advancements in facial recognition, liveness detection, and AI-driven fraud analytics improve onboarding accuracy and reduce manual review time. This trend supports sectors such as banking, insurance, and digital lending, where fast and secure customer authentication drives competitive differentiation in a high-risk digital environment.
- For instance, Synctera has significantly scaled its BaaS infrastructure in 2024, reconciling 219 billion in transaction volume across more than 80 sources, while automating reconciliation for ~99% of those transactions.
Increasing Adoption of Low-Code/No-Code Fintech Development
Financial institutions embrace low-code and no-code platforms to accelerate product development, reduce IT dependency, and modernize legacy systems. These platforms enable rapid creation of workflows for onboarding, loan processing, and compliance automation. Fintech providers integrate drag-and-drop tools, pre-built templates, and API connectors to support faster innovation. This trend presents an opportunity for software vendors to target mid-size banks and fintech startups seeking cost-efficient digital transformation. As operational agility becomes critical, low-code approaches reshape how financial services design and deploy new digital products.
Key Challenges
Rising Cybersecurity Threats and Data-Privacy Risks
As financial systems become more interconnected, cyberattacks, ransomware incidents, and data breaches pose significant risks. Fintech software must constantly evolve to protect sensitive information across cloud environments, APIs, and digital channels. Institutions face challenges in deploying end-to-end encryption, identity protection, and threat-intelligence systems at scale. Regulatory expectations around data privacy further increase complexity. Balancing innovation with cybersecurity investments remains a major obstacle, particularly for smaller fintech firms with limited resources, making security resilience a core industry challenge.
Integration Issues with Legacy Banking Infrastructure
Many traditional banks continue to operate on outdated core systems, creating major integration barriers for modern fintech software. Legacy architecture often lacks API compatibility, scalability, and real-time processing capabilities, slowing digital transformation efforts. Upgrading or replacing these systems involves high costs, operational risks, and lengthy implementation timelines. As a result, fintech vendors must develop flexible middleware, microservices, and migration tools to bridge old and new environments. Despite growing demand, integration complexity remains a significant challenge that limits rapid adoption of advanced fintech solutions.
Regional Analysis
North America
North America holds the largest share of the Fintech Software Market at around 35%, supported by strong digital adoption, advanced financial infrastructure, and high investment in AI-driven banking platforms. The region benefits from widespread use of mobile banking, real-time payments, and cloud-native financial systems. Regulatory frameworks encouraging open banking and data security also accelerate technological innovation. The presence of major fintech developers, extensive venture capital funding, and rapid integration of API-based services across banks and financial institutions further solidify the region’s leadership in fintech software deployment.
Europe
Europe accounts for approximately 30% of the global market, driven by strong regulatory initiatives such as PSD2 and open banking, which promote interoperability and secure data sharing across financial ecosystems. The region experiences high demand for compliance automation, digital identity verification, and cross-border payments software. Banks and financial institutions increasingly adopt cloud-based platforms and AI-enabled decision systems to enhance operational efficiency. Strong fintech hubs in the UK, Germany, and the Nordics support continuous innovation, while rising digital banking penetration and cybersecurity investments strengthen market expansion.
Asia-Pacific
Asia-Pacific captures around 25% of the fintech software market, supported by rapid digitalization, high mobile-payment adoption, and strong government initiatives promoting cashless economies. Countries such as China, India, and Singapore lead adoption of real-time payments, e-KYC systems, and digital lending platforms. Fintech startups and large technology firms increasingly collaborate with banks to offer embedded finance, AI-powered credit scoring, and blockchain-based transaction tools. Rising financial inclusion efforts and expanding digital infrastructure further accelerate demand, positioning the region as the fastest-growing market for fintech software solutions.
Latin America
Latin America holds roughly 6–7% market share, with growth supported by expanding digital-banking ecosystems, rising smartphone penetration, and a strong shift toward online payments and digital lending. Brazil and Mexico lead regional adoption, driven by fintech-friendly regulations and government-backed instant payment systems. Financial institutions increasingly rely on cloud-based platforms, fraud analytics tools, and digital onboarding software to meet rising consumer expectations. Although infrastructure gaps persist, rapid financial inclusion and growing interest from global fintech investors continue to strengthen opportunities across the region.
Middle East & Africa
The Middle East & Africa region represents around 3–4% of the global market but shows strong growth potential due to accelerating digital transformation and expanding mobile banking usage. Gulf countries lead adoption with investments in blockchain, digital payment platforms, and regulatory technology solutions. African markets experience increasing fintech penetration driven by mobile wallets, digital micro-lending, and identity-verification platforms that support underserved populations. Government initiatives promoting fintech sandboxes and cross-border payment modernization further encourage adoption, positioning the region for steady long-term growth despite infrastructural challenges.
Market Segmentations:
By Technology:
- AI
- Blockchain
By Application:
- Fraud Monitoring
- KYC Verification
By End User:
- Banks
- Financial Institutions
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Fintech Software Market features a diverse competitive landscape led by Solid Financial Technologies, Inc., Rapyd Financial Network, Upstart Holdings, Inc., Braintree, Railsbank Technology Ltd., Block, Inc., Synctera Inc., Envestnet, Inc., Mastercard Incorporated, and PayPal Holdings, Inc. The Fintech Software Market exhibits a highly dynamic and competitive landscape driven by rapid digitalization, convergence of financial services, and continuous innovation in payments, lending, compliance, and infrastructure solutions. Vendors increasingly differentiate through advanced cloud-native architectures, real-time data analytics, and AI-enabled automation that enhance transaction efficiency and risk management. Competition intensifies as companies expand their product portfolios to include embedded finance, API marketplaces, and modular platforms that enable enterprises to integrate financial capabilities at scale. Strategic partnerships, mergers, and global expansion remain critical as firms aim to strengthen regulatory compliance, improve customer experience, and accelerate time-to-market. Additionally, rising demand for secure digital payment systems, cross-border processing, and personalized financial services encourages providers to invest in cybersecurity, fraud prevention, and open banking frameworks. Overall, the market remains characterized by rapid technological evolution and a shift toward interoperable financial ecosystems.
Key Player Analysis
- Solid Financial Technologies, Inc.
- Rapyd Financial Network
- Upstart Holdings, Inc.
- Braintree
- Railsbank Technology Ltd.
- Block, Inc.
- Synctera Inc.
- Envestnet, Inc.
- Mastercard Incorporated
- PayPal Holdings, Inc.
Recent Developments
- In February 2025, Oracle enhanced its supply chain management platform by integrating AI capabilities. This update enables the automation of various tasks for procurement professionals, such as generating standardized product descriptions and providing supplier recommendations, which can significantly streamline procurement processes.
- In January 2025, Block, a technology, announced the launch of Goose, an open-source AI agent designed to empower developers with customizable tools. Goose allows users to leverage various large language models, providing flexibility in its application across different tasks and industries.
- In November 2024, Microsoft unveiled cloud-connected software that enables customers to deploy Azure computing, networking, storage, and application services across various environments, including edge locations, on-premises data centers, and hybrid cloud setups.
- In July 2024, Open Payment Technologies Ltd, a leading provider of fintech solutions, announced the launch of its new digital wallet app, Kuady. Kuady is expected to provide a safe and user-friendly experience to ensure efficient money management.
Report Coverage
The research report offers an in-depth analysis based on Technology, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will adopt more AI-driven automation to enhance credit decisioning, fraud detection, and customer onboarding.
- Open banking frameworks will expand, enabling greater data sharing and fostering new digital financial services.
- Cloud-native fintech platforms will continue to replace legacy systems, improving scalability and operational efficiency.
- Embedded finance will grow as non-financial enterprises integrate payments, lending, and insurance into their offerings.
- Cross-border digital payment solutions will advance, supporting faster, more secure international transactions.
- Regulatory technology adoption will rise as firms strengthen compliance, reporting accuracy, and risk management.
- Blockchain and digital asset infrastructure will gain traction, supporting transparent and secure transaction environments.
- Partnerships between fintechs and traditional financial institutions will increase to accelerate innovation and market reach.
- Cybersecurity investment will intensify to combat sophisticated digital threats and protect customer data.
- Personalized financial services powered by real-time analytics will become more prevalent across consumer and enterprise segments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rapid Expansion of Digital Payments and Real-Time Processing
The surge in mobile wallets, instant transfers, and contactless transactions is driving demand for fintech software that can process high transaction volumes efficiently and securely. Enterprises are investing in scalable, real-time payment engines and unified interfaces to meet consumer expectations for seamless, low-cost, and cross-border payment experiences.
Strong Regulatory Push for Compliance Automation
Increasingly stringent global regulations around AML, KYC, and data governance are compelling financial institutions to adopt automated compliance solutions. Fintech software enables real-time identity verification, risk scoring, and regulatory reporting, reducing manual workloads and ensuring audit readiness.
Integration of AI, Analytics, and Cloud-Native Platforms
Financial institutions are accelerating adoption of AI and cloud-native fintech solutions to enhance credit scoring, fraud detection, and personalized services. These technologies improve operational efficiency, scalability, and enable rapid deployment of new financial products.
Growth of Embedded Finance and Banking-as-a-Service (BaaS)
Non-financial enterprises are integrating financial services directly into their platforms, creating new revenue streams and customer touchpoints. Fintech software providers benefit from rising demand for API-based onboarding, KYC, and transaction modules that support embedded finance and BaaS models.
Rising Need for Advanced Fraud Monitoring and Digital Identity Solutions
As digital transaction volumes grow, so do cyber threats and fraud risks. Financial enterprises are deploying AI-driven anomaly detection, biometric authentication, and e-KYC tools to reduce fraud-related losses and ensure secure, compliant onboarding.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Fintech Software Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Fintech Software Market projected to grow between 2025 and 2032?
Who are the major players in The Fintech Software Market ?
What are the major market drivers of The Fintech Software Market ?
What are the major market restraints of The Fintech Software Market ?
What are the major market opportunities of The Fintech Software Market ?
What is the end-user type of The Fintech Software Market ?
What is the significant technology segment of The Fintech Software Market ?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Banks
- 1.2.2 Financial Institutions
- 1.2.3 Insurance Companies
- 1.2.4 Fintech Startups & Non-Bank Entities
- 1.3 By Technology
- 1.3.1 Artificial Intelligence (AI)
- 1.3.2 Blockchain
- 1.3.3 Robotic Process Automation (RPA)
- 1.3.4 Cloud-Native Platforms
- 1.4 By Application
- 1.4.1 Fraud Monitoring
- 1.4.2 KYC Verification
- 1.4.3 Compliance & Regulatory Support
- 1.4.4 Digital Payments
- 1.4.5 Lending & Credit Scoring
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 340.41 billion → 2032: USD 1116.01 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Fintech Software Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Fintech Software Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Fintech Software Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Fintech Software Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Fintech Software Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Fintech Software Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Fintech Software Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Fintech Software Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 340.41 billion → 2032: USD 1116.01 billion)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Fintech Software Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Banks
- 12.3.6.2 Financial Institutions
- 12.3.6.3 Insurance Companies
- 12.3.6.4 Fintech Startups & Non-Bank Entities
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Artificial Intelligence (AI)
- 12.4.6.2 Blockchain
- 12.4.6.3 Robotic Process Automation (RPA)
- 12.4.6.4 Cloud-Native Platforms
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Fraud Monitoring
- 12.5.6.2 KYC Verification
- 12.5.6.3 Compliance & Regulatory Support
- 12.5.6.4 Digital Payments
- 12.5.6.5 Lending & Credit Scoring
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Fintech Software End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Fintech Software Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Fintech Software Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Fintech Software Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 PayPal Holdings, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Mastercard Incorporated
- 18.4 Block, Inc.
- 18.5 Upstart Holdings, Inc.
- 18.6 Rapyd Financial Network
- 18.7 Railsbank Technology Ltd.
- 18.8 Synctera Inc.
- 18.9 Braintree
- 18.10 Envestnet, Inc.
- 18.11 Solid Financial Technologies, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

