
Market Overview
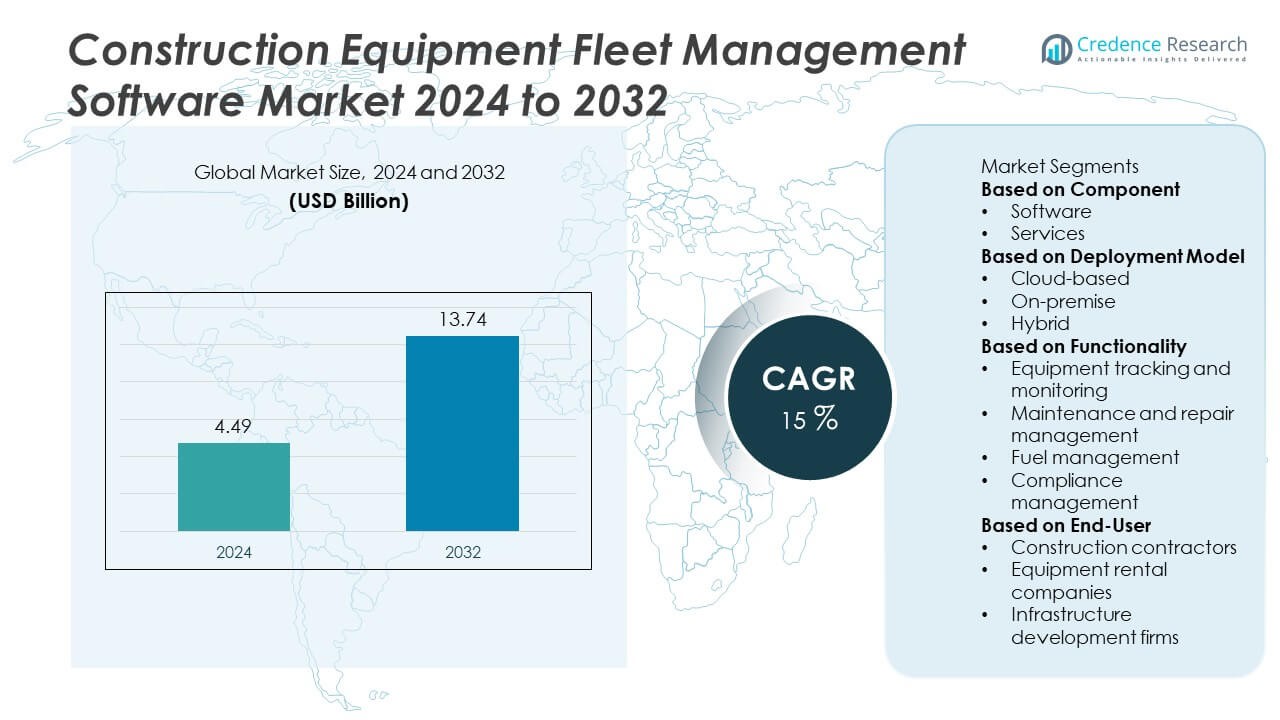
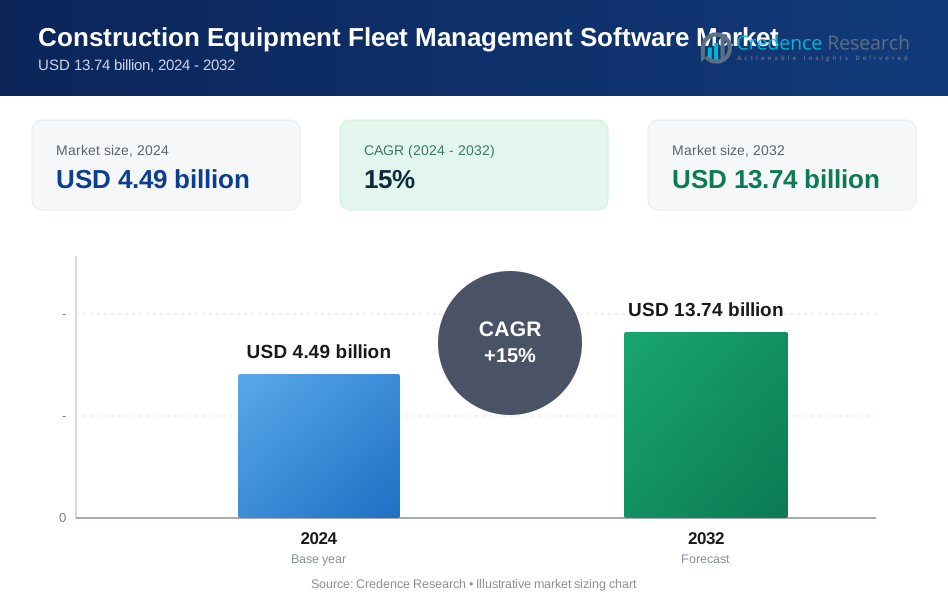
The Construction Equipment Fleet Management Software Market was valued at USD 4.49 billion in 2024 and is projected to reach USD 13.74 billion by 2032, expanding at a CAGR of 15% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Construction Equipment Fleet Management Software Market Size 2024 | USD 4.49 Billion |
| Construction Equipment Fleet Management Software Market, CAGR | 15% |
| Construction Equipment Fleet Management Software Market Size 2032 | USD 13.74 Billion |
The Construction Equipment Fleet Management Software market is led by prominent players such as Trimble, Caterpillar, Komatsu, John Deere, Hitachi Construction Machinery, Topcon Positioning Systems, Volvo Construction Equipment, Samsara, Teletrac Navman, and Zebra Technologies. These companies dominate through integrated telematics platforms, IoT-based analytics, and cloud-driven asset management solutions that enhance operational visibility and equipment utilization. North America led the market with a 36% share in 2024, supported by rapid adoption of digital construction technologies and strong investment in infrastructure modernization. Europe followed with 27%, driven by fleet optimization needs and sustainability goals, while Asia-Pacific, holding 30%, witnessed accelerated growth from large-scale construction and smart city projects.
Market Insights
- The construction equipment fleet management software market was valued at USD 4.49 billion in 2024 and is projected to reach USD 13.74 billion by 2032, growing at a CAGR of 15% during the forecast period.
- Market growth is driven by rising demand for real-time fleet tracking, predictive maintenance, and automation to enhance productivity and minimize equipment downtime.
- Key trends include increasing adoption of IoT, AI, and cloud-based analytics platforms for remote monitoring, asset optimization, and sustainability compliance across construction fleets.
- The market is competitive, with major players such as Trimble, Caterpillar, Komatsu, and John Deere focusing on digital integration, data analytics, and telematics-based solutions to strengthen global presence.
- North America led the market with a 36% share in 2024, followed by Asia-Pacific with 30% and Europe with 27%, while the software segment dominated with a 64% share due to higher deployment in large-scale equipment management systems.
Market Segmentation Analysis:
By Component
The software segment dominated the construction equipment fleet management software market in 2024, accounting for a 65% share. This dominance stems from the rising integration of telematics, GPS tracking, and IoT-based analytics in fleet operations. Software solutions provide real-time visibility into asset location, fuel consumption, and equipment performance, enabling data-driven decision-making. Increasing adoption of AI and cloud technologies enhances predictive maintenance and reduces operational downtime. The demand for centralized fleet management platforms among construction companies continues to drive segment expansion, as they help optimize utilization and ensure higher productivity.
- For instance, Caterpillar Inc. integrated VisionLink across its fleet management ecosystem, processing machine data points for performance analytics. VisionLink provides key insights to maximize performance, monitor fleets, and optimize utilization.
By Deployment Model
The cloud-based segment led the market with a 59% share in 2024, driven by its scalability, cost efficiency, and easy accessibility across multiple job sites. Cloud deployment enables seamless data synchronization, remote monitoring, and real-time reporting for construction companies managing large fleets. Contractors increasingly prefer subscription-based cloud platforms to reduce IT overhead and improve data security. The growing use of mobile applications and remote operations management further strengthens this segment. Continuous advancements in cloud computing and SaaS-based fleet solutions are expected to fuel sustained adoption across global construction markets.
- For instance, Samsara Inc. connected more than 2.3 million IoT devices to its unified cloud fleet management platform, enabling real-time tracking and predictive diagnostics for construction equipment.
By Functionality
The equipment tracking and monitoring segment held the largest share of 42% in 2024, supported by increasing demand for real-time visibility and performance optimization. Advanced telematics and IoT sensors allow operators to track asset location, utilization rates, and operational health. This functionality minimizes idle time, prevents theft, and improves project scheduling accuracy. Construction firms are deploying intelligent tracking systems to manage dispersed fleets efficiently and reduce unplanned maintenance. Integration with AI-based analytics further enhances operational control, enabling proactive decision-making and extending equipment lifespan across large-scale infrastructure and commercial projects.
Key Growth Drivers
Rising Demand for Equipment Utilization and Cost Optimization
Construction companies are increasingly adopting fleet management software to enhance equipment utilization and reduce idle time. These platforms help track machine performance, fuel efficiency, and maintenance schedules in real time, lowering operational costs. The growing focus on maximizing return on assets (ROA) and minimizing downtime is driving adoption across infrastructure and heavy construction projects. Advanced analytics and telematics integration are further supporting efficient resource allocation, ensuring higher productivity and profitability in large-scale fleet operations.
- For instance, John Deere's JDLink™ telematics platform monitors over 500,000 connected machines and offers tools and data to improve uptime and reduce maintenance costs.
Expansion of Smart Construction and IoT Integration
The integration of IoT and telematics technologies is a major growth driver in the construction equipment fleet management software market. Connected sensors enable real-time monitoring of equipment health, location, and environmental conditions. These data insights support predictive maintenance and help reduce mechanical failures. Construction firms are using IoT-driven platforms to streamline communication between operators and site managers. The ongoing shift toward smart construction ecosystems enhances safety, reliability, and operational transparency, strengthening market adoption globally.
- For instance, Trimble Inc. operates a connected ecosystem with over 1.3 million active devices, using GNSS and IoT sensors to deliver centimeter-level precision in fleet positioning and performance tracking.
Regulatory Push for Safety and Compliance
Increasing government regulations related to worker safety, emissions, and equipment maintenance are promoting the adoption of fleet management software. Compliance management modules help track certifications, inspections, and operational logs, ensuring adherence to safety standards. Construction companies rely on digital systems to automate compliance reporting and prevent violations. The need to meet evolving environmental and operational regulations across regions like North America and Europe continues to drive demand for integrated and compliant fleet management solutions.
Key Trends & Opportunities
Adoption of AI and Predictive Maintenance Solutions
AI-based predictive maintenance is transforming fleet management by enabling early detection of performance anomalies. Machine learning algorithms analyze sensor data to predict failures before they occur, reducing downtime and repair costs. This trend is gaining traction among large construction firms managing multiple heavy equipment fleets. Integration of predictive tools with telematics platforms enhances decision-making, boosts operational efficiency, and extends machinery lifespan. Companies investing in AI-driven solutions are improving fleet reliability while reducing total ownership costs.
- For instance, Komatsu Ltd.'s KOMTRAX system uses predictive analytics and real-time data to anticipate maintenance needs, aiming to reduce unscheduled maintenance across connected fleets. This strategy helps optimize maintenance schedules and improve machine uptime.
Cloud-Based and Mobile Fleet Management Expansion
The growing shift toward cloud-based and mobile-enabled fleet management platforms is creating new opportunities for remote operations. Cloud deployment allows real-time data sharing across construction sites and headquarters, improving collaboration. Mobile apps enhance accessibility by enabling field managers to monitor and control equipment from any location. This flexibility is particularly beneficial for multi-site contractors. As construction projects become more geographically dispersed, the demand for mobile-friendly and scalable fleet management software continues to accelerate globally.
- For instance, Topcon Positioning Systems developed its MAGNET Construct mobile application for Android and iOS handheld devices to enable remote site coordination, graphical-based layout, and asset mapping for construction projects.
Key Challenges
High Implementation and Integration Costs
The initial investment for advanced fleet management systems remains a major barrier, especially for small and medium-sized contractors. Costs include software licensing, IoT sensor installation, and integration with existing enterprise systems. In addition, ongoing maintenance and data analytics services increase total expenditure. While the long-term benefits are significant, the short-term financial burden slows adoption in cost-sensitive regions. Vendors are addressing this challenge by introducing modular and subscription-based models to improve affordability and accessibility.
Data Security and Connectivity Concerns
The reliance on cloud and IoT platforms increases vulnerability to cyber threats and data breaches. Construction firms store sensitive operational data, including equipment usage patterns and project timelines, which require secure transmission and storage. Weak network infrastructure in remote construction areas can also disrupt data flow and reduce system reliability. Addressing cybersecurity and connectivity challenges through advanced encryption, secured networks, and reliable connectivity solutions is essential for maintaining user trust and ensuring uninterrupted operations.
Regional Analysis
North America
North America held a 35% share of the construction equipment fleet management software market in 2024, driven by strong digital adoption across infrastructure and commercial construction projects. The United States leads the region due to widespread use of IoT, telematics, and AI-based asset management platforms. Government initiatives promoting smart construction and sustainable infrastructure further enhance demand. The presence of key players offering advanced analytics and compliance tools supports regional growth. Rising investments in predictive maintenance systems and cloud-based deployment models continue to strengthen North America’s leadership in technology-driven fleet operations.
Europe
Europe accounted for 27% of the global market in 2024, fueled by stringent regulations on equipment safety, emissions, and operational compliance. Countries such as Germany, France, and the U.K. are at the forefront of adopting digital fleet management platforms. The region’s focus on automation, sustainability, and operational transparency supports software adoption in large-scale infrastructure projects. Cloud-based solutions are gaining traction among equipment rental firms and contractors seeking real-time monitoring and regulatory alignment. The growing emphasis on lifecycle management and predictive analytics is accelerating the digital transformation of Europe’s construction ecosystem.
Asia-Pacific
Asia-Pacific dominated the construction equipment fleet management software market with a 30% share in 2024, driven by rapid urbanization, industrialization, and infrastructure expansion in China, India, and Japan. The region’s growing construction activities and government-led smart city initiatives are spurring adoption of digital fleet monitoring systems. Local contractors increasingly prefer cloud-based and mobile-enabled platforms to enhance equipment visibility and productivity. Investments in IoT-enabled machinery and data analytics tools are rising as firms aim to improve cost efficiency and reduce downtime. Expanding manufacturing bases and technology integration continue to position Asia-Pacific as the fastest-growing regional market.
Middle East & Africa
The Middle East & Africa region captured a 5% share in 2024, supported by growing infrastructure, oil and gas, and construction projects in Saudi Arabia, the UAE, and South Africa. Major government initiatives such as Saudi Vision 2030 are driving digital transformation and the integration of smart fleet management systems. Harsh working conditions and remote project locations are increasing reliance on predictive maintenance and equipment tracking solutions. Vendors are focusing on providing tailored cloud-based software to improve asset utilization. The region’s rising focus on operational efficiency and sustainability is gradually boosting adoption of advanced fleet management platforms.
South America
South America held a 3% share of the market in 2024, led by Brazil, Chile, and Argentina, where infrastructure development and mining activities are expanding. Construction companies in the region are increasingly adopting digital tools to monitor equipment performance and minimize downtime. Growing partnerships between global software vendors and local contractors are enhancing awareness and accessibility. Economic recovery and government investment in public infrastructure are further driving adoption. However, challenges such as limited internet connectivity and budget constraints persist, slowing widespread implementation of advanced fleet management systems across smaller enterprises.
Market Segmentations:
By Component
- Software
- Services
By Deployment Model
- Cloud-based
- On-premise
- Hybrid
By Functionality
- Equipment tracking and monitoring
- Maintenance and repair management
- Fuel management
- Compliance management
By End-User
- Construction contractors
- Equipment rental companies
- Infrastructure development firms
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Construction Equipment Fleet Management Software market includes major players such as Trimble, Hitachi Construction Machinery, Caterpillar, Topcon Positioning Systems, Volvo Construction Equipment, Komatsu, Zebra Technologies, John Deere, Samsara, and Teletrac Navman. These companies are leading innovation through advanced telematics, IoT integration, and predictive analytics solutions that enhance equipment efficiency and reduce downtime. Market leaders are focusing on cloud-based platforms offering real-time tracking, maintenance alerts, and performance analytics. Strategic collaborations with construction firms and equipment OEMs are expanding product reach globally. Continuous investment in AI-driven analytics, remote diagnostics, and data-driven decision tools is strengthening competitive differentiation. Moreover, regional expansion, scalable SaaS offerings, and user-friendly interfaces are central to maintaining market dominance. The competition remains intense as vendors prioritize automation, cost optimization, and fleet visibility to cater to growing demands in large-scale infrastructure and smart construction projects worldwide.
Key Player Analysis
- Trimble
- Hitachi Construction Machinery
- Caterpillar
- Topcon Positioning Systems
- Volvo Construction Equipment
- Komatsu
- Zebra Technologies
- John Deere
- Samsara
- Teletrac Navman
Recent Developments
- In April 2025, Hitachi Construction Machinery launched LANDCROS Connect, a mixed-brand fleet platform that manages non-Hitachi machines from one dashboard.
- In February 2025, Trimble released FieldLink v2025.1.0 with new inspection and layout reporting to tighten field-to-office workflows used alongside connected machine control fleets.
- In September 2024, Continental Tire added onto their ContiConnect fleet management software by releasing two new versions, ContiConnect Lite and ContiConnect Pro. This modification intends to offer specific and customer-centric options for fleet managers to ensure efficient and sustainable practice in their tire maintenance.
- In August 2024, Align Technologies reported the acquisition of FleetWatcher, a significant company who specializes in fleet and material management software systems for heavy civil construction. This initiative is meant to strengthen the operating capabilities for Align’s customers by consolidating tools, equipment, fleet, and materials management in a single system.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment Model, Functionality, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand rapidly as construction firms prioritize digital fleet management solutions.
- Cloud-based platforms will dominate due to scalability, real-time access, and lower IT costs.
- Predictive analytics and AI will enhance maintenance scheduling and equipment performance.
- Integration with IoT and telematics will improve fleet visibility and operational efficiency.
- Data-driven insights will drive fuel optimization and emissions reduction initiatives.
- North America will remain a leading region supported by advanced digital infrastructure.
- Asia-Pacific will witness the fastest growth driven by urbanization and infrastructure investments.
- Partnerships between software developers and OEMs will boost integrated fleet ecosystems.
- Cybersecurity and data privacy measures will become key priorities for solution providers.
- Continuous innovation in automation and machine learning will define the market’s competitive edge
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Construction Equipment Fleet Management Software market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Construction Equipment Fleet Management Software market projected to grow between 2025 and 2032?
Which Construction Equipment Fleet Management Software market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Construction Equipment Fleet Management Software market?
Who are the leading companies in the Construction Equipment Fleet Management Software market?
Which region commanded the largest share of the Construction Equipment Fleet Management Software market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Construction Equipment Fleet Management Software Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Construction Equipment Fleet Management Software Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4.49 billion → 2032: USD 13.74 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Construction Equipment Fleet Management Software Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Construction Equipment Fleet Management Software Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Construction Equipment Fleet Management Software Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Construction Equipment Fleet Management Software Market Drivers
- 3.3 Construction Equipment Fleet Management Software Market Restraints & Challenges
- 3.4 Construction Equipment Fleet Management Software Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Construction Equipment Fleet Management Software Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Construction Equipment Fleet Management Software Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Construction Equipment Fleet Management Software category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Construction Equipment Fleet Management Software Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Construction Equipment Fleet Management Software Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Construction Equipment Fleet Management Software market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Construction Equipment Fleet Management Software Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Construction Equipment Fleet Management Software Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Construction Equipment Fleet Management Software Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Construction Equipment Fleet Management Software (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Construction Equipment Fleet Management Software Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Construction Equipment Fleet Management Software Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Construction Equipment Fleet Management Software Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Construction Equipment Fleet Management Software Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Construction Equipment Fleet Management Software Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Construction Equipment Fleet Management Software Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Construction Equipment Fleet Management Software Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Construction Equipment Fleet Management Software Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Construction Equipment Fleet Management Software Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
