
Market Overview:
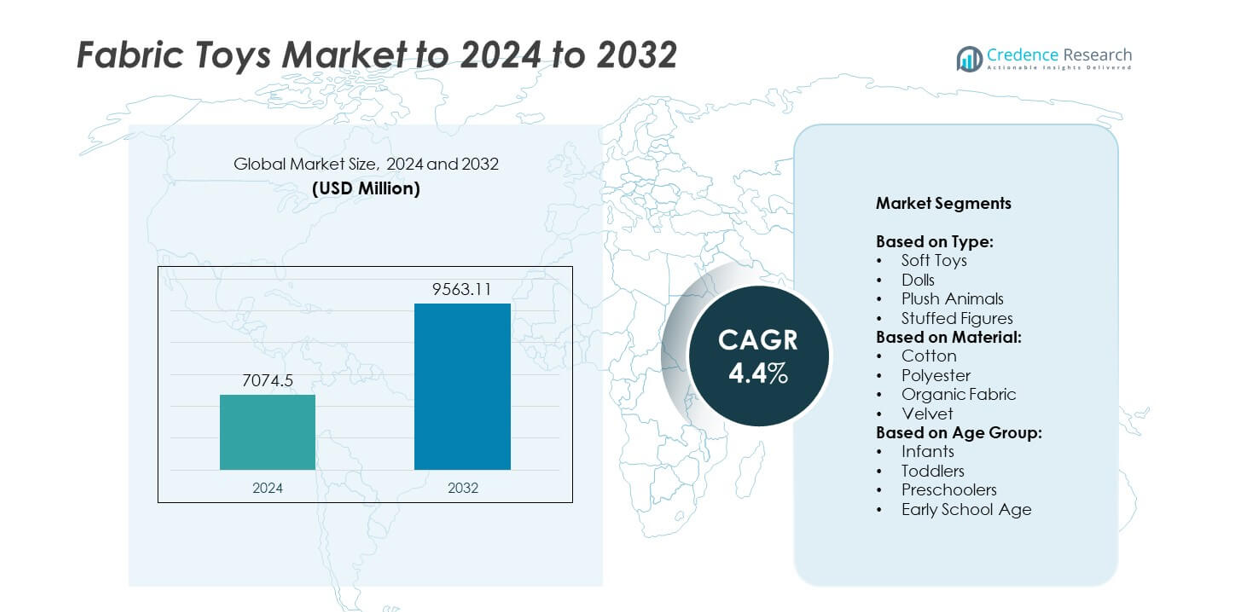
Fabric Toys market size was valued at USD 7074.5 million in 2024 and is anticipated to reach USD 9563.11 million by 2032, at a CAGR of 4.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Fabric Toys Market Size 2024 | USD 7074.5 million |
| Fabric Toys Market, CAGR | 4.4% |
| Fabric Toys Market Size 2032 | USD 9563.11 million |
The fabric toys market is shaped by leading players such as Cloud b, Spin Master, Gund, Melissa and Doug, Aurora World, Hasbro, Jellycat, Folkmanis, Ty Inc., Snoozies, Mattel, North American Bear Co., MGA Entertainment, Sassy, VTech, and Kidoozie. These companies focus on innovation, character licensing, eco-friendly materials, and expanding online retail channels to strengthen their competitive positions. Regional analysis shows that North America led the market in 2024, holding 32% share, driven by high consumer spending, strong retail infrastructure, and demand for sustainable and licensed products. Europe followed with 28% share, supported by strict safety standards and preference for eco-conscious toys, while Asia Pacific accounted for 25%, fueled by rising disposable incomes and production hubs.
Market Insights
- The fabric toys market size reached USD 7074.5 million in 2024 and is expected to reach USD 9563.11 million by 2032, growing at a CAGR of 4.4%.
- Rising demand for developmental and educational toys, along with growing parental focus on safe and sensory play, is fueling consistent growth across product categories, with soft toys leading at over 35% share in 2024.
- Key trends include increasing adoption of sustainable fabrics such as organic cotton and recycled polyester, along with growing interest in licensed and character-based toys linked to global entertainment franchises.
- The competitive landscape is shaped by global leaders and niche manufacturers emphasizing eco-friendly innovations, customization, and e-commerce expansion, while facing challenges from local low-cost producers and strict safety compliance costs.
- North America led with 32% share in 2024, followed by Europe at 28% and Asia Pacific at 25%, while Latin America and Middle East & Africa accounted for smaller but steadily growing shares.
Market Segmentation Analysis:
By Type
Soft toys dominated the fabric toys market in 2024, capturing over 35% of the share. Their popularity stems from wide appeal across age groups and strong gifting demand. Plush animals follow closely, driven by themed collections and licensed characters from entertainment franchises. Dolls maintain steady growth supported by cultural traditions and interactive play features. Stuffed figures are expanding due to demand for customized and character-based designs. The dominance of soft toys reflects their versatility, emotional connection for children, and increasing product innovations such as washable and hypoallergenic fabrics.
- For instance, As of August 2024, Jazwares’ Squishmallows brand had sold over 400 million units across more than 3,000 unique styles.
By Material
Polyester emerged as the leading material segment, accounting for more than 40% of the fabric toys market in 2024. Its durability, affordability, and ease of mass production make it highly preferred by manufacturers. Cotton ranks second, benefiting from its natural feel and safety appeal for infants and toddlers. Organic fabrics are witnessing rising adoption, driven by eco-conscious parents seeking non-toxic, sustainable options. Velvet remains a niche but growing material due to its premium texture and demand in collectible toys. Polyester dominance is fueled by scalability and broad acceptance across global markets.
- For instance, Paramount reports ~100,000 PAW Patrol products in market across categories, underscoring preschool pull.
By Age Group
Toddlers represented the dominant age group in the fabric toys market, securing over 38% of total share in 2024. This segment benefits from strong parental spending on developmental toys that enhance sensory skills and comfort. Infants contribute significantly, as soft and plush designs meet safety and soothing needs. Preschoolers show consistent adoption due to role-play and learning-focused toys, while early school-age children engage with themed and collectible stuffed figures. The leading toddler segment reflects high replacement cycles, gifting occasions, and demand for safe, washable, and engaging fabric-based play products.
Key Growth Drivers
Rising Demand for Educational and Developmental Toys
The growing emphasis on early childhood learning strongly drives the fabric toys market. Parents and educators increasingly prefer toys that stimulate cognitive, sensory, and emotional development. Soft toys, dolls, and plush animals support imaginative play, language development, and motor skills. Rising disposable incomes in emerging economies further encourage higher spending on interactive and safe toys. The demand for fabric toys as both comforting companions and learning tools ensures their steady adoption, making this the key growth driver shaping global market expansion.
- For instance, Keel Toys' Keeleco range is made from 100% recycled plastic waste, with the number of bottles used varying by product size.
Growing Popularity of Licensed and Character-Based Products
Licensed fabric toys tied to movies, cartoons, and gaming franchises are fueling sales globally. Children’s fascination with characters such as superheroes, animated animals, and fantasy figures has significantly boosted demand for branded plush animals and stuffed figures. Manufacturers collaborate with entertainment companies to create exclusive collections that enhance brand value. These products also enjoy strong gifting appeal and collectability among both children and adults. The increasing influence of pop culture ensures continued momentum for licensed toys, reinforcing brand loyalty and driving repeat purchases.
- For instance, the Ty Inc. Beanie Boos line features over 600 distinct items
Expansion of Sustainable and Eco-Friendly Materials
Sustainability has become a critical driver as parents prioritize safe, non-toxic, and eco-friendly products. The use of organic fabrics, cotton, and recycled polyester in fabric toys is rising sharply. Regulatory frameworks promoting sustainable materials also push manufacturers to shift toward eco-conscious production. Brands adopting biodegradable packaging and recyclable textiles attract environmentally aware consumers. This transition is especially prominent in developed markets such as Europe and North America, where sustainability strongly influences purchasing decisions. The expansion of eco-friendly toys opens long-term growth opportunities for ethical brands.
Key Trends & Opportunities
Customization and Personalization of Toys
A major trend shaping the fabric toys market is customization, where consumers seek personalized products for gifting and emotional connection. Parents often prefer toys embroidered with names or tailored designs reflecting children’s interests. E-commerce platforms support this trend by offering easy customization options and direct-to-consumer models. Personalized plush animals, dolls, and soft toys enhance attachment and increase consumer loyalty. The shift toward bespoke toys not only adds premium value but also creates opportunities for niche players and startups to differentiate their offerings in competitive markets.
- For instance, Budsies states it has produced over 200,000 custom plush designs for customers worldwide.
Digital Integration and Interactive Features
The integration of technology into fabric toys is opening fresh opportunities. Interactive toys embedded with sound chips, sensors, or augmented reality features provide immersive play experiences. Parents increasingly adopt smart toys that combine traditional fabric comfort with modern digital engagement. These innovations appeal to tech-savvy families and align with the rising preference for multi-sensory learning tools. Companies are investing in safe, durable, and washable digital fabric toys to ensure practicality. This trend is expected to grow as digital-native children demand engaging and interactive play products.
- For instance, Hasbro’s 2023 Furby features 5 voice-activated modes and 600+ phrases/songs in a plush form factor.
Key Challenges
Safety Regulations and Compliance Costs
Strict safety standards present a major challenge for the fabric toys market. Regulations require toys to be free from toxic dyes, small detachable parts, and hazardous chemicals. Meeting these standards increases production costs and limits the use of cheaper materials. Frequent recalls due to safety violations can damage brand reputation and reduce consumer trust. Smaller manufacturers face difficulty in sustaining compliance expenses, leading to competitive disadvantages. As authorities continue tightening regulations, manufacturers must balance innovation and affordability while maintaining strict adherence to global safety norms.
Intense Competition and Price Pressure
The fabric toys market faces intense competition from both global brands and regional manufacturers. Local producers often compete on price, offering lower-cost alternatives to branded products. This exerts strong pricing pressure on established players, reducing profit margins. Additionally, the availability of counterfeit licensed toys threatens market credibility. Consumers in price-sensitive markets may opt for cheaper options despite quality concerns. Companies are forced to focus on differentiation through sustainability, innovation, and branding to maintain competitive advantage, but this requires high investment and marketing efforts.
Regional Analysis
North America
North America held the largest share of the fabric toys market in 2024, accounting for 32%. Strong consumer spending, high demand for licensed character toys, and a mature retail infrastructure support regional dominance. The U.S. leads with extensive product innovation and collaborations with global entertainment brands. Rising awareness of eco-friendly materials also drives adoption of organic and sustainable toys. Canada contributes steadily, with growing interest in educational and sensory toys for toddlers. The established distribution networks across online and offline channels further enhance accessibility, reinforcing North America’s leadership in the global fabric toys market.
Europe
Europe captured 28% of the fabric toys market in 2024, supported by strong demand for sustainable and ethically produced toys. Countries such as Germany, France, and the UK lead adoption due to strict safety regulations and consumer preference for eco-friendly materials. Educational toys tailored to developmental needs also gain traction, reflecting the region’s emphasis on child learning. Licensed toys inspired by European entertainment franchises further fuel sales. The popularity of premium-quality toys among middle- and high-income families strengthens market presence. E-commerce expansion and gifting culture during holidays provide an additional boost to Europe’s position.
Asia Pacific
Asia Pacific accounted for 25% of the fabric toys market in 2024, driven by rapid urbanization and rising disposable incomes. China dominates production and consumption, supported by cost-efficient manufacturing hubs and strong domestic demand. India shows robust growth with increasing middle-class spending on educational and sensory toys. Japan and South Korea contribute through premium character-based toys tied to popular media franchises. Growing awareness of child development and safety standards is pushing demand for quality fabric toys. Expanding e-commerce platforms and affordable product ranges further support Asia Pacific’s growth, positioning it as a fast-evolving regional market.
Latin America
Latin America represented 9% of the fabric toys market in 2024, with Brazil and Mexico driving regional growth. Rising birth rates and increasing parental focus on developmental play support demand. Licensed toys connected to global and regional entertainment franchises remain popular among children. However, economic fluctuations and price sensitivity influence purchasing behavior, pushing preference for affordable options. Online platforms are expanding their role in distribution, offering wider access to diverse product ranges. Growing awareness of child safety and the introduction of organic materials are also encouraging higher-quality purchases in Latin American markets.
Middle East and Africa
The Middle East and Africa held 6% of the fabric toys market in 2024, reflecting steady but smaller-scale growth. Urban centers such as the UAE and South Africa show rising demand, supported by expanding retail infrastructure and a growing young population. High preference for plush animals and soft toys as gifting items enhances sales. However, limited awareness of eco-friendly and educational toys restrains broader adoption. Economic disparity across regions creates uneven market penetration, with premium toys mainly restricted to high-income groups. Gradual improvements in e-commerce and retail channels are expected to support future expansion.
Market Segmentations:
By Type:
- Soft Toys
- Dolls
- Plush Animals
- Stuffed Figures
By Material:
- Cotton
- Polyester
- Organic Fabric
- Velvet
By Age Group:
- Infants
- Toddlers
- Preschoolers
- Early School Age
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Cloud b, Spin Master, Gund, Melissa and Doug, Aurora World, Hasbro, Jellycat, Folkmanis, Ty Inc., Snoozies, Mattel, North American Bear Co., MGA Entertainment, Sassy, VTech, and Kidoozie are among the prominent companies shaping the competitive landscape of the fabric toys market. The industry is characterized by a blend of global leaders and niche specialists competing across product innovation, sustainability, and licensed character partnerships. Companies focus heavily on integrating eco-friendly materials, enhancing safety standards, and expanding customization options to attract environmentally conscious and value-driven consumers. The rise of online retail channels has intensified competition, with firms leveraging e-commerce to extend their global reach and offer direct-to-consumer models. Collaborations with entertainment franchises remain a critical strategy, ensuring consistent demand through character-driven toys. Market rivalry is further heightened by regional manufacturers offering low-cost alternatives, pushing established players to differentiate through quality, brand reputation, and innovation-driven product portfolios.
Key Player Analysis
- Cloud b
- Spin Master
- Gund
- Melissa and Doug
- Aurora World
- Hasbro
- Jellycat
- Folkmanis
- Ty Inc.
- Snoozies
- Mattel
- North American Bear Co.
- MGA Entertainment
- Sassy
- VTech
- Kidoozie
Recent Developments
- In 2025, GUND introduced an updated Muttsy plush as part of its new Forever Friends line and Forever Friends Promise initiative. The updated plush is softer, features new red heart stitching on its paw pads, and comes with a scannable tag that provides special benefits
- In January 2024, Spin Master completed its acquisition of Melissa & Doug, a move positioned to drive innovation and growth in the toy industry.
- In 2023, Ty Inc. launched a special edition gold beanie baby teddy bear named Aloha
Report Coverage
The research report offers an in-depth analysis based on Type, Material, Age Group and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The fabric toys market will expand steadily with growing demand for developmental play products.
- Sustainability will shape consumer preferences, boosting adoption of organic and eco-friendly materials.
- Licensed and character-based toys will continue driving brand collaborations and premium sales.
- Digital integration in plush and soft toys will enhance interactive learning experiences.
- E-commerce platforms will strengthen distribution, offering customization and wider global reach.
- Emerging markets will witness faster growth due to rising disposable incomes and urbanization.
- Safety regulations will push manufacturers to invest in high-quality, compliant production processes.
- Personalization trends will create premium opportunities in gifting and niche toy categories.
- Competition will intensify, with companies focusing on innovation and brand differentiation.
- Educational toys will remain central to market growth, appealing to parents worldwide.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Fabric Toys Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Fabric Toys Market projected to grow between 2025 and 2032?
Which Fabric Toys Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Fabric Toys Market?
Who are the leading companies in the Fabric Toys Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7074.5 million → 2032: USD 9563.11 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Fabric Toys Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Fabric Toys Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Fabric Toys Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Fabric Toys Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Fabric Toys Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Fabric Toys Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Fabric Toys Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Fabric Toys Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7074.5 million → 2032: USD 9563.11 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Fabric Toys Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Fabric Toys Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Fabric Toys Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Fabric Toys Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

