
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Fiber To The Home (FTTH) Market Size 2023 | USD 48.90 Million |
| Fiber To The Home (FTTH) Market, CAGR | 10.80% |
| Fiber To The Home (FTTH) Market Size 2032 | USD 123.07 Million |
Market Overview
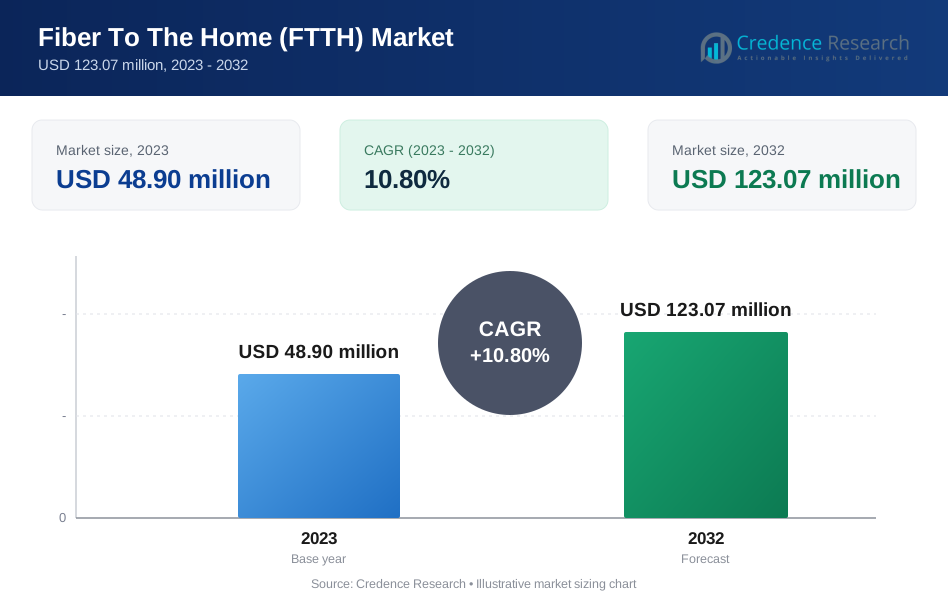
The global Fiber To The Home (FTTH) Market is projected to grow from USD 48.90 million in 2023 to an estimated USD 123.07 million by 2032, with a compound annual growth rate (CAGR) of 10.80% from 2024 to 2032. The increasing demand for high-speed internet connectivity, advancements in fiber optic technology, and growing adoption of FTTH services across residential, commercial, and industrial sectors are key contributors to this market's expansion.
Market drivers include the rise in data consumption, the increasing need for faster internet speeds, and government initiatives supporting broadband infrastructure development. Furthermore, FTTH adoption is also driven by the growing demand for bandwidth-intensive services such as video streaming, online gaming, and cloud computing. Technological advancements and the ongoing rollout of 5G networks are also fueling the need for efficient and high-speed connectivity solutions, which FTTH is well-positioned to provide.
Geographically, North America and Europe dominate the FTTH market, with significant investments in fiber optic infrastructure and a high adoption rate of FTTH services. Meanwhile, Asia-Pacific is anticipated to witness the highest growth during the forecast period, driven by large-scale FTTH deployment in countries like China, Japan, and South Korea. Key players in the market include AT&T, Verizon Communications, China Telecom, NTT Communications, and Deutsche Telekom.
Market Insights
- The FTTH market is projected to grow from USD 48.90 million in 2023 to USD 123.07 million by 2032, with a CAGR of 10.80% from 2024 to 2032.
- Increased data consumption and the need for faster internet speeds are driving market expansion, particularly with the growing demand for streaming and cloud services.
- Innovations in fiber optic technology and the ongoing rollout of 5G networks are key contributors to the FTTH market's growth.
- Government investments in broadband infrastructure and digital inclusion initiatives are fueling the adoption of FTTH services across various regions.
- High deployment costs and regulatory delays in certain regions can hinder the pace of FTTH rollout, particularly in rural and underserved areas.
- North America and Europe dominate the market, with Asia-Pacific set for the highest growth due to large-scale deployments in China and Japan.
- Major players like Verizon, AT&T, and China Telecom continue to lead, with increasing competition from regional providers and alternative broadband solutions.
Market Drivers
Rising Demand for High-Speed Internet Connectivity
The primary driver of the global Fiber to the Home (FTTH) market is the surging demand for high-speed internet connectivity. As digital content consumption escalates, both residential and business customers seek faster and more reliable internet services. Bandwidth-intensive applications like 4K/8K video streaming, virtual reality (VR), augmented reality (AR), online gaming, and cloud computing pressure existing network infrastructures. FTTH offers a robust solution with consistent and high-speed internet access and minimal latency. For instance, in the U.S., the average download speed is approximately 209.01 Mbps, reflecting the growing need for faster internet to support these applications. In India, the average monthly data consumption per user has reached 20.27 GB, highlighting the escalating demand for high-speed internet services. This increasing demand is pushing governments and private companies to expand fiber optic networks, particularly in urban and suburban areas, driving market growth globally.
Government Initiatives and Investments in Broadband Infrastructure
Government policies and initiatives supporting broadband infrastructure development are another significant factor fueling the FTTH market growth. Countries recognize the strategic importance of advanced internet infrastructure in driving economic growth, improving education, enhancing healthcare services, and fostering digital inclusion. Governments invest in fiber optic networks to bridge the digital divide, especially in rural areas. For example, as of April 2024, 95.15% of villages in India have access to internet with 3G/4G mobile connectivity, demonstrating government efforts to expand broadband infrastructure. Initiatives like the European Union's Digital Single Market strategy are accelerating FTTH deployments across Europe.
Technological Advancements in Fiber Optic Networks
Technological advancements in fiber optic networks are a critical factor driving the FTTH market. Innovations have reduced deployment costs, making FTTH more economically viable. Technologies like Dense Wavelength Division Multiplexing (DWDM) and Optical Network Terminals (ONTs) enhance data transmission rates and infrastructure efficiency. For instance, these innovations have significantly reduced deployment costs, making FTTH more feasible for both private and public entities. The symbiotic relationship between FTTH and 5G technologies is expected to further accelerate fiber network adoption, expanding the FTTH market globally.
Increasing Adoption of Fiber-Enabled Smart Homes and IoT Devices
The increasing adoption of smart home technologies and IoT devices is contributing to the FTTH market growth. Smart homes require fast and stable internet connections to function effectively. FTTH networks, with their high-speed and low-latency capabilities, are ideally suited to support the increasing bandwidth requirements of these connected devices. For example, in regions like North America and Europe, the rapid adoption of smart home devices and IoT solutions is driving the demand for FTTH networks. These devices require high-speed, low-latency connections to function effectively, further fueling the growth of the FTTH market.
Market Trends
Expanding FTTH Coverage in Emerging Markets
One of the most prominent trends in the global Fiber to the Home (FTTH) market is the increasing expansion of FTTH networks in emerging markets, particularly in Asia-Pacific, Latin America, and the Middle East. These regions are seeing significant investments in broadband infrastructure as both governments and private companies work to meet the growing demand for high-speed internet. In Asia-Pacific, countries like China, India, and Southeast Asian nations are witnessing accelerated FTTH deployments due to urbanization, growing digital literacy, and the increasing reliance on internet-based services. For instance, in India, the government's Digital India Program aims to connect around 600,000 rural citizens, bridging the digital gap between villages and cities by providing FTTH services across the nation. This growing focus on providing affordable, high-speed internet access in emerging economies is propelling FTTH adoption, particularly in areas where traditional broadband networks have struggled to meet demand.
Integration of FTTH with 5G Networks
As 5G technology continues to roll out globally, there is an emerging trend of integrating FTTH infrastructure with 5G networks. 5G networks require high-capacity, low-latency backhaul solutions to function efficiently, which is where FTTH plays a crucial role. FTTH provides the necessary bandwidth and performance to support the high-speed demands of 5G, particularly in urban areas where mobile data traffic is expected to surge. For instance, AT&T is integrating its fiber networks with 5G services to deliver seamless connectivity for applications like smart homes, telehealth, and cloud-based business solutions. This integration is expected to play a significant role in ensuring that 5G networks deliver their promised capabilities, while simultaneously boosting demand for fiber optic solutions.
Increased Focus on Fiber to the Building (FTTB) and Multi-Dwelling Units (MDUs)
A current trend in the FTTH market is the growing focus on Fiber to the Building (FTTB) and multi-dwelling units (MDUs), particularly in urban environments. While FTTH traditionally targets individual homes in suburban and rural areas, service providers are now looking at expanding fiber optic infrastructure to serve residential buildings and apartments more effectively. For instance, in urban environments, service providers are focusing on connecting high-rise apartments and office buildings with FTTH solutions, allowing them to serve multiple customers efficiently and meet the growing demand for reliable high-speed internet. This trend allows service providers to cater to multiple customers at once and improves the efficiency of FTTH deployments in densely populated areas.
Emergence of New Business Models and Competition
The competitive landscape of the FTTH market is evolving as new business models and service providers enter the market. Traditional telecom operators, who have been the dominant players in FTTH deployment, are facing growing competition from alternative service providers, municipal networks, and over-the-top (OTT) players who are venturing into the broadband market. For instance, the rise of open-access networks allows multiple service providers to offer their services on the same infrastructure, enhancing competition and improving service offerings for consumers. This dynamic environment is pushing traditional providers to innovate and improve their offerings to maintain market share, while simultaneously opening up opportunities for new business models and players to gain a foothold in the FTTH market.
Market Challenges
High Deployment Costs and Infrastructure Challenges
One of the most significant challenges facing the global Fiber to the Home (FTTH) market is the high cost of deployment. Building fiber optic networks requires significant investment in infrastructure, including the installation of fiber optic cables, network equipment, and related technology. For telecommunications companies, the costs associated with trenching, digging, and the installation of underground or overhead fiber lines can be substantial, particularly in densely populated urban areas or remote locations where the infrastructure is less developed. This high upfront capital expenditure can be a deterrent, especially in regions where the demand for FTTH services is not yet widespread. Additionally, maintenance and upgrading of fiber optic infrastructure over time further contribute to the overall cost. While the growing demand for high-speed internet helps justify these investments, the financial burden can limit the pace of FTTH rollout in some markets. Small or underserved communities, especially in rural or economically weaker regions, often face delays in receiving FTTH services due to the prohibitive costs of building the necessary infrastructure.
Regulatory Hurdles and Permitting Delays
Another challenge in the FTTH market is navigating the regulatory landscape and dealing with permitting delays. Deploying fiber optic networks often requires approvals from local governments, urban planners, and regulatory bodies, which can lead to delays in project timelines. Permitting processes can be complex, especially when digging up public roads or private lands for fiber optic cable installation. In many cases, this regulatory red tape can significantly slow down the deployment of FTTH services, particularly in regions where strict zoning laws and environmental concerns are prevalent. Furthermore, in some countries, regulatory frameworks may not be fully aligned with the rapid pace of technological advancements, leading to inefficiencies in the rollout of FTTH infrastructure. Regulatory delays and challenges can hinder the market's growth, particularly in markets that require significant regulatory compliance before network expansions can occur.
Market Opportunities
Expansion into Underserved and Rural Areas
One of the most promising opportunities in the global Fiber to the Home (FTTH) market lies in expanding coverage to underserved and rural areas. Despite the rapid deployment of FTTH networks in urban centers, many rural and remote regions still lack access to high-speed broadband. Governments and private sector players are increasingly focused on addressing this digital divide by investing in fiber optic infrastructure to enhance connectivity in rural areas. With the help of government incentives, grants, and regulatory support, FTTH providers have an opportunity to tap into these underserved markets. Expanding FTTH networks in rural regions not only supports digital inclusion but also opens up new revenue streams for service providers. The growing demand for reliable, high-speed internet in these areas for education, telemedicine, and remote work further emphasizes the opportunity for FTTH adoption, making this a key area for market growth.
Integration with Emerging Technologies
Another significant opportunity for the FTTH market lies in its integration with emerging technologies such as 5G, smart cities, and Internet of Things (IoT). As 5G networks roll out globally, the demand for robust backhaul infrastructure to support high-speed mobile networks will create synergies with FTTH deployments. FTTH networks are crucial for providing the high-capacity backhaul required for 5G small cells and enhancing overall 5G performance. Additionally, the rise of smart homes, smart cities, and IoT devices is driving demand for fast, low-latency internet connections. FTTH's ability to handle high data traffic makes it an ideal infrastructure solution for supporting these technologies, presenting a growth opportunity for providers that can integrate their services with the ongoing evolution of smart technologies.
Market Segmentation Analysis
By Download Speed
The download speed segment in the global FTTH market is divided into four key categories: Less than 50 Mbps, 50 to 100 Mbps, 100 Mbps to 1 Gbps, and More than 1 Gbps. The Less than 50 Mbps segment primarily serves basic internet users with minimal requirements such as browsing and emailing, mainly in rural or underdeveloped regions. This segment’s growth potential is limited due to the increasing demand for higher speeds. The 50 to 100 Mbps range targets residential users and small businesses that need moderate bandwidth for activities like streaming, video conferencing, and light gaming. The 100 Mbps to 1 Gbps segment is experiencing the most rapid expansion, driven by demand for high-definition video, online gaming, and cloud applications. Meanwhile, the More than 1 Gbps segment is growing as tech-savvy consumers and businesses require ultra-fast connections for high-performance applications like virtual reality and 4K/8K video streaming.
By Service Provider
The service provider segment in the FTTH market includes Low-cost Telecom Operators, Internet Service Providers (ISPs), Cable Operators, and Other Broadband Service Providers. Low-cost Telecom Operators focus on offering affordable FTTH services to price-sensitive consumers, particularly in underserved and rural areas. ISPs are major players in the market, catering to both residential and commercial customers with competitive pricing and bundled service packages. Cable Operators are increasingly transitioning to FTTH technologies to meet the growing demand for higher speeds and more reliable connections, as traditional cable networks struggle to support modern broadband services. Other Broadband Service Providers, including municipal networks and third-party vendors, are also emerging, with innovative business models like open-access networks, allowing multiple service providers to share the same fiber infrastructure.
Segments
Based on Download Speed
- Less than 50 Mbps
- 50 to 100 Mbps
- 100 Mbps to 1 Gbps
- More than 1 Gbps
Based on Service Provider
- Low-cost Telecom Operators
- Internet Service Providers (ISPs)
- Cable Operators
- Other Broadband Service Providers
Based on Application
- Internet TV
- VoIP (Voice over IP)
- Interactive Gaming
- Virtual Private LAN Services (VPLS)
Based on End User
- Single Family Homes
- Multiple Dwelling Units (MDUs)
- Small Office Home Offices (SOHO)
Based on Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East & Africa
Regional Analysis
North America (35%)
North America holds the largest market share in the FTTH market at approximately 35%, largely due to advanced infrastructure and widespread adoption of fiber optic technology in both residential and business sectors. The United States and Canada are key contributors, with strong government initiatives such as the FCC's Connect America Fund and state-level projects aimed at expanding broadband access to underserved areas. The presence of major service providers like AT&T, Verizon, and Comcast, along with high consumer demand for services such as video streaming and telecommuting, fuels the market growth in this region. Additionally, the rollout of 5G networks is expected to further drive FTTH deployment in urban areas, as fiber optic backhaul is essential for 5G infrastructure.
Europe (30%)
Europe accounts for approximately 30% of the global FTTH market, with key players including Deutsche Telekom, Orange, and Vodafone spearheading the expansion of fiber optic networks. Countries such as Spain, Sweden, and France have seen rapid adoption of FTTH due to significant government investments in digital infrastructure. The European Union's Digital Single Market strategy, which aims to increase broadband coverage across the continent, has further propelled FTTH deployments. High demand for services like Internet TV, VoIP, and remote work solutions is driving continued market growth in the region.
Key players
- Verizon Communications Inc.
- Optimum
- AT&T, Inc.
- Ziply Fiber
- Softbank Group Corp.
- Etisalat
- Frontier Communications Parent, Inc.
- Singtel
- Windstream Intellectual Property Services, LLC
- Century Link
- China Telecom Corporation Limited
- China Mobile Ltd
- Vodafone Group Plc
- Telefonica SA
- Nippon Telegraph and Telephone Corporation
Competitive Analysis
The global FTTH market is highly competitive, with leading players such as Verizon Communications Inc., AT&T, China Telecom, and Vodafone dominating the market. These companies leverage extensive infrastructure investments and a wide customer base to maintain their market share. For instance, Verizon and AT&T are focused on expanding their fiber-optic networks across North America to cater to the growing demand for high-speed internet, while China Telecom and China Mobile are driving growth in the Asia-Pacific region, supported by government-backed broadband initiatives. Companies like Softbank and Singtel are increasingly adopting 5G and FTTH integration to enhance network performance. Smaller regional players, such as Ziply Fiber and Windstream, are focusing on localized broadband deployments and customer-centric strategies. The competitive landscape is marked by aggressive pricing, technological innovations, and strong customer service, which enable these key players to maintain a competitive edge in the rapidly evolving FTTH market.
Recent Developments
- In February 2025, Verizon is expected to increase its capital expenditures (capex) by about $1 billion in 2025, partly due to an increase in FTTH passings by approximately 650,000 from 500,000 in 2024.
- In July 2023, Optimum launched its 8 Gig symmetrical fiber internet service, accessible to over 1.7 million residents and businesses, with plans to extend it to nearly 3 million locations by the end of 2023.
- In 2025 Outlook, AT&T aims to expand its FTTH footprint to 30 million homes passed by 2025. It plans to add about 2.7 million passings in 2025, increasing to over 3 million annually thereafter.
Market Concentration and Characteristics
The global Fiber to the Home (FTTH) market is moderately concentrated, with a few dominant players such as Verizon Communications Inc., AT&T, China Telecom, and Vodafone Group Plc. holding significant market share. These key players are primarily focusing on expanding their fiber optic networks through strategic investments and technological innovations to enhance service offerings and meet the growing demand for high-speed internet. The market is characterized by strong competition, with providers differentiating themselves through factors such as pricing, network reliability, and customer service. Moreover, the ongoing rollout of 5G networks and the integration of FTTH infrastructure are shaping the competitive dynamics. The market also sees the emergence of smaller, regional players targeting underserved areas, enabling greater access to fiber-optic broadband. Overall, while the market is driven by a few major corporations, it continues to witness growth in new and emerging regions, presenting opportunities for both large and smaller players to expand.
Report Coverage
The research report offers an in-depth analysis based on Download Speed, Service Provider, Application, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The global FTTH market is expected to grow at a CAGR of 10.80% from 2024 to 2032, driven by increased demand for high-speed internet and expanding digital infrastructure.
- Governments worldwide will continue to invest in broadband infrastructure to support digital inclusion and meet the needs of underserved regions, particularly in rural and remote areas.
- The rollout of 5G will drive further adoption of FTTH networks, as fiber optic backhaul is essential for supporting the high-speed requirements of 5G small cells.
- Innovations in fiber optic technology, such as optical network terminals and dense wavelength division multiplexing (DWDM), will improve network performance and reduce deployment costs.
- FTTH providers will focus on expanding coverage to rural and underserved regions, bridging the digital divide and offering high-speed connectivity to a broader population.
- The Fiber to the Building (FTTB) segment will grow significantly, as demand for high-speed internet increases in multi-dwelling units (MDUs) and commercial buildings.
- As smart home technologies become more prevalent, the demand for high-speed FTTH connections will rise to support devices like IoT and streaming services.
- The rise of open-access networks will provide new opportunities for multiple service providers to offer services over the same FTTH infrastructure, promoting competition and affordable pricing.
- Asia-Pacific, Latin America, and Africa will witness accelerated FTTH deployments as growing economies and government initiatives focus on broadband expansion in these regions.
- Future FTTH networks will prioritize sustainability, with companies investing in energy-efficient technologies and green practices to reduce environmental impact and meet evolving regulatory requirements.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the global FTTH market in 2023 and 2032?
What is the growth rate of the FTTH market?
What are the main drivers for the FTTH market's growth?
Which regions dominate the FTTH market?
Who are the key players in the FTTH market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Fiber To The Home (FTTH) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Fiber To The Home (FTTH) Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 48.90 million → 2032: USD 123.07 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Fiber To The Home (FTTH) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Fiber To The Home (FTTH) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Fiber To The Home (FTTH) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Fiber To The Home (FTTH) Market Drivers
- 3.3 Fiber To The Home (FTTH) Market Restraints & Challenges
- 3.4 Fiber To The Home (FTTH) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Fiber To The Home (FTTH) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Fiber To The Home (FTTH) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Fiber To The Home (FTTH) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Fiber To The Home (FTTH) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Fiber To The Home (FTTH) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Fiber To The Home (FTTH) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Fiber To The Home (FTTH) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Fiber To The Home (FTTH) Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Fiber To The Home (FTTH) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Fiber To The Home (FTTH) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Fiber To The Home (FTTH) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Fiber To The Home (FTTH) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Fiber To The Home (FTTH) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Fiber To The Home (FTTH) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Fiber To The Home (FTTH) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Fiber To The Home (FTTH) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Fiber To The Home (FTTH) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Fiber To The Home (FTTH) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Fiber To The Home (FTTH) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
