
Market Overview:
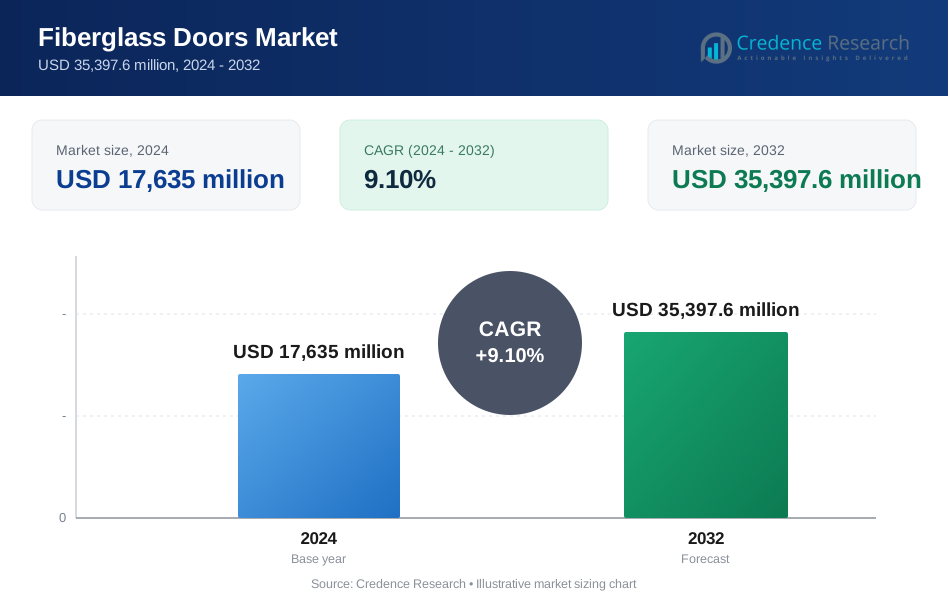
The fiberglass doors market size was valued at USD 17635 million in 2024 and is anticipated to reach USD 35397.6 million by 2032, at a CAGR of 9.1 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Fiberglass Doors Market Size 2024 | USD 17635 million |
| Fiberglass Doors Market, CAGR | 9.1% |
| Fiberglass Doors Market Size 2032 | USD 35397.6 million |
The market is driven by rising construction activity worldwide, coupled with increasing consumer preference for low-maintenance and long-lasting materials. Growing awareness of energy efficiency and sustainability in building practices has fueled demand for fiberglass doors, as they offer better thermal performance and weather resistance. Additionally, the trend toward smart and modern home designs, combined with customization options in styles, colors, and textures, is stimulating adoption. Manufacturers are also investing in technological innovations such as impact-resistant fiberglass and fire-rated doors to expand product applications.
Regionally, North America leads the fiberglass doors market due to strong residential remodeling trends and stringent energy efficiency regulations. Europe follows with a focus on sustainable construction and high adoption in modern housing projects. Asia Pacific is emerging as the fastest-growing market, driven by rapid urbanization, infrastructure development, and increasing disposable incomes in countries like China and India. Meanwhile, Latin America and the Middle East & Africa present growth opportunities through rising construction activities and expanding real estate investments.

Market Insights:
- The fiberglass doors market was valued at USD 17,635 million in 2024 and is projected to reach USD 35,397.6 million by 2032, registering a CAGR of 9.1%.
- Rising construction activity and consumer preference for durable, low-maintenance materials are driving strong adoption across residential and commercial sectors.
- Demand is fueled by growing awareness of energy efficiency and sustainability, with fiberglass doors offering superior insulation and weather resistance.
- Increasing customization in textures, finishes, glazing, and hardware supports both premium and budget-conscious buyers, enhancing market reach.
- High initial costs and competition from vinyl and aluminum doors remain key challenges, particularly in price-sensitive markets.
- North America leads with 38% share due to remodeling activity and energy efficiency regulations, while Europe holds 27% with strong sustainability initiatives.
- Asia Pacific, with 22% share, is the fastest-growing region, supported by rapid urbanization, rising incomes, and government investments in smart housing.
Market Drivers:
Growing Demand for Durable and Low-Maintenance Solutions:
The fiberglass doors market benefits from the shift toward materials that outperform traditional wood and steel. It offers superior resistance to warping, rusting, and rotting, which increases its lifespan and reduces maintenance costs for homeowners and commercial users. Consumers value the ability to achieve a wood-like appearance without the drawbacks of moisture absorption or termite damage. The rising preference for low-maintenance products strengthens adoption across residential and non-residential projects.
- For instance, Masonite’s Performance Door System fiberglass doors have withstood 8 inches of rainfall per hour and wind gusts over 50 mph during controlled durability tests.
Rising Focus on Energy Efficiency and Sustainability:
Energy efficiency regulations across major economies push builders and property owners to adopt materials that improve insulation and reduce energy loss. The fiberglass doors market meets this demand with products that provide superior thermal performance, ensuring lower heating and cooling costs. It also aligns with sustainability goals, as manufacturers integrate eco-friendly production methods and recyclable components. The emphasis on green construction practices enhances its role in meeting modern building standards.
- For instance, Andersen Corporation has developed fiberglass doors with a U-factor rating as low as 0.17, significantly improving insulation and energy conservation in residential buildings.
Advancements in Design Flexibility and Customization:
Architects and homeowners increasingly seek doors that combine strength with design versatility. The fiberglass doors market provides a wide range of textures, finishes, and color options that replicate wood or create modern aesthetics. It supports customization in size, glazing, and hardware, which appeals to both premium and budget-conscious segments. This ability to meet diverse preferences encourages wider adoption across new construction and renovation projects.
Expansion of Construction and Remodeling Activities Globally:
The global construction boom in residential and commercial sectors directly fuels demand for fiberglass doors. It gains traction in North America and Europe through strong remodeling activity and rising replacement demand. In Asia Pacific, rapid urbanization and real estate development accelerate uptake. Governments investing in infrastructure and smart housing further enhance its adoption, making it a critical component of modern building projects.
Market Trends:
Integration of Smart Features and Advanced Functionalities:
The fiberglass doors market is experiencing a rise in demand for products integrated with smart technologies. It now incorporates features such as electronic locks, security sensors, and energy-efficient glazing that appeal to modern homeowners. Builders and consumers favor doors that combine safety with convenience, leading to higher adoption in smart homes and commercial spaces. Manufacturers are investing in advanced materials to produce impact-resistant and fire-rated fiberglass doors that meet stricter building codes. The trend of blending aesthetics with technology strengthens product positioning in both residential and non-residential applications. It creates opportunities for brands to differentiate through innovation and value-added offerings.
- For instance, Simpson Door’s Fortress® Series fiberglass door earned a 90-minute fire-resistance rating under UL 10C testing, enhancing safety in commercial installations.
Expansion of Premium Designs and Sustainable Manufacturing:
The fiberglass doors market is witnessing growing demand for high-end designs that replicate natural wood with greater precision and durability. It offers a wide variety of finishes and textures that support architectural diversity while maintaining strength and longevity. Sustainability has become a central trend, with manufacturers focusing on recyclable materials and eco-friendly production processes. Rising awareness of green building certifications such as LEED encourages property owners to choose fiberglass doors for compliance. Urbanization and remodeling activities are fueling the preference for doors that deliver both style and energy efficiency. The trend toward sustainable premium products strengthens growth in developed markets and accelerates penetration in emerging regions.
- For instance, in 2021 Therma-Tru diverted 6.5 million pounds of manufacturing waste from landfills through enhanced recycling processes that capture scrap fiberglass, foam and wood components for reuse.
Market Challenges Analysis:
High Initial Costs and Intense Market Competition:
The fiberglass doors market faces the challenge of higher upfront costs compared to traditional wood and steel doors. It limits adoption among budget-conscious consumers, particularly in price-sensitive markets. Manufacturers compete to balance affordability with premium quality, but raw material and production costs remain significant. Intense competition from substitute materials such as vinyl and aluminum doors also affects market expansion. Many consumers remain inclined toward cheaper alternatives despite long-term benefits. The need to educate buyers on lifecycle cost savings is critical for sustained demand.
Supply Chain Constraints and Awareness Gaps in Emerging Regions:
Global supply chain disruptions and fluctuating raw material prices create obstacles for consistent production and distribution. It impacts manufacturers’ ability to maintain stable pricing, especially in regions with volatile economic conditions. Limited awareness of fiberglass doors in developing markets further slows adoption, as traditional wood remains a dominant choice. Builders and consumers often lack knowledge about its durability and energy efficiency advantages. Marketing and awareness campaigns are essential to overcome this knowledge gap. Without stronger outreach and reliable supply networks, growth potential in emerging economies remains underutilized.
Market Opportunities:
Rising Demand for Energy-Efficient and Sustainable Construction:
The fiberglass doors market presents strong opportunities through increasing global emphasis on energy-efficient and sustainable building solutions. It aligns with government regulations and consumer demand for materials that lower energy costs and reduce environmental impact. Fiberglass doors provide excellent insulation and contribute to green building certifications, making them attractive in both residential and commercial projects. Growing urbanization and infrastructure investments in emerging economies create demand for durable, low-maintenance solutions. Developers are seeking products that meet long-term performance standards, and fiberglass doors fit this requirement effectively. Expansion in green housing projects strengthens the growth outlook.
Innovation in Design, Smart Integration, and Premium Offerings:
The fiberglass doors market benefits from opportunities in advanced product development and customization. It supports integration of smart home features such as biometric locks and connected security systems, which enhance user convenience. Increasing consumer preference for premium designs that replicate natural wood with improved durability fuels demand in high-end housing and commercial spaces. Manufacturers are leveraging advanced textures, finishes, and glazing options to appeal to diverse customer segments. Opportunities also arise from expanding e-commerce channels that improve product accessibility worldwide. This shift toward innovation and premiumization enhances growth prospects across mature and emerging markets.
Market Segmentation Analysis:
By Product Type:
The fiberglass doors market is segmented into single doors, double doors, and others, with single doors holding a significant share due to their widespread use in residential spaces. It offers versatility, durability, and energy efficiency, making them attractive for both interior and exterior applications. Double doors gain traction in premium housing and commercial projects where aesthetics and space considerations drive demand. Other specialized door types, including sliding and custom-fit fiberglass doors, serve niche segments and add diversity to the market.
- For instance, Therma-Tru’s Smooth-Star® fiberglass door features a polyurethane foam core that delivers an R-Value of 7.7, greatly enhancing its insulating performance
By Design:
Design preferences shape adoption patterns, with paneled fiberglass doors leading due to their traditional appeal combined with modern durability. It allows homeowners to replicate the look of wooden doors while enjoying superior performance. Flush doors are popular in contemporary housing for their minimalistic and sleek design. Decorative glass-integrated fiberglass doors see rising demand in urban housing projects, where light transmission and design elegance enhance property value.
- For instance, Therma-Tru’s Smooth-Star® half-lite double door model S6021 is engineered to withstand wind forces up to 167 mph (DP-50), ensuring robust performance in high-wind conditions.
By End User:
The market serves residential, commercial, and industrial sectors, with residential applications accounting for the largest share. It benefits from strong adoption in new housing projects and growing renovation activities. Commercial spaces such as offices, hotels, and retail outlets increasingly use fiberglass doors for their strength and low maintenance. Industrial facilities also prefer these doors for their resistance to moisture, corrosion, and impact, supporting longevity in demanding environments.
Segmentations:
By Product Type:
- Single Doors
- Double Doors
- Others
By Design:
- Paneled Doors
- Flush Doors
- Decorative Glass Doors
- Others
By End User:
- Residential
- Commercial
- Industrial
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
North America holds 38% market share in the fiberglass doors market, making it the leading region. The United States drives growth with strong residential remodeling activity and strict energy efficiency regulations that favor fiberglass over traditional materials. It gains traction in commercial projects as builders adopt sustainable and low-maintenance options. The growing preference for durable products that reduce long-term costs strengthens demand across urban and suburban developments. Canada also contributes with rising housing renovation projects and government incentives for energy-efficient construction. Product innovation and premium customization further expand market acceptance in this region.
Europe:
Europe accounts for 27% market share in the fiberglass doors market, supported by strict building regulations and sustainability initiatives. It sees strong growth in countries such as Germany, the United Kingdom, and France, where energy efficiency standards influence material selection. Fiberglass doors are widely adopted in residential and commercial sectors due to their insulation and fire-resistant properties. Renovation projects in older housing stock provide additional opportunities for growth. The rising demand for eco-friendly construction materials aligns well with regional climate targets. Manufacturers focus on premium and customizable designs to meet architectural diversity in European markets.
Asia Pacific:
Asia Pacific holds 22% market share in the fiberglass doors market, positioning it as the fastest-growing region. China and India drive demand with large-scale urban housing projects and significant government investments in infrastructure. It benefits from rising disposable incomes, which support adoption of premium and durable building materials. The expansion of smart cities and sustainable housing initiatives further accelerates uptake. Japan and South Korea also show steady growth, supported by advanced construction practices and consumer demand for modern home designs. The growing awareness of energy-efficient materials creates long-term opportunities for manufacturers targeting this region.
Key Player Analysis:
- Assa Abloy AB
- ETO Doors Corp.
- Bayer Built Inc.
- Jeld-Wen Holding, Inc
- Masonite
- Kohltech
- Milgard Manufacturing LLC
- Master Grain
- Taylor Entrance Systems
- Pella Corporation
- Stanley Black & Decker Inc.
- PLASTPRO
- Steves & Sons
Competitive Analysis:
The fiberglass doors market is shaped by the presence of established global players and specialized regional manufacturers competing across product categories. Leading companies include Assa Abloy AB, ETO Doors Corp., Bayer Built Inc., Jeld-Wen Holding, Inc., Masonite, Kohltech, Milgard Manufacturing LLC, and Master Grain. It is defined by innovation in product design, emphasis on energy efficiency, and the introduction of customizable options to meet diverse consumer preferences. Larger players focus on expanding portfolios with premium finishes, smart integrations, and fire-rated solutions, while smaller firms strengthen their market position through cost competitiveness and local distribution networks. The competitive landscape reflects a balance between brand recognition, technological innovation, and the ability to meet sustainability standards. Strategic partnerships, acquisitions, and expansion in e-commerce channels remain key tools for companies to enhance global reach and capture a larger customer base in this growing market.
Recent Developments:
- In January 2025, Assa Abloy acquired InVue in the United States, expanding its product portfolio in security solutions.
- In August 2025, Assa Abloy announced the acquisition of SiteOwl, a cloud-based platform for physical security lifecycle management.
- In July 2025, Pella Corporation announced its acquisition of Weather Shield, a premium manufacturer of architectural wood and aluminum window and door solutions, significantly expanding Pella’s manufacturing footprint and product portfolio in the premium segment.
Market Concentration & Characteristics:
The fiberglass doors market demonstrates moderate concentration, with a mix of global leaders and regional manufacturers competing across product categories. It is characterized by innovation in design, focus on energy efficiency, and emphasis on durability to meet modern construction demands. Leading players invest in advanced materials, smart integration, and premium finishes to differentiate their offerings, while smaller firms target cost competitiveness and localized preferences. Competition intensifies through expansion in e-commerce channels and growing demand for sustainable solutions. It shows strong reliance on construction trends, regulatory frameworks, and consumer awareness, making adaptability and product diversification critical success factors.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Design, End User and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The fiberglass doors market will expand with rising demand for durable and low-maintenance alternatives to wood and steel.
- It will benefit from stricter energy efficiency regulations that increase adoption of thermally insulated door solutions.
- Growth in smart homes will drive demand for fiberglass doors integrated with electronic locks and security features.
- Manufacturers will focus on sustainable production methods and recyclable materials to align with green building standards.
- Premium designs replicating natural wood finishes will attract homeowners seeking aesthetics with long-term performance.
- Expansion in e-commerce channels will improve product accessibility and broaden customer reach globally.
- Rapid urbanization and infrastructure development in Asia Pacific will fuel higher adoption in residential and commercial projects.
- Renovation and remodeling activities in North America and Europe will continue to support replacement demand.
- Technological advancements in fire-rated and impact-resistant fiberglass doors will expand applications in safety-focused sectors.
- Competitive differentiation will rely on innovation, customization, and strategic partnerships to strengthen market positioning.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the fiberglass doors market, and what is its projected size in 2032?
Which fiberglass doors market segment held the largest share in 2024?
What are the primary factors fueling the growth of the fiberglass doors market?
Who are the leading companies in the fiberglass doors market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Fiberglass Doors Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Fiberglass Doors Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 17,635 million → 2032: USD 35,397.6 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Fiberglass Doors Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Fiberglass Doors Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Fiberglass Doors Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Fiberglass Doors Market Drivers
- 3.3 Fiberglass Doors Market Restraints & Challenges
- 3.4 Fiberglass Doors Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Fiberglass Doors Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Fiberglass Doors Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Fiberglass Doors category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Fiberglass Doors Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Fiberglass Doors Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Fiberglass Doors market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Fiberglass Doors Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Fiberglass Doors Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Fiberglass Doors Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Fiberglass Doors (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Fiberglass Doors Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Fiberglass Doors Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Fiberglass Doors Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Fiberglass Doors Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Fiberglass Doors Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Fiberglass Doors Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Fiberglass Doors Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Fiberglass Doors Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Fiberglass Doors Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
