
Market overview
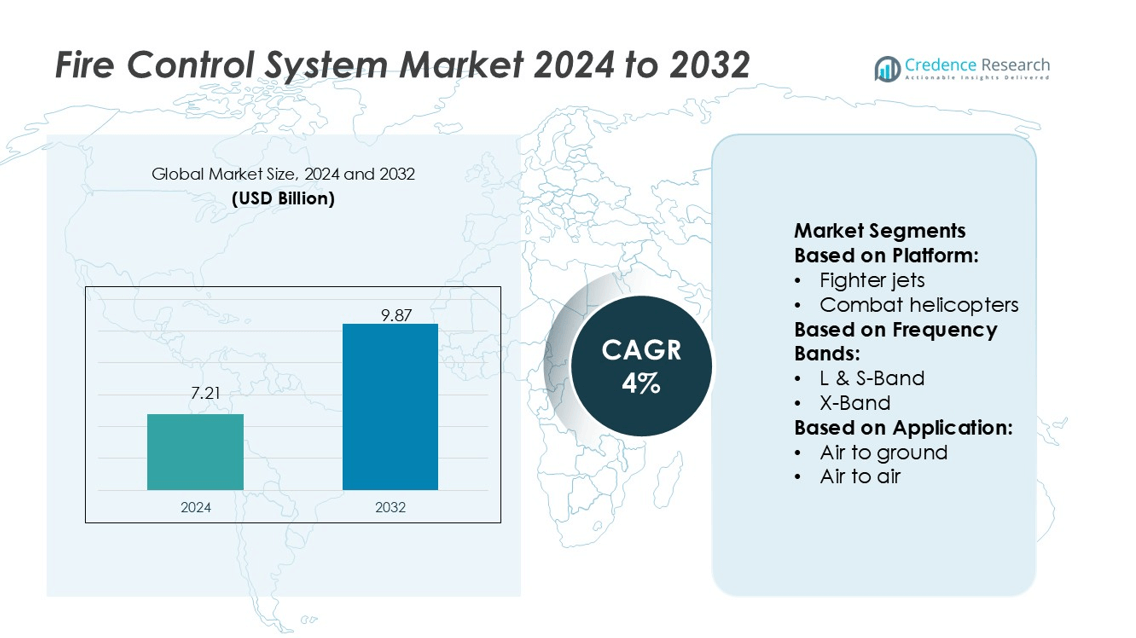
Fire Control System Market size was valued USD 7.21 billion in 2024 and is anticipated to reach USD 9.87 billion by 2032, at a CAGR of 4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Fire Control System Market Size 2024 | USD 7.21 billion |
| Fire Control System Market, CAGR | 4% |
| Fire Control System Market Size 2032 | USD 9.87 billion |
The fire control system market is driven by leading players such as Raytheon Technologies Corporation, Honeywell International, Siemens AG, Robert Bosch GmbH, Johnson Controls, Hitachi Ltd., Halma plc, GENTEX CORPORATION, Eaton, and Iteris, Inc. These companies focus on developing advanced radar, electro-optical sensors, and AI-enabled solutions to enhance precision and interoperability across combat platforms. Strategic partnerships, government contracts, and continuous R&D investment strengthen their global positions. Regionally, North America dominates the market with a 36% share, supported by high defense spending, strong technological capabilities, and the presence of major defense contractors spearheading modernization programs.
Market Insights
- The Fire Control System Market size was valued at USD 7.21 billion in 2024 and is expected to reach USD 9.87 billion by 2032, growing at a CAGR of 4%.
- Growing demand for precision-guided weapons and AI-enabled targeting solutions acts as a major driver, with fighter jets holding the largest platform share due to high procurement and modernization programs.
- A key trend includes the integration of multi-domain interoperability and advanced radar frequency bands, enhancing accuracy and real-time data sharing across platforms.
- High development and integration costs remain a restraint, particularly impacting adoption in regions with limited defense budgets.
- North America leads the market with a 36% share, driven by strong defense spending, while Asia-Pacific emerges as the fastest-growing region due to increasing military modernization and indigenous defense manufacturing initiatives.
Market Segmentation Analysis:
By Platform
Fighter jets hold the dominant share of the fire control system market, accounting for nearly 42% of total revenue. Their dominance is driven by rising defense modernization programs and the integration of advanced radar, targeting pods, and precision-guided munitions. Nations are prioritizing next-generation fighter aircraft with network-centric capabilities to ensure superiority in contested environments. Increasing global procurement of stealth fighters, such as the F-35 and Rafale, reinforces demand for advanced fire control solutions, as these platforms require high-performance targeting and tracking systems to enhance accuracy in multi-domain combat operations.
- For instance, Raytheon provides the AN/APG-79 Active Electronically Scanned Array (AESA) radar for the U.S. Navy's F/A-18E/F Super Hornet. It is capable of tracking multiple air targets simultaneously and has a detection range of up to approximately 150 kilometers (about 93 miles) against a standard 1-square-meter target.
By Frequency Bands
The X-Band segment dominates with 38% market share, supported by its precision in tracking and targeting applications. X-Band radars are widely adopted in fire control systems for fighter jets, helicopters, and naval platforms due to their superior resolution and ability to detect small, fast-moving targets. The adoption is further fueled by rising investments in phased-array radar technology and electronic countermeasure resistance. Defense programs across the U.S., Europe, and Asia-Pacific continue to favor X-Band systems, driving their leadership over L & S-Band and higher Ku/K/Ka-Band applications.
- For instance, Iteris introduced its Vantage Apex hybrid sensor combining 4D/HD radar and 1080p video, supporting stop-bar and advance detection out to 600 feet, with object tracking in up to 64 zones.
By Application
Air-to-ground applications lead with 44% market share, supported by the growing use of precision strike weapons and guided munitions. Modern combat increasingly requires accurate targeting of surface installations and armored formations, driving investment in fire control systems optimized for ground attack missions. Integration of laser designators, electro-optical sensors, and AI-enabled targeting enhances strike precision and minimizes collateral damage. The rise of asymmetric warfare and cross-border conflicts further strengthens demand for advanced air-to-ground capabilities, making this application segment the most significant contributor to overall market growth.
Key Growth Drivers
Rising Defense Modernization Programs
Global defense forces are heavily investing in modernizing their fleets of fighter jets, combat helicopters, and UAVs, fueling demand for advanced fire control systems. These upgrades focus on precision targeting, automated tracking, and multi-domain integration to improve battlefield effectiveness. Nations such as the U.S., China, and India are expanding procurement of advanced radar and sensor technologies, reinforcing this demand. Increased government spending on defense modernization ensures sustained adoption of fire control solutions across land, air, and naval platforms, making it a crucial growth driver.
- For instance, Honeywell secured a $103 million U.S. Army contract to deliver its Next-Gen APN-209 radar altimeter system, which replaces legacy units and enhances reliability in adverse weather and harsh environments.
Increasing Focus on Precision-Guided Weapons
The rising use of precision-guided munitions is significantly driving fire control system adoption. Modern warfare demands higher accuracy and reduced collateral damage, creating a strong need for advanced targeting and sensor integration. Fire control systems with electro-optical sensors, laser designators, and AI-based solutions are widely deployed to enhance strike effectiveness. As both developed and emerging nations expand their guided missile and smart munition inventories, the integration of advanced fire control systems becomes essential, ensuring higher operational efficiency in diverse combat environments.
- For instance, Bosch’s new radar SoCs, SX600 and SX601, built on 22-nm RF CMOS, extend detection range by about 30% over conventional sensors and use four transmit / four receive channels.
Growing Adoption of UAVs in Combat Operations
Unmanned Aerial Vehicles (UAVs) are becoming vital for surveillance, reconnaissance, and precision strikes, directly driving fire control system demand. Armed UAVs equipped with advanced targeting pods, radar systems, and AI-enabled fire control technologies provide strategic advantages in asymmetric warfare. Defense programs in countries such as Israel, the U.S., and Turkey highlight the growing reliance on UAVs for combat missions. The ability to conduct precision strikes with minimal human risk positions UAV-based fire control solutions as a major driver, supporting both tactical and strategic defense operations globally.
Key Trends & Opportunities
Integration of AI and Machine Learning
Artificial intelligence and machine learning are transforming fire control systems by enabling predictive targeting, automated decision-making, and enhanced accuracy. AI-driven algorithms analyze battlefield data in real time, supporting faster and more precise engagements. Defense contractors are actively embedding AI in radar, electro-optical sensors, and tracking modules, creating a competitive edge. This trend represents a significant opportunity for manufacturers to deliver next-generation fire control solutions that address evolving combat scenarios, ensuring technological superiority in highly contested environments.
- For instance, Johnson Controls unveiled an Illustra Edge AI LPR (License Plate Recognition) camera at GSX 2024 that performs onboard object analytics. It supports license plate recognition and runs deep neural networks on the edge. The camera is capable of streaming video at up to 30 frames per second, allowing for real-time AI processing of events.
Shift Toward Multi-Domain Operations
Modern combat strategies increasingly emphasize integration across land, sea, air, and space, driving the adoption of interoperable fire control systems. Defense forces seek systems capable of sharing data seamlessly across domains, improving situational awareness and response. Programs like the U.S. Joint All-Domain Command and Control (JADC2) highlight this shift, creating opportunities for manufacturers that can deliver network-enabled fire control solutions. Companies investing in interoperability and data fusion technologies are positioned to capture significant market share in this evolving defense landscape.
- For instance, Navtech Radar, a Halma subsidiary, builds 360° scanning radar systems for applications in ground surveillance and traffic management. Its AdvanceGuard ground surveillance system, for instance, offers high-definition radar that can detect and track targets, such as pedestrians and vehicles, with its longest-range sensor providing a detection radius of up to 5 kilometers.
Key Challenges
High Development and Integration Costs
Fire control systems are technologically complex, requiring advanced radar, sensors, and AI integration, which significantly raises development costs. Defense contractors face challenges in managing expenses while meeting the demand for cutting-edge capabilities. Additionally, integrating these systems into existing platforms often requires extensive customization, further increasing costs. This financial burden limits adoption among smaller defense budgets, particularly in developing nations, creating a barrier for market expansion despite rising global demand for modernized defense systems.
Vulnerability to Cybersecurity Threats
The growing digitization and network connectivity of fire control systems expose them to cybersecurity risks. Advanced systems rely heavily on data integration, AI, and satellite communication, making them susceptible to hacking, spoofing, and electronic warfare attacks. Such vulnerabilities can compromise mission-critical operations and reduce system reliability in combat. Ensuring robust cybersecurity frameworks and secure communication channels adds complexity and cost to development. Addressing these risks remains a key challenge for manufacturers and defense agencies aiming to safeguard operational effectiveness.
Regional Analysis
North America
North America leads the fire control system market with a 36% share, supported by strong defense spending and technological leadership. The U.S. spearheads advancements with large-scale investments in radar, electro-optical systems, and AI-based targeting solutions integrated into fighter jets, combat helicopters, and UAVs. Key defense contractors such as Lockheed Martin, Raytheon, and Northrop Grumman strengthen the region’s dominance by delivering next-generation solutions under major modernization programs. The demand is further driven by initiatives like JADC2, enhancing interoperability across platforms. Continuous innovation and export opportunities to allied nations ensure North America’s sustained leadership in the global market.
Europe
Europe holds a 25% share of the fire control system market, driven by increasing defense budgets and collaborative programs across NATO members. Countries such as France, Germany, and the U.K. prioritize upgrades in air and naval platforms, deploying advanced radar and precision-guided weapon systems. The European Defence Fund encourages joint R&D projects, accelerating technology adoption across the region. Rising geopolitical tensions in Eastern Europe have intensified procurement of modern combat systems, including AI-enabled fire control solutions. Strong contributions from companies like BAE Systems, Thales Group, and Leonardo S.p.A. further consolidate Europe’s position as a critical market player.
Asia-Pacific
Asia-Pacific accounts for 28% of the global fire control system market, with rapid growth fueled by military modernization and territorial disputes. China, India, Japan, and South Korea are leading contributors, investing heavily in advanced fighter jets, UAVs, and naval combat systems. Rising tensions in the South China Sea and Indo-Pacific region drive significant demand for precision-guided weapons and integrated fire control systems. Local manufacturing initiatives and indigenous defense programs boost market expansion, supported by collaborations with global players. With increasing procurement and defense partnerships, Asia-Pacific is emerging as a high-growth market with strong future potential.
Latin America
Latin America contributes 3% to the global fire control system market, with moderate growth influenced by limited defense budgets but increasing modernization needs. Brazil and Mexico lead the region’s adoption, focusing on upgrading air and naval capabilities with advanced targeting and radar solutions. Defense spending is primarily directed toward enhancing border security and counter-narcotics operations, driving demand for UAV-based fire control systems. Partnerships with U.S. and European manufacturers support technology transfer and deployment of modern systems. While budget constraints remain a challenge, gradual investments in modernization programs are expected to sustain market growth in the region.
Middle East & Africa
The Middle East & Africa region holds an 8% share, shaped by regional conflicts, counterterrorism efforts, and investments in defense modernization. Countries such as Saudi Arabia, Israel, and the UAE prioritize advanced targeting systems for both aerial and ground platforms. High reliance on imports from U.S. and European defense companies drives adoption of radar and electro-optical fire control solutions. African nations, though constrained by budgets, are increasingly investing in UAV-based systems for surveillance and counterinsurgency. Rising security concerns and defense procurement initiatives position the region as a steadily growing market segment, though challenges remain in affordability and local manufacturing.
Market Segmentations:
By Platform:
- Fighter jets
- Combat helicopters
By Frequency Bands:
- L & S-Band
- X-Band
By Application:
- Air to ground
- Air to air
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the fire control system market is shaped by key players including Raytheon Technologies Corporation, Iteris, Inc., Honeywell International, Inc., Siemens AG, Robert Bosch GmbH, Johnson Controls, Hitachi Ltd., Halma plc, GENTEX CORPORATION, and Eaton. The fire control system market is highly competitive, characterized by continuous innovation, technological integration, and strong defense modernization initiatives. Companies in this sector focus on developing advanced radar systems, electro-optical sensors, and AI-enabled targeting solutions to meet the growing demand for precision and multi-domain operations. Strategic partnerships, joint ventures, and defense contracts play a pivotal role in strengthening global presence and expanding product portfolios. The market also sees significant investments in interoperability and cybersecurity, ensuring system reliability in modern combat environments. Overall, competition is driven by innovation, operational efficiency, and long-term defense collaborations.
Key Player Analysis
- Raytheon Technologies Corporation
- Iteris, Inc.
- Honeywell International, Inc.
- Siemens AG
- Robert Bosch GmbH
- Johnson Controls
- Hitachi Ltd.
- Halma plc
- GENTEX CORPORATION
- Eaton
Recent Developments
- In June 2024, Edwards, a subsidiary of Carrier, introduced a new Optica duct smoke detector for commercial and industrial areas. It is specially designed to detect HVAC smoke in commercial and industrial premises.
- In January 2024, Lockheed Martin Corporation and Northrop Grumman collaborated to supply the U.S. Navy's E-2D Advanced Hawkeye with the 75th APY-9 radar. The latest iteration of the Advanced Hawkeye is equipped with Lockheed Martin's APY-9 radar system. The E-2, manufactured by Northrop Grumman, demonstrates exceptional proficiency in monitoring air, land, and sea simultaneously.
- In August 2023, Johnson Controls International Plc launched a new simplex foundation series of fire protection systems, which is suitable for industrial and commercial applications. In this series, the company introduced four fire alarm control units that offer features such as reliability, innovation, and cost-efficiency.
- In May 2023, Raytheon unveiled that its PhantomStrike radar will be incorporated into the FA-50 light combat aircraft by Korea Aerospace Industries (KAI). This advanced radar is entirely air-cooled and serves as a fire-control radar, offering extensive capabilities for detecting, tracking, and targeting threats over long range
Report Coverage
The research report offers an in-depth analysis based on Platform, Frequency Bands, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with rising adoption of AI-enabled targeting and tracking systems.
- Defense modernization programs will continue to drive procurement of advanced fire control solutions.
- UAV integration with precision strike capabilities will create new growth opportunities.
- Multi-domain interoperability will become a key requirement across land, air, and naval platforms.
- Cybersecurity measures will play a critical role in securing next-generation fire control systems.
- Demand for precision-guided weapons will strengthen adoption across both developed and emerging markets.
- Regional conflicts and border tensions will accelerate investments in advanced targeting systems.
- Collaborations between defense contractors and governments will shape long-term technology development.
- Indigenous manufacturing and defense localization initiatives will gain momentum in Asia-Pacific and Middle East.
- Continued innovation in radar frequency bands and electro-optical sensors will enhance market competitiveness.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Defense Modernization Programs
Global defense forces are investing heavily in upgrading fleets of fighter jets, helicopters, and UAVs, driving demand for advanced fire control systems with precision targeting and multi-domain integration. These modernization efforts ensure sustained adoption across land, air, and naval platforms.
Increasing Focus on Precision-Guided Weapons
The proliferation of precision-guided munitions and the need for higher strike accuracy are fueling the integration of advanced fire control systems with electro-optical sensors, laser designators, and AI-based targeting, enhancing operational effectiveness and reducing collateral damage.
Growing Adoption of UAVs in Combat Operations
Unmanned Aerial Vehicles are increasingly used for surveillance, reconnaissance, and precision strikes, necessitating sophisticated fire control systems for targeting and engagement. This trend is particularly strong in regions facing asymmetric warfare and border conflicts.
Integration of AI and Machine Learning
The adoption of AI and machine learning in fire control systems enables predictive targeting, automated decision-making, and real-time data analysis, significantly improving accuracy and response times in complex combat environments.
Shift Toward Multi-Domain Operations
Modern military strategies require interoperable fire control systems capable of seamless data sharing across land, sea, air, and space domains, driving demand for network-enabled and interoperable solutions that enhance situational awareness and mission effectiveness.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Fire Control System Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Fire Control System Market projected to grow between 2025 and 2032?
Which Fire Control System Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Fire Control System Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Platform
- 1.2.1 Fighter jets
- 1.2.2 Combat helicopters
- 1.2.3 Unmanned Aerial Vehicles (UAVs)
- 1.2.4 Naval vessels
- 1.2.5 Ground vehicles
- 1.3 By Application
- 1.3.1 Air to ground
- 1.3.2 Air to air
- 1.3.3 Naval targeting
- 1.3.4 Ground-based targeting
- 1.4 By Frequency Bands
- 1.4.1 L & S-Band
- 1.4.2 X-Band
- 1.4.3 Ku/K/Ka-Band
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7.21 billion → 2032: USD 9.87 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Fire Control System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Fire Control System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Fire Control System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Fire Control System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Fire Control System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Fire Control System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Fire Control System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Fire Control System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7.21 billion → 2032: USD 9.87 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Fire Control System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Platform - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fighter jets
- 12.3.7.2 Combat helicopters
- 12.3.7.3 Unmanned Aerial Vehicles (UAVs)
- 12.3.7.4 Naval vessels
- 12.3.7.5 Ground vehicles
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Air to ground
- 12.4.7.2 Air to air
- 12.4.7.3 Naval targeting
- 12.4.7.4 Ground-based targeting
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Frequency Bands - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 L & S-Band
- 12.5.7.2 X-Band
- 12.5.7.3 Ku/K/Ka-Band
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Fire Control System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Fire Control System Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Fire Control System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Fire Control System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Raytheon Technologies Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Honeywell International, Inc.
- 18.4 Siemens AG
- 18.5 Robert Bosch GmbH
- 18.6 Johnson Controls
- 18.7 Hitachi Ltd.
- 18.8 Halma plc
- 18.9 GENTEX CORPORATION
- 18.10 Eaton
- 18.11 Iteris, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

