
Market Overview
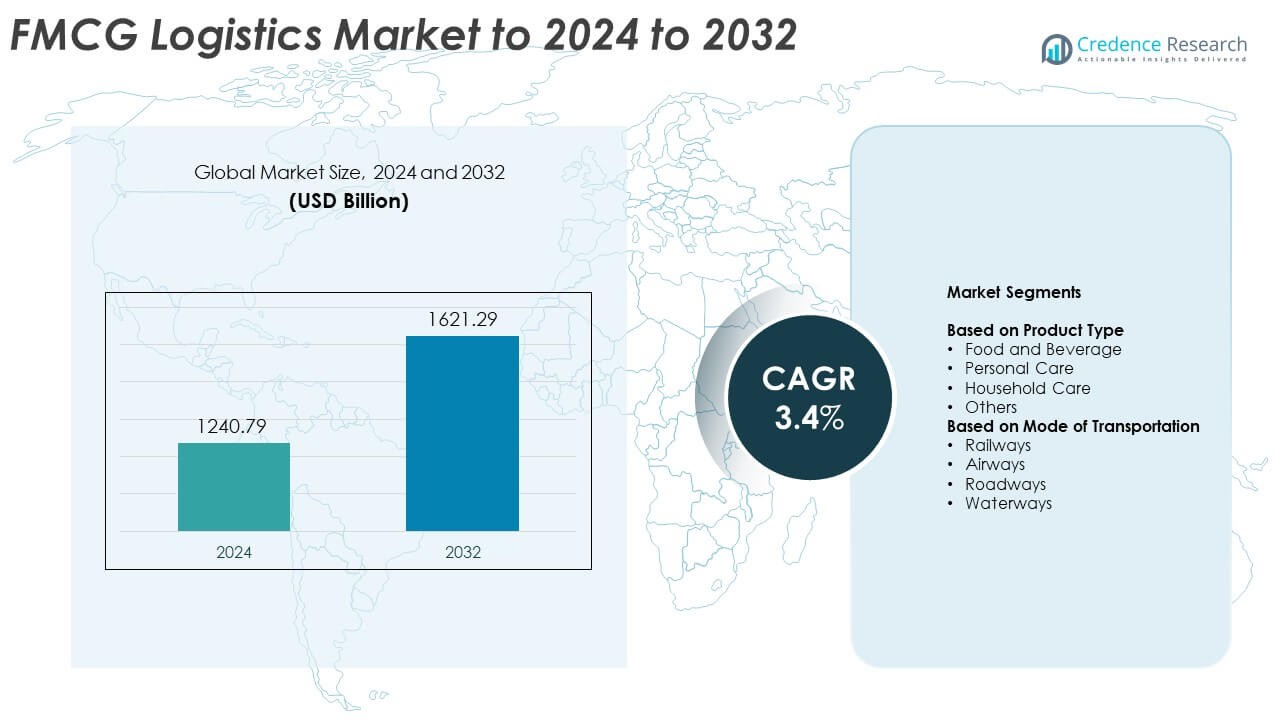
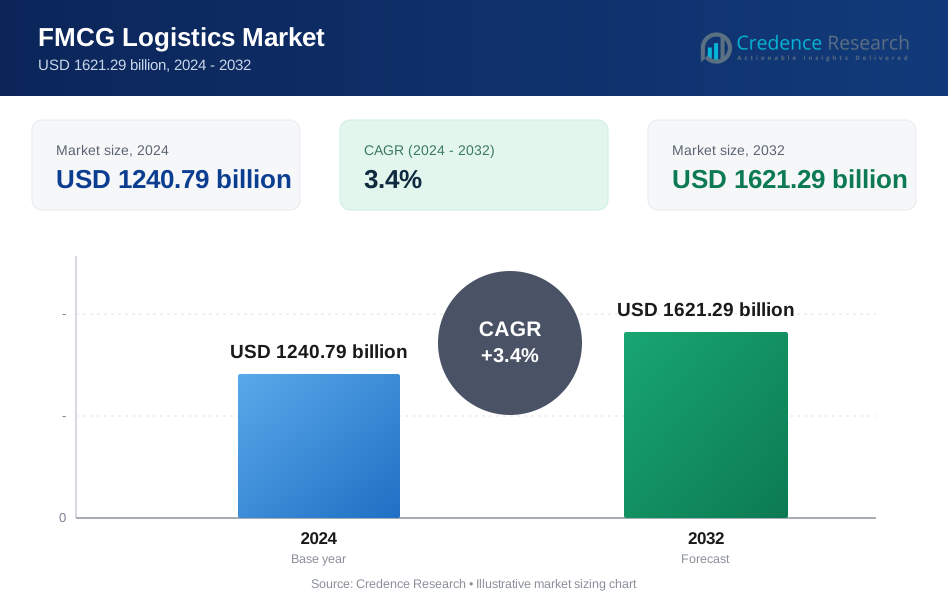
The FMCG Logistics Market size was valued at USD 1240.79 billion in 2024 and is anticipated to reach USD 1621.29 billion by 2032, at a CAGR of 3.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| FMCG Logistics Market Size 2024 | USD 1240.79 Billion |
| FMCG Logistics Market, CAGR | 3.4% |
| FMCG Logistics Market Size 2032 | USD 1621.29 Billion |
The FMCG logistics market is led by major companies such as DHL Supply Chain, FedEx, C.H. Robinson, Kuehne + Nagel, CEVA Logistics, Maersk, DB Schenker, UPS, DSV, Geodis, XPO Logistics, Rhenus Warehousing Solutions UK, Cainiao, and Swiggy. These players focus on automation, sustainability, and technology integration to enhance global logistics performance. North America emerged as the leading region in 2024, holding a 35% share, supported by advanced infrastructure and high e-commerce penetration. Europe followed with 29%, driven by strong cross-border trade networks and sustainable transport practices, while Asia Pacific accounted for 25%, fueled by rapid urbanization and growing digital retail ecosystems.
Market Insights
- The FMCG logistics market was valued at USD 1240.79 billion in 2024 and is expected to reach USD 1621.29 billion by 2032, growing at a CAGR of 3.4%.
- Growing e-commerce demand, improved cold chain infrastructure, and automation in warehousing are driving logistics efficiency and service speed.
- The market is witnessing trends like digital supply chain integration, green logistics adoption, and AI-based route optimization for faster delivery.
- The competitive landscape features global logistics providers focusing on sustainability, automation, and regional expansion to strengthen their network capabilities.
- North America led the market with a 35% share, followed by Europe at 29% and Asia Pacific at 25%, while the food and beverage segment held the largest share of 46% in 2024.
Market Segmentation Analysis:
By Product Type
The food and beverage segment held the largest share of approximately 46% of the FMCG logistics market in 2024. This dominance is driven by the continuous demand for perishable goods, requiring advanced cold chain solutions and rapid delivery systems. Growth in e-commerce grocery platforms and global trade of packaged foods has further increased logistics efficiency. The segment benefits from innovations such as temperature-controlled warehouses and smart tracking systems that reduce spoilage and improve delivery accuracy.
- For instance, PepsiCo installed a Dematic automated storage and retrieval system with 16,520 pallet locations at its Thailand distribution center, enabling fully automated movement from production lines to outbound docks.
By Mode of Transportation
The roadways segment accounted for the dominant share of around 61% of the FMCG logistics market in 2024, owing to its flexibility, cost-effectiveness, and last-mile connectivity. Trucks and delivery vans are widely used for intra-city and intercity transport of FMCG products. The adoption of GPS-enabled fleet management systems and electric delivery vehicles has enhanced operational reliability. Expanding road infrastructure and express delivery services further strengthen this mode’s preference among FMCG manufacturers and distributors.
- For instance, DHL Group operated a global fleet of more than 42,000 electric delivery vehicles as of September 2025.
Key Growth Drivers
Rising Demand for E-commerce Fulfillment
The rapid expansion of online retail has created strong demand for efficient FMCG logistics networks. Consumers now expect faster delivery times and flexible return options, pushing companies to optimize warehousing and distribution. Advanced automation, AI-driven route planning, and real-time tracking systems are helping brands streamline last-mile delivery operations. The integration of digital platforms and smart inventory systems enhances supply chain visibility, enabling FMCG players to meet rising consumer expectations while maintaining cost efficiency.
- For instance, Lineage Logistics operates over 485 temperature-controlled facilities totaling about 3.1 billion cubic feet of capacity worldwide, supporting major FMCG distribution networks.
Expansion of Cold Chain Infrastructure
Growth in perishable and temperature-sensitive product categories, including dairy, frozen foods, and pharmaceuticals, has strengthened the need for cold chain logistics. Companies are investing in advanced refrigerated vehicles and temperature-controlled storage facilities to maintain product quality. The use of IoT-based monitoring ensures real-time tracking of temperature deviations. This infrastructure expansion supports safe and efficient transport of perishable goods across domestic and international routes, helping FMCG manufacturers maintain product integrity and reduce wastage.
- For instance, Walmart partnered with Symbotic to deploy automation systems in over 400 Accelerated Pickup and Delivery (APD) centers.
Technological Integration and Automation
Automation and digital transformation are driving major efficiency gains in FMCG logistics. Technologies like robotics, AI, and IoT enable real-time visibility, predictive maintenance, and automated warehouse operations. Smart sensors and data analytics optimize fleet performance and energy consumption. The adoption of automated sorting systems and robotic picking improves accuracy and speed, reducing manual labor costs. As digitalization accelerates, logistics networks are becoming more agile, resilient, and responsive to fluctuating consumer demand.
Key Trends and Opportunities
Sustainability and Green Logistics
Environmental concerns are prompting FMCG companies to adopt eco-friendly logistics solutions. Firms are deploying electric delivery vehicles, optimizing routes to cut fuel use, and investing in recyclable packaging. Green warehouses powered by renewable energy are becoming more common. These sustainable practices not only reduce carbon emissions but also improve brand reputation among environmentally conscious consumers. Regulatory support and incentives for green supply chains further encourage sustainable logistics investments.
- For instance, Geopost (DPD Group) expanded its low-emission fleet to more than 10,000 electric vans and cargo bikes for urban deliveries in 2024.
Rising Cross-Border Trade and Global Distribution
Expanding international trade in FMCG products offers strong growth opportunities for logistics providers. Companies are developing regional hubs and bonded warehouses to improve delivery efficiency in key markets. Digital trade platforms and customs automation simplify cross-border operations, reducing clearance delays. The demand for reliable and cost-effective international freight solutions is pushing logistics firms to expand global partnerships and enhance multimodal capabilities for faster and safer deliveries.
- For instance, Cainiao averaged over 5,000,000 cross-border packages daily in FY2024. Cainiao also launched a Xi’an–Liège charter operating 2 flights per week from September 2024.
Key Challenges
Rising Transportation Costs
Increasing fuel prices and vehicle maintenance expenses are significantly impacting FMCG logistics profitability. As companies strive to offer competitive pricing, high transportation costs put pressure on operating margins. Fluctuating energy costs and labor shortages further add to the challenge. Logistics providers are countering these issues by adopting energy-efficient fleets, optimizing load capacity, and using predictive analytics to manage expenses. However, balancing service quality with cost control remains a critical challenge.
Supply Chain Disruptions and Labor Shortages
Frequent supply chain disruptions caused by global conflicts, natural disasters, and labor constraints continue to affect FMCG logistics operations. Shortages of skilled drivers, warehouse workers, and technicians delay order fulfillment and increase delivery times. Automation and digital tools mitigate some of these risks, but dependency on human resources remains high in several regions. Strengthening supply chain resilience and workforce retention strategies is essential to sustain reliability and business continuity.
Regional Analysis
North America
North America held the largest share of about 35% of the FMCG logistics market in 2024. The region’s dominance is supported by advanced logistics infrastructure, high consumer spending, and the presence of major retail chains. Strong e-commerce penetration in the United States and Canada has increased demand for faster fulfillment and last-mile delivery services. Investments in automation, AI-enabled tracking, and sustainable delivery fleets continue to enhance operational efficiency. The focus on temperature-controlled logistics for food and beverage distribution further supports regional market growth.
Europe
Europe accounted for around 29% of the FMCG logistics market share in 2024, driven by well-established transport networks and strong regulatory standards. The region benefits from cross-border trade within the European Union, enabling streamlined movement of FMCG goods. Demand for sustainable logistics and green transport is rising as companies shift to low-emission vehicles. The expansion of cold chain capacity and adoption of digital supply chain systems are improving efficiency. Markets like Germany, France, and the United Kingdom remain key hubs for FMCG distribution and warehousing operations.
Asia Pacific
Asia Pacific captured about 25% of the FMCG logistics market in 2024, fueled by rapid urbanization, expanding retail networks, and rising disposable incomes. Countries such as China, India, and Japan are experiencing strong growth in e-commerce and consumer goods production. The region’s logistics players are investing heavily in smart warehouses and AI-driven route optimization. Increasing demand for cold chain solutions to handle perishable goods is accelerating market development. Government initiatives to enhance port connectivity and regional trade routes further strengthen Asia Pacific’s logistics capabilities.
Latin America
Latin America represented roughly 7% of the FMCG logistics market in 2024. Growth is supported by expanding retail infrastructure and increased adoption of digital logistics systems in Brazil, Mexico, and Argentina. The region’s improving road networks and growing cross-border trade within Mercosur contribute to logistics efficiency. However, challenges such as inconsistent regulatory frameworks and infrastructure gaps persist. Rising consumer demand for fast-moving products and the shift toward e-commerce distribution are expected to attract further investment in regional logistics operations.
Middle East & Africa
The Middle East and Africa accounted for nearly 4% of the FMCG logistics market share in 2024. The region’s growth is driven by expanding retail modernization, increasing urban populations, and rising demand for packaged goods. Gulf countries such as the UAE and Saudi Arabia are investing in advanced logistics hubs and free trade zones. Africa is witnessing gradual progress in transport infrastructure and cold chain development. While challenges in connectivity and customs processes remain, increasing investments in warehousing and digital supply chains are enhancing efficiency across the region.
Market Segmentations:
By Product Type
- Food and Beverage
- Personal Care
- Household Care
- Others
By Mode of Transportation
- Railways
- Airways
- Roadways
- Waterways
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The FMCG logistics market is shaped by global players such as DHL Supply Chain, FedEx, C.H. Robinson, Kuehne + Nagel, CEVA Logistics, Maersk, DB Schenker, UPS, DSV, Geodis, XPO Logistics, Rhenus Warehousing Solutions UK, Cainiao, and Swiggy. These companies focus on expanding warehousing capacity, digital automation, and sustainable logistics networks to enhance supply chain efficiency. The industry is witnessing major investments in AI-based route optimization, real-time tracking, and temperature-controlled storage for perishable goods. Strategic collaborations with e-commerce and FMCG brands are driving innovation in last-mile delivery and cold chain logistics. Firms are also integrating electric vehicle fleets and renewable-powered warehouses to reduce emissions and operational costs. The competitive environment emphasizes service diversification, regional expansion, and digital transformation to strengthen market presence and customer satisfaction across both developed and emerging economies.
Key Player Analysis
- DHL Supply Chain
- FedEx
- H. Robinson
- Kuehne + Nagel
- CEVA Logistics
- Maersk
- DB Schenker
- UPS
- DSV
- Geodis
- XPO Logistics
- Rhenus Warehousing Solutions UK
- Cainiao
- Swiggy
Recent Developments
- In 2025, XPO earned the 2025 EcoVadis Gold Medal for its sustainability efforts, placing it in the top 1% of logistics companies worldwide.
- In 2024, Kuehne+Nagel opened a highly automated distribution center in Mantua, Italy, for Adidas, capable of handling a high volume of shipments for Southern and Eastern Europe.
- In 2023, Maersk initiated a green shipping program by bunkering its first methanol-enabled vessel, the Laura Maersk, demonstrating a commitment to more sustainable logistics.
- In 2023, DHL launched its "GoGreen Plus" service, offering a green logistics solution for shippers by powering freight with Sustainable Aviation Fuels.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Mode of Transportation and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The FMCG logistics market will see increased automation, with robotics improving warehouse efficiency.
- Green logistics practices will gain momentum as companies invest in low-emission fleets and packaging.
- E-commerce growth will continue to drive demand for faster and more reliable last-mile delivery.
- Digital twins and IoT systems will enhance visibility and predictive maintenance across supply chains.
- Cold chain logistics will expand rapidly due to rising demand for perishable food and pharmaceuticals.
- Cross-border trade integration will strengthen, supported by digital customs and smart port networks.
- Artificial intelligence will optimize route planning, load management, and fuel efficiency for carriers.
- Urban logistics hubs will emerge to manage same-day delivery and reduce congestion in cities.
- Strategic partnerships between FMCG producers and logistics providers will improve scalability and service reach.
- Data-driven analytics will become vital for demand forecasting, risk assessment, and inventory optimization.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for FMCG Logistics Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the FMCG Logistics Market projected to grow between 2025 and 2032?
Which FMCG Logistics Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the FMCG Logistics Market?
Who are the leading companies in the FMCG Logistics Market?
Which region commanded the largest share of the FMCG Logistics Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 FMCG Logistics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global FMCG Logistics Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1240.79 billion → 2032: USD 1621.29 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 FMCG Logistics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. FMCG Logistics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 FMCG Logistics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 FMCG Logistics Market Drivers
- 3.3 FMCG Logistics Market Restraints & Challenges
- 3.4 FMCG Logistics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 FMCG Logistics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 FMCG Logistics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, FMCG Logistics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 FMCG Logistics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. FMCG Logistics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the FMCG Logistics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 FMCG Logistics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 FMCG Logistics Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 FMCG Logistics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in FMCG Logistics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New FMCG Logistics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global FMCG Logistics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America FMCG Logistics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe FMCG Logistics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific FMCG Logistics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America FMCG Logistics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East FMCG Logistics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa FMCG Logistics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. FMCG Logistics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
