
Market Overview
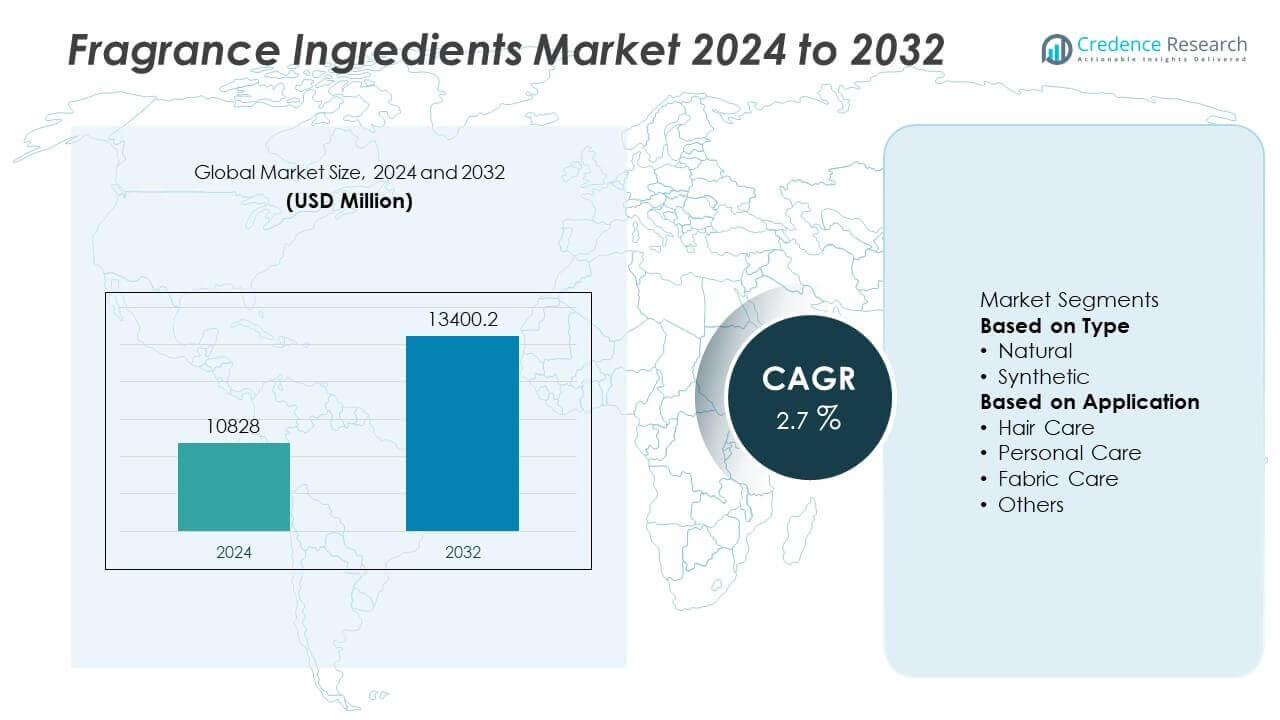
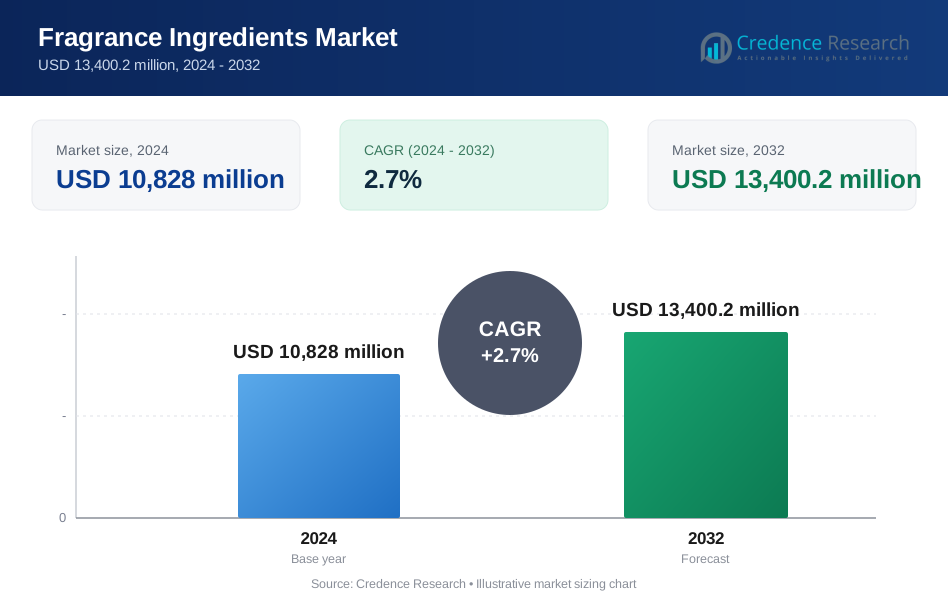
The fragrance ingredients market was valued at USD 10,828 million in 2024 and is projected to reach USD 13,400.2 million by 2032, growing at a CAGR of 2.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Fragrance Ingredients Market Size 2024 | USD 10,828 Million |
| Fragrance Ingredients Market, CAGR | 2.7% |
| Fragrance Ingredients Market Size 2032 | USD 13,400.2 Million |
Fragrance Ingredients Market grows with rising demand for natural, clean-label, and sustainable formulations across personal care, cosmetics, and home care sectors. Consumers seek safer products with transparent ingredient lists, driving investments in plant-based and bio-derived aroma molecules.
Fragrance Ingredients Market shows strong presence across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa, with Europe leading due to its rich perfumery heritage and strict regulatory standards that drive innovation in safe and sustainable formulations. North America benefits from advanced R&D facilities and growing demand for clean-label, natural, and hypoallergenic products, while Asia-Pacific experiences rapid growth supported by urbanization, rising disposable incomes, and expanding personal care consumption. Latin America and Middle East & Africa witness increasing demand for fine fragrances, deodorants, and traditional scents, creating opportunities for global and regional suppliers. Key players such as Givaudan, Mane SA, Firmenich SA, and International Flavors & Fragrances Inc. focus on launching bio-based aroma molecules, expanding production capacity, and enhancing digital fragrance design platforms to meet evolving customer needs. Collaborations with local brands and investments in sustainable solutions strengthen their competitive positioning across these diverse regions.
Market Insights
- Fragrance Ingredients Market was valued at USD 10,828 million in 2024 and is projected to reach USD 13,400.2 million by 2032, growing at a CAGR of 2.7%.
- Demand for natural, clean-label, and bio-based ingredients drives adoption across personal care, cosmetics, and home care products.
- Trends show rising popularity of niche perfumes, personalized fragrances, and sustainable formulations supported by green chemistry and biotech solutions.
- Competition remains strong with global leaders such as Givaudan, Firmenich SA, Mane SA, and International Flavors & Fragrances Inc. investing in innovation and expanding their portfolios.
- Price volatility of essential oils and petrochemical-derived aroma chemicals creates supply chain pressure and impacts margins for manufacturers.
- Europe leads in innovation and regulatory compliance, while Asia-Pacific shows the fastest growth with expanding middle-class demand and rising personal care consumption.
- Opportunities emerge from e-commerce expansion, increasing wellness product sales, and growing preference for eco-certified and biodegradable fragrance solutions worldwide.
Market Drivers
Rising Demand for Premium and Natural Fragrances
Fragrance Ingredients Market grows with increasing consumer preference for premium and natural formulations. Rising awareness of health and wellness encourages brands to use plant-based and bio-derived ingredients. Consumers seek products that avoid synthetic chemicals and allergens, driving demand for safe and transparent labels. Brands invest in natural essential oils, botanical extracts, and biodegradable compounds to meet these needs. The shift strengthens partnerships between suppliers and fragrance houses to create clean and sustainable solutions. It supports product differentiation in competitive beauty and personal care markets.
- For instance, The Robertet Group is a leading supplier of natural raw materials, including organic essential oils, sourced globally. This includes key sourcing activities in Grasse, France, where the company is headquartered, and Madagascar, where it specifically produces ingredients like Ylang-Ylang. The company's ingredients and products are designed to be IFRA-compliant and feature processes to reduce allergens, such as its patented cleanRscent line of hexane-residue-free absolutes.
Expanding Applications Across Multiple Industries
Fragrance Ingredients Market benefits from its use in personal care, home care, and fine fragrances. Rising demand for air fresheners, detergents, and cosmetics fuels consumption of specialty aroma chemicals. Growth in household cleaning products and luxury perfumes supports stable ingredient demand. The market serves food and beverage sectors through flavor-enhancing ingredients for functional products. It also attracts interest from aromatherapy brands targeting relaxation and wellness segments. This broad application base ensures steady revenue streams for suppliers.
- For instance, T. Hasegawa provides more than 12,000 custom flavor and fragrance products for global food and beverage brands, offering a "high-mix, low-volume" approach. The company's portfolio covers both sweet and savory applications and emphasizes responsiveness to customer needs.
Innovation in Sustainable and Biodegradable Solutions
Fragrance Ingredients Market advances with strong focus on sustainability and green chemistry. Companies develop biodegradable fixatives, bio-based solvents, and low-VOC compounds to meet regulatory expectations. It drives R&D investments into renewable feedstocks and energy-efficient production methods. Brands adopt eco-certified and IFRA-compliant ingredients to appeal to environmentally conscious consumers. Suppliers prioritize circular economy practices, including waste reduction and recycling initiatives. These innovations help manufacturers maintain compliance and gain a competitive edge.
Regulatory Compliance and Quality Standardization
Fragrance Ingredients Market is influenced by strict global regulations and quality standards. Governments enforce REACH, IFRA, and FDA guidelines to ensure consumer safety. It compels producers to maintain transparent sourcing and traceability across supply chains. Brands implement rigorous quality testing to reduce risk of allergens or harmful chemicals. Compliance supports trust among end users and retailers. Strong adherence to standards safeguards market reputation and encourages sustainable growth.
 Market Trends
Shift Toward Clean Label and Transparency
Fragrance Ingredients Market shows a strong trend toward clean-label and transparent formulations. Consumers want detailed ingredient disclosure and safer options for daily use. Brands focus on allergen-free, phthalate-free, and paraben-free formulations to meet this demand. It encourages suppliers to invest in traceability and clear labeling practices. Retailers promote products with sustainability certifications to gain customer trust. This shift drives competition toward innovation in safe and natural fragrance molecules.
- For instance, in June 2024, International Flavors & Fragrances Inc. (IFF) unveiled three new ingredients, including a single new fragrance molecule called Ylanganate. In general, IFF and its LMR Naturals division focus on producing sustainable, IFRA-compliant, and phthalate-free ingredients
Growing Popularity of Niche and Personalized Scents
Fragrance Ingredients Market benefits from rising interest in niche and customized perfumes. Consumers seek unique scents that reflect individuality and lifestyle. Perfume houses develop limited-edition blends using rare and exotic ingredients. It supports small and artisanal fragrance brands in gaining market presence. Luxury brands expand personalization services, allowing customers to create signature fragrances. This trend strengthens demand for specialty aroma chemicals and natural extracts.
- For instance, in 2025, fragrance house Mane SA expanded its ingredient portfolio by launching new innovative extracts like ANTILLONE™, a 100% natural fruit ketone, and showcasing products that use its proprietary PURE JUNGLE ESSENCE™ technology, which is manufactured at its facilities including the Bar-sur-Loup site.
Adoption of Green Chemistry and Biotech Solutions
Fragrance Ingredients Market embraces green chemistry and biotechnology to meet sustainability goals. Companies use fermentation and enzyme-based processes to create bio-identical aroma molecules. It helps reduce reliance on petrochemical sources and lowers carbon footprint. Suppliers explore renewable feedstocks to ensure stable supply and cost efficiency. Brands highlight bio-based content on labels to attract eco-conscious consumers. These advances improve product safety and regulatory compliance.
Integration of Digital Tools in Fragrance Creation
Fragrance Ingredients Market is witnessing digital transformation in product design and testing. AI and data analytics help perfumers predict consumer preferences and create better blends. It accelerates the formulation process and shortens time-to-market for new products. Virtual reality tools enable customers to explore fragrance profiles online. Digital platforms allow faster collaboration between suppliers and fragrance houses. This adoption of technology enhances efficiency and product innovation.
Market Challenges Analysis
Volatility in Raw Material Prices and Supply Chain Disruptions
Fragrance Ingredients Market faces challenges due to fluctuating raw material costs and unstable supply chains. Natural ingredients like essential oils depend on agricultural yields, which vary with climate conditions. Price spikes for petrochemical-derived aroma compounds affect profit margins for manufacturers. It creates uncertainty for producers who must balance cost control with quality. Global logistics delays and geopolitical tensions add further complexity to sourcing. Companies invest in supplier diversification and inventory management to reduce these risks. Maintaining consistent quality while managing costs remains a key concern.
Regulatory Compliance and Allergen Restrictions
Fragrance Ingredients Market is impacted by stringent regulatory frameworks and evolving allergen guidelines. IFRA standards, REACH rules, and FDA requirements limit the use of several fragrance compounds. It forces companies to reformulate products and conduct extensive safety testing. These changes raise development costs and slow product launches. Brands face challenges in communicating compliance while maintaining scent performance. Small manufacturers struggle with the high cost of certification and documentation. Meeting global compliance while staying competitive requires significant investment in R&D and regulatory expertise.
Market Opportunities
Rising Demand for Sustainable and Bio-Based Ingredients
Fragrance Ingredients Market holds strong opportunities through the shift toward sustainable and bio-based solutions. Consumers prefer eco-friendly products with minimal environmental impact, driving adoption of renewable ingredients. It motivates suppliers to invest in plant-derived aroma molecules and biodegradable compounds. Brands highlight sustainability credentials to build loyalty and attract conscious buyers. Growing interest in carbon-neutral manufacturing creates scope for innovation in production processes. This trend allows manufacturers to differentiate offerings and expand into premium segments.
Expansion in Emerging Economies and E-Commerce Channels
Fragrance Ingredients Market gains growth potential from rising disposable incomes in Asia-Pacific, Latin America, and Middle East & Africa. Urbanization and lifestyle changes increase demand for personal care, cosmetics, and home care products. It opens new opportunities for suppliers to partner with local brands and formulators. E-commerce platforms accelerate product reach and support niche fragrance launches. Digital marketing and direct-to-consumer models enable faster market penetration. These opportunities encourage global players to expand operations and strengthen regional distribution networks.
Market Segmentation Analysis:
By Type
Fragrance Ingredients Market is segmented by type into essential oils, aroma chemicals, and synthetic ingredients. Essential oils dominate demand due to rising consumer interest in natural and plant-based solutions. Brands in personal care and aromatherapy use essential oils to promote wellness and relaxation. It also benefits from clean-label trends and preference for allergen-free formulations. Aroma chemicals play a critical role in delivering consistent and long-lasting scents for perfumes and household products. Synthetic ingredients remain relevant due to cost efficiency and ability to replicate rare natural aromas. The balance between natural and synthetic ingredients drives product innovation across the industry.
- For instance, doTERRA sources its lavender and peppermint oils through its Co-Impact Sourcing initiative, partnering with local growers in over 45 countries to supply its network of over 10 million customers and distributors worldwide. The company achieved annual sales of over $2 billion in 2024 through this direct-to-consumer model.
By Application
Fragrance Ingredients Market by application covers personal care, fine fragrances, home care, and cosmetics. Personal care leads adoption, driven by shampoos, soaps, and deodorants that rely on signature scents for brand identity. Fine fragrances represent a premium segment, using rare and high-quality ingredients to create luxury perfumes. It attracts steady demand from both niche perfume houses and global players. Home care products such as air fresheners, detergents, and candles contribute significantly to volume sales. Cosmetics use fragrance ingredients to enhance product appeal and consumer experience. Growth across these applications supports steady demand for both natural and specialty fragrance compounds, sustaining overall market expansion.
- For instance, S H Kelkar & Co. did experience business expansion and reported growth in its fragrance segment in both domestic and international markets in 2024. During this time, the company expanded its international operations by establishing a new subsidiary in Germany and another in the U.S., while also preparing to commission a new factory in Indonesia.
Segments:
Based on Type
- Natural
- Synthetic
Based on Application
- Hair Care
- Personal Care
- Fabric Care
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds 28% market share in the Fragrance Ingredients Market, driven by strong demand for premium perfumes, cosmetics, and home care products. The region benefits from well-established fragrance houses and multinational personal care brands headquartered in the U.S. and Canada. It sees rising adoption of clean-label and natural fragrance formulations, reflecting consumer focus on safety and sustainability. Strict regulatory frameworks, including FDA and IFRA guidelines, ensure high product quality and compliance across supply chains. It encourages manufacturers to invest in transparent sourcing and innovative ingredients. Growth in e-commerce and direct-to-consumer fragrance brands strengthens accessibility and market penetration. The region continues to prioritize R&D for biodegradable and hypoallergenic fragrance solutions to cater to evolving preferences.
Europe
Europe accounts for 32% market share, making it the leading region for the Fragrance Ingredients Market. The region is home to several global fragrance and flavor giants and benefits from centuries of expertise in perfumery. Strong demand for luxury perfumes, artisanal scents, and eco-certified products drives steady growth. It also faces strict REACH regulations and IFRA standards, pushing suppliers toward safer, low-allergen formulations. Consumer interest in sustainable and traceable ingredients leads to significant investment in bio-based chemistry. Markets such as France, Germany, and the U.K. lead innovation in niche fragrance offerings and support export demand globally. The region remains a hub for fragrance research, sustainability initiatives, and creative product development.
Asia-Pacific
Asia-Pacific captures 24% market share, representing one of the fastest-growing regions for the Fragrance Ingredients Market. Rising disposable incomes, rapid urbanization, and growing personal care adoption fuel demand for fragrances across China, India, Japan, and Southeast Asia. Local brands expand product portfolios, while international companies increase investments in regional manufacturing and partnerships. It benefits from expanding retail infrastructure, with strong growth in e-commerce and specialty beauty stores. Demand for natural and plant-based ingredients is rising, particularly among younger consumers seeking safer alternatives. The market also gains traction from growth in wellness products and aromatherapy. With rising middle-class populations, Asia-Pacific is set to become a major driver of long-term market growth.
Latin America
Latin America holds 9% market share, supported by growing demand for affordable perfumes, deodorants, and household care products. Brazil and Mexico lead consumption due to strong cultural affinity for fragrances. It experiences increasing adoption of mid-range and premium scents, driven by rising disposable incomes. Local manufacturers collaborate with global fragrance houses to introduce new and innovative formulations. Distribution channels expand through supermarkets, specialty retailers, and online platforms, improving access to diverse product lines. Consumers show interest in sustainable and natural ingredients, pushing brands to adjust portfolios. The region’s expanding young population supports steady fragrance consumption across categories.
Middle East & Africa
Middle East & Africa represents 7% market share, characterized by a deep-rooted cultural tradition of fragrance use. Demand for concentrated perfumes, attars, and incense products remains robust across GCC countries. It sees growing interest in luxury and niche fragrances, attracting international perfume brands to expand presence. Increasing tourism, rising incomes, and development of modern retail formats contribute to steady growth. Suppliers focus on sourcing natural ingredients aligned with regional preferences for oud, musk, and amber-based scents. Local production facilities are expanding to reduce dependence on imports and meet domestic demand. The region continues to offer long-term growth potential through premiumization and tailored product offerings.
Key Player Analysis
- Mane SA
- Kalpsutra Chemicals Pvt. Ltd.
- Robertet Group
- BASF SE
- Firmenich SA (Sentarom SA)
- Hasegawa Co. Ltd.
- S H Kelkar & Co. Limited
- Fine Fragrance Pvt. Ltd
- Givaudan
- International Flavors & Fragrances Inc.
Competitive Analysis
Competitive landscape of the Fragrance Ingredients Market is shaped by leading players such as Givaudan, Firmenich SA, International Flavors & Fragrances Inc., Mane SA, BASF SE, Robertet Group, S H Kelkar & Co. Limited, T.Hasegawa Co. Ltd., Fine Fragrance Pvt. Ltd, and Kalpsutra Chemicals Pvt. Ltd. These companies compete through innovation, sustainable product development, and global distribution strength. They focus on expanding their portfolios with bio-based aroma molecules, biodegradable fixatives, and low-allergen formulations to meet clean-label and regulatory demands. Strategic investments in R&D enable them to leverage green chemistry, biotechnological synthesis, and advanced extraction techniques for consistent quality and cost efficiency. Partnerships with personal care, cosmetics, and home care brands help strengthen supply chain relationships and secure long-term contracts. Many players adopt digital platforms for fragrance design, predictive analytics, and consumer trend mapping to reduce time-to-market. Expansion into emerging regions and capacity upgrades support growing demand while maintaining competitive positioning worldwide.
Recent Developments
- In September 2025, Givaudan unveiled Labdanum Absolute SIGNATURE, a new natural ingredient derived from hand-harvested cistus plants in Andalusia, Spain.
- In August 2025, T. Hasegawa USA introduced HASECITRUS, a natural technology to stabilize citrus flavors in beverages to resist oxidation.
- In April 2025, Mane SA developed ANTILLONE™, a 100 % natural ketone with a bold fruity signature.
- In March 2025, BASF SE launched Isobionics® Natural beta-Sinensal 20 and alpha-Humulene 90, fermentation-based aroma/flavor ingredients.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for natural and bio-based fragrance ingredients will continue to rise globally.
- Clean-label and allergen-free product formulations will become standard across industries.
- Biotechnology and green chemistry will play a key role in ingredient innovation.
- Personalized and niche fragrances will drive growth in premium and specialty segments.
- Digital fragrance design tools will speed up product development and customization.
- Sustainability and carbon-neutral production will gain priority for manufacturers.
- Emerging economies will witness rapid growth in personal care and home care demand.
- Strategic partnerships between global suppliers and local brands will expand distribution reach.
- Regulatory compliance will drive continuous reformulation and safer product development.
- Investment in R&D and capacity expansion will strengthen competitive positions worldwide.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Shift Toward Natural and Clean-Label Ingredients
Consumers are increasingly seeking products with natural, plant-based, and bio-derived fragrance ingredients, driving brands to reformulate with essential oils and botanical extracts. This trend is reinforced by demand for allergen-free and transparent labeling, pushing suppliers to innovate in clean and sustainable solutions.
Expansion of Personal Care and Home Care Applications
The use of fragrance ingredients is growing across personal care, home care, and fine fragrance products, with rising consumption of shampoos, soaps, air fresheners, and detergents. This broad application base ensures steady demand and supports market expansion.
Innovation in Sustainable and Biodegradable Solutions
Manufacturers are investing in green chemistry, bio-based aroma molecules, and biodegradable compounds to meet regulatory requirements and consumer expectations for eco-friendly products. This focus on sustainability differentiates brands and opens new premium market segments.
Stringent Regulatory Compliance and Quality Standards
Global regulations such as IFRA, REACH, and FDA guidelines require high standards of safety and transparency, compelling producers to invest in traceable sourcing and rigorous quality testing. Compliance builds consumer trust and supports long-term market growth.
Growth in Emerging Markets and E-Commerce Channels
Rising disposable incomes, urbanization, and expanding e-commerce in Asia-Pacific, Latin America, and Middle East & Africa are increasing access to fragrance products. Digital platforms and direct-to-consumer models accelerate market penetration and support niche fragrance launches.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Fragrance Ingredients, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Fragrance Ingredients market projected to grow between 2025 and 2032?
Which Fragrance Ingredients market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Fragrance Ingredients market?
Who are the leading companies in the Fragrance Ingredients market?
Which region commanded the largest share of the Fragrance Ingredients market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Natural
- 1.2.2 Synthetic
- 1.2.3 Essential Oils
- 1.2.4 Aroma Chemicals
- 1.3 By Application
- 1.3.1 Personal Care
- 1.3.2 Fine Fragrances
- 1.3.3 Home Care
- 1.3.4 Cosmetics
- 1.3.5 Fabric Care
- 1.3.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 10,828 million → 2032: USD 13,400.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Fragrance Ingredients Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Fragrance Ingredients Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Fragrance Ingredients Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Fragrance Ingredients Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Fragrance Ingredients Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Fragrance Ingredients Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Fragrance Ingredients Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Fragrance Ingredients Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 10,828 million → 2032: USD 13,400.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Fragrance Ingredients Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Natural
- 12.3.7.2 Synthetic
- 12.3.7.3 Essential Oils
- 12.3.7.4 Aroma Chemicals
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Personal Care
- 12.4.7.2 Fine Fragrances
- 12.4.7.3 Home Care
- 12.4.7.4 Cosmetics
- 12.4.7.5 Fabric Care
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Fragrance Ingredients End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Fragrance Ingredients Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Fragrance Ingredients Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Fragrance Ingredients Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Givaudan
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Firmenich SA
- 18.4 International Flavors & Fragrances Inc.
- 18.5 Mane SA
- 18.6 BASF SE
- 18.7 Robertet Group
- 18.8 S H Kelkar & Co. Limited
- 18.9 T. Hasegawa Co. Ltd.
- 18.10 Fine Fragrance Pvt. Ltd
- 18.11 Kalpsutra Chemicals Pvt. Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

