
Market Overview
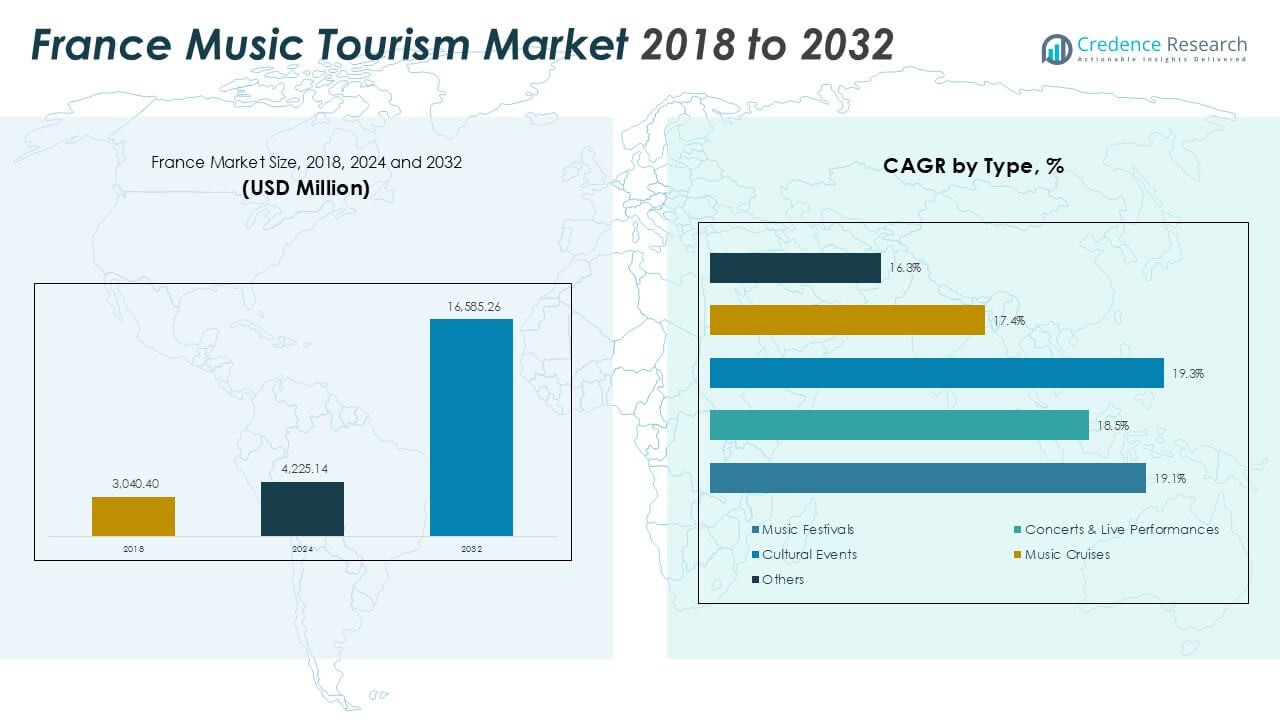
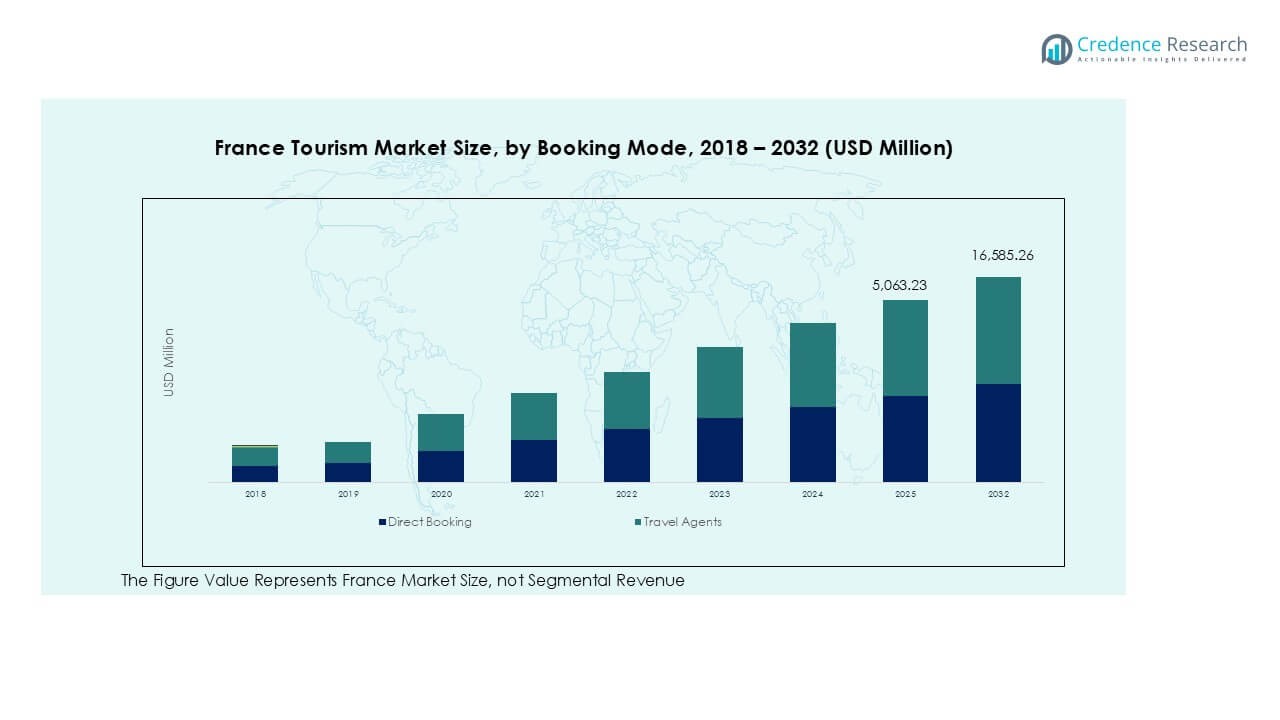
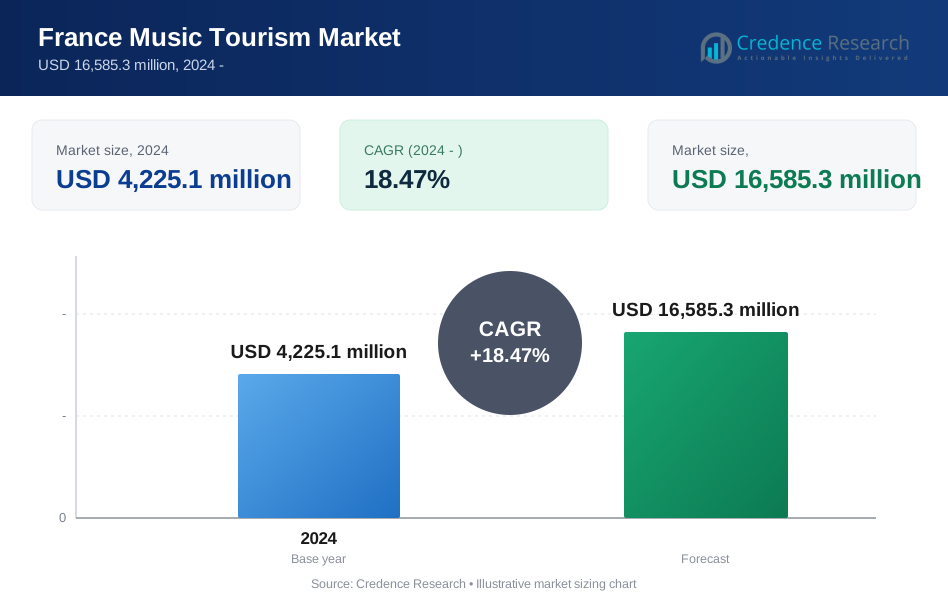
France Music Tourism market size was valued at USD 3,040.4 million in 2018, increased to USD 4,225.1 million in 2024, and is anticipated to reach USD 16,585.3 million by 2032, growing at a CAGR of 18.47% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| France Music Tourism market Size 2024 | USD 4,225.1 Million |
| France Music Tourism market, CAGR | 18.47% |
| France Music Tourism market Size 2032 | USD 16,585.3 Million |
The France music tourism market is led by Live Nation France, AEG Presents France, Olympia Production, and Alias Production, which collectively dominate the event and festival landscape through large-scale concert management and international artist collaborations. Supporting players such as Auguri Productions, Gérard Drouot Productions, and Nous Productions contribute to the diversity of regional and niche music events. Ticketmaster France and France Billet strengthen market accessibility through advanced ticketing systems and digital integration. Southern France leads the market with a 30% share, driven by its Mediterranean appeal, international connectivity, and renowned festivals like the Nice Jazz Festival and Les Déferlantes, attracting both domestic and global audiences.
Market Insights
- The France Music Tourism market was valued at USD 4,225.1 million in 2024 and is expected to reach USD 16,585.3 million by 2032, growing at a CAGR of 18.47% during the forecast period.
- Market growth is driven by the rising popularity of large-scale music festivals such as Hellfest and Les Vieilles Charrues, supported by government funding and regional tourism initiatives.
- Key trends include the integration of digital platforms, sustainable event management practices, and growing interest in experiential travel among younger audiences.
- The competitive landscape features major promoters like Live Nation France, AEG Presents France, and Olympia Production, focusing on digital engagement and artist collaborations.
- Southern France leads with a 30% regional share, followed by Eastern France at 20% and Northern France at 18%, while the music festivals segment dominates with a 41% market share in 2024.
Market Segmentation Analysis:
By Type
The music festivals segment dominated the France Music Tourism market in 2024 with a 41% share. France’s globally recognized events, such as Les Vieilles Charrues and Hellfest, attract millions of domestic and international visitors annually. The strong cultural identity of these festivals, combined with government support for creative industries, sustains segment growth. Rising demand for experiential travel and digital promotion through streaming and social media platforms further boosts attendance. The growth of boutique and eco-friendly festivals also contributes to the segment’s expansion across regional destinations.
- For instance, Hellfest in Clisson hosted over 240,000 attendees in 2024, featuring more than 180 international metal bands and generating over 12,000 temporary jobs according to festival organizers.
By Age Group
The 18–34 years segment held the largest market share of 46% in 2024. This age group shows the highest engagement in live music experiences and festival tourism, driven by lifestyle preferences and digital influence. Millennials and Gen Z travelers prioritize immersive cultural experiences and music-based events during leisure trips. The integration of travel packages with concert tours and music festivals strengthens participation among younger audiences. Moreover, affordable travel options and extensive rail connectivity across France enhance accessibility for this demographic, encouraging repeat visitation.
By End-User
The leisure travelers segment led the France Music Tourism market with a 49% share in 2024. Growing interest in combining cultural exploration with entertainment drives participation in concerts, local music events, and heritage festivals. Leisure travelers seek authentic and memorable experiences that reflect regional traditions and contemporary music culture. Destination marketing organizations are increasingly promoting music-centric itineraries that include venue tours and local performances. Rising disposable incomes, coupled with improved hospitality infrastructure and flexible booking options, further stimulate market growth within this category.
- For instance, in 2024, Accor, as the main sponsor of Paris Saint-Germain football club and with naming rights to the Accor Arena in Paris, leveraged its "ALL - Accor Live Limitless" loyalty program to offer music-related rewards.
Key Growth Drivers
Growing Popularity of Music Festivals and Live Events
The strong appeal of large-scale music festivals is one of the primary drivers of France’s music tourism growth. Events like Hellfest, Les Vieilles Charrues, and Rock en Seine attract millions of domestic and international visitors annually. The combination of world-class performances, scenic venues, and cultural immersion creates a compelling travel experience. Supportive policies from tourism boards and local governments further enhance event accessibility and logistics. Growing interest in sustainable and boutique festivals also diversifies attendance, while the inclusion of digital ticketing, live streaming, and social media engagement expands audience reach beyond physical attendance.
- For instance, the Les Vieilles Charrues festival in 2024 hosted more than 75 artists over four days and was attended by approximately 250,000 people.
Government Support and Cultural Promotion
France’s long-standing commitment to promoting cultural tourism significantly strengthens the music tourism ecosystem. The government invests heavily in maintaining historical venues, developing event infrastructure, and supporting regional music festivals. Initiatives under the Ministry of Culture and local tourism bodies aim to enhance France’s image as a global music and arts hub. Tax incentives for cultural organizations and partnerships with private event companies encourage international collaborations. These programs ensure that music tourism not only boosts visitor numbers but also contributes to regional development, job creation, and heritage preservation.
- For instance, in 2024, the French Ministry of Culture saw a significant budget increase, with €4.466 billion allocated for the Culture and Media missions and €4.025 billion for Public Audiovisual. The Centre National de la Musique (CNM) provided €66.7 million in selective aid in 2024, including €17.7 million specifically for venues and festivals.
Expanding International Tourism and Connectivity
France’s robust transportation network and global connectivity play a vital role in music tourism growth. Paris, Lyon, and Marseille serve as major entry points for visitors attending festivals and concerts. Efficient high-speed rail and affordable airline services enable easy domestic and cross-border travel. The post-pandemic rebound in tourism, combined with digital promotion by event organizers, has increased international attendance. Packages combining accommodation, travel, and event tickets have simplified visitor planning. This infrastructure-driven convenience positions France as one of Europe’s most accessible and attractive destinations for music-based travel experiences.
Key Trends & Opportunities
Rise of Experiential and Sustainable Tourism
A growing trend toward immersive, experience-driven travel is reshaping France’s music tourism landscape. Travelers increasingly prefer events offering cultural workshops, local gastronomy, and sustainable festival models. Organizers are adopting eco-friendly practices such as waste reduction, renewable power use, and carbon offset programs. This aligns with global sustainability goals and appeals to environmentally conscious audiences. Destinations are also promoting off-season or rural festivals to reduce overcrowding and distribute economic benefits across regions. The combination of authenticity, sustainability, and cultural depth is redefining visitor engagement in France’s music tourism sector.
- For instance, the We Love Green Festival powered its 2024 edition with 100% renewable energy. In 2024, the festival recycled 78% of the 130 tons of waste collected. It achieved its ISO 20121 certification for sustainable event management in 2023. The festival consulted with the French Environment and Energy Management Agency (ADEME) on a sustainable plan for the 2024 Olympic Games but was not partnered with them for the festival's own 2024 certification.
Integration of Technology and Digital Engagement
Digital transformation is creating new opportunities for event organizers and travelers alike. Online ticketing platforms, mobile event guides, and virtual concert experiences enhance accessibility and convenience. Social media and influencer marketing campaigns attract younger audiences, especially in the 18–34 age group. Technologies such as augmented reality (AR) and virtual reality (VR) are being tested for pre-event engagement and live streaming. Moreover, AI-powered personalization tools are helping travel platforms recommend music-based itineraries. This technological integration not only improves event experience but also expands audience reach beyond traditional concert-goers.
Key Challenges
Seasonal Concentration of Events
One of the major challenges for France’s music tourism market is the high seasonality of major events. Most festivals and outdoor concerts occur between May and September, leading to concentrated visitor inflows. This seasonal pattern strains accommodation, transportation, and local infrastructure during peak months while leaving resources underused in the off-season. Smaller venues and local governments face difficulties maintaining year-round engagement. Developing indoor festivals, winter tours, and digital event formats could mitigate this imbalance and sustain economic activity throughout the year.
Rising Operational Costs and Infrastructure Pressure
Growing attendance and heightened safety regulations have significantly increased operational costs for event organizers. Expenses related to crowd management, security, insurance, and environmental compliance continue to rise. Additionally, hosting large-scale music events in urban centers often leads to congestion and higher logistics costs. Smaller regional festivals face financial strain due to limited sponsorship and fluctuating ticket revenues. Infrastructure upgrades, including transport and waste management, are essential to handle visitor surges sustainably. Without targeted investment, these rising costs may limit new event development and regional diversification.
Regional Analysis
Northern France
Northern France contributes roughly 15 %–18 % of France’s music tourism market. The region’s proximity to Belgium and England boosts cross‐border attendance at festivals around Lille, Dunkirk, and Nord. Its dense population centers support numerous concerts and live events across small and mid-sized venues. Local festivals in Hauts-de-France attract both regional and foreign tourists. Improved rail connectivity from Paris and international hubs enables easy access. Strong institutional support from local governments ensures festival infrastructure and scheduling ecosystem.
Western France
Western France holds an estimated 12 %–14 % share of music tourism. Regions like Brittany and Pays de la Loire host coastal and rural festivals, making them seasonal hotspots. The Atlantic coastline’s allure draws tourists who combine beach and music travel. Communities often promote local genres, folk music, and regional lineups. Festival circuits around Nantes, Rennes, and La Rochelle integrate with cultural tourism routes. Limited air connectivity is offset by efficient regional rail and road access, helping sustain visitor inflows during festival months.
Southern France
Southern France commands the largest regional share—approximately 28 %–30 % of music tourism. The Provence-Alpes-Côte d’Azur region (PACA), Occitanie, and Nouvelle-Aquitaine host marquee events like Nice Jazz Festival, Fête de la Musique along the Riviera, and rural summer festivals. The Mediterranean climate allows extended outdoor seasons. International attendees favor festival packages linking coastal relaxation and performances. Airports at Marseille, Nice, and Montpellier facilitate access. Local and regional support strongly promotes cultural tourism, increasing festival capacities and regional benefits.
Central France
Central France captures around 10 %–12 % of the market. The Loire Valley, Auvergne, Centre-Val de Loire, and Bourgogne coordinate smaller festivals, cultural concerts, and heritage music experiences. These events appeal to travelers seeking off-beat, scenic music tourism beyond urban centers. Though less internationally prominent, central festivals benefit from proximity to Paris via high-speed rail. Cultural institutions support concerts in historic towns like Bourges or Orléans. Budget travelers and domestic tourists often explore multiple regions, linking central attractions with adjacent festival circuits.
Eastern France
Eastern France holds approximately 18 %–20 % share. Regions like Grand Est, Bourgogne-Franche-Comté, and Alsace host cross-border festivals and concerts that draw German, Swiss, Belgian visitors. Cities such as Strasbourg, Nancy, and Lyon (border area) serve as nodes for international tours. Traditional and classical music festivals in towns like Colmar and Mulhouse attract niche audiences. Strong connectivity to Germany, Switzerland, and Northern Italy helps draw foreign music tourists. Regional cultural agencies invest in festival infrastructure and cross-border collaborations to boost attendance.
Market Segmentations:
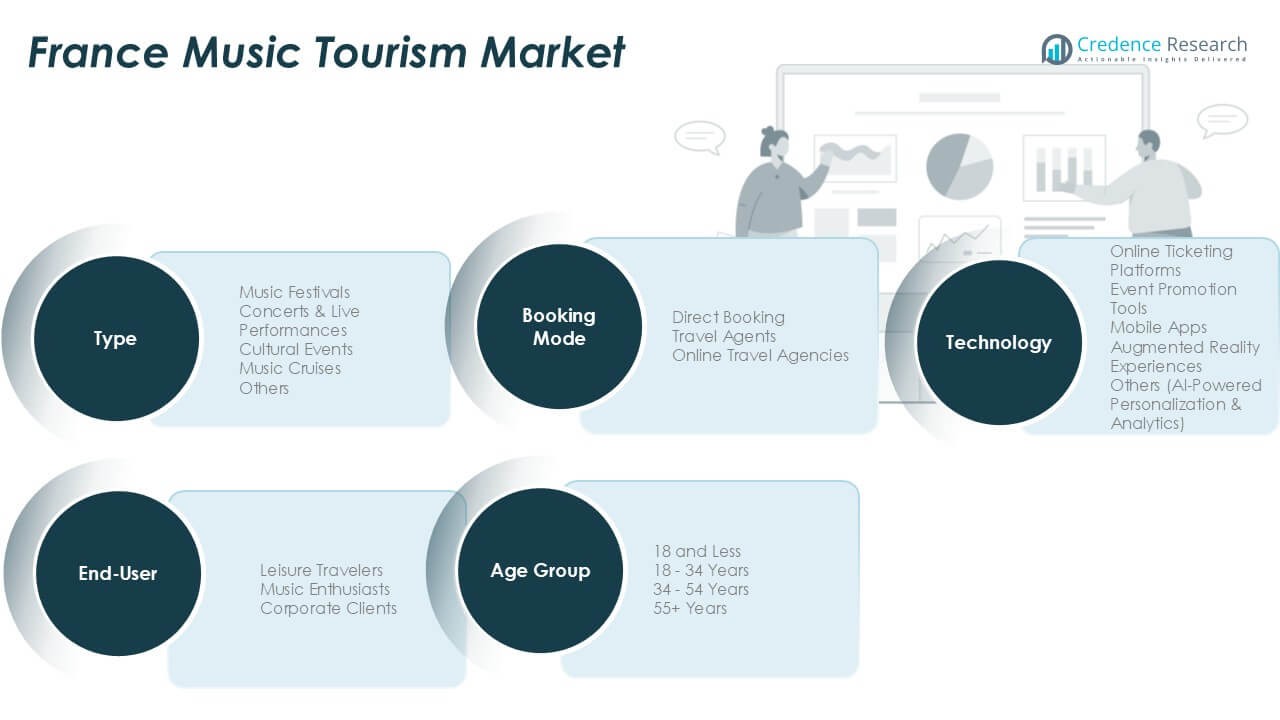
By Type
- Music Festivals
- Concerts & Live Performances
- Cultural Events
- Music Cruises
- Others
By Age Group
- 18 and Less
- 18–34 Years
- 34–54 Years
- 55+ Years
By End-User
- Leisure Travelers
- Music Enthusiasts
- Corporate Clients
By Technology
- Online Ticketing Platforms
- Event Promotion Tools
- Mobile Apps
- Augmented Reality Experiences
- Others (AI-Powered Personalization & Analytics)
By Booking Mode
- Direct Booking
- Travel Agents
- Online Travel Agencies
By Geography
- Northern France
- Western France
- Southern France
- Central France
- Eastern France
Competitive Landscape
The France music tourism market is moderately concentrated, with major players including Live Nation France, AEG Presents France, Olympia Production, and Alias Production dominating large-scale event organization and concert promotion. These companies manage international tours, regional festivals, and collaborations with tourism boards to attract global audiences. Mid-sized firms such as Auguri Productions, Nous Productions, and Radical Production strengthen the competitive ecosystem through diverse event portfolios and niche festival management. Ticketing leaders Ticketmaster France and France Billet provide vital distribution and analytics support, improving market efficiency. Companies increasingly focus on digital ticketing, sustainability initiatives, and hybrid festival formats to expand audience reach. Strategic partnerships with local authorities, hospitality providers, and streaming platforms are enhancing revenue diversification and visitor experience. The competition centers on event exclusivity, artist lineup strength, and technological integration, with leading promoters investing heavily in brand visibility, online engagement, and cross-regional expansion to maintain market dominance.
Key Player Analysis
- Live Nation France
- AEG Presents France
- Olympia Production
- Alias Production
- Auguri Productions
- Gérard Drouot Productions
- Nous Productions
- Radical Production
- Yuma Productions
- Bleu Citron
- Ticketmaster France
- France Billet
Recent Developments
- In February 2025, Busan Concert Hall launched its official website to provide classical music enthusiasts with a seamless platform for ticket reservations, venue rentals, and academy schedules. Designed with responsive technology, the site ensures accessibility across devices and features a mobile ticketing service for quick entry via barcode scanning. The initiative enhances convenience and enriches the cultural experience for visitors in Busan.
- In August 2024, Brightline launched "The Big Concert Sweepstakes," offering tickets to Taylor Swift's sold-out Miami concert on October 20. The prize included two concert tickets, four round-trip Brightline tickets on a special "Tay-keover Sing-Along" train, and exclusive lounge perks. Participants entered by following Brightline on Instagram and signing a rail safety pledge, with the winner announced during Rail Safety Week in late September.
- In May 2024, Live Nation brought back its annual Concert Week promotion, offering USD 25 all-in tickets for over 5,000 shows across North America. Featuring artists like Janet Jackson and 21 Savage, the week-long event made live music more accessible to fans. Tickets, available from May 8 to May 14, could be purchased online without a promo code, allowing fans to enjoy significant savings on select concerts and festivals. The initiative aimed to enhance the summer touring season with budget-friendly options.
Report Coverage
The research report offers an in-depth analysis based on Type, Age Group, End-User, Technology, Booking Mode and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- France is expected to remain a leading European destination for music-based tourism by 2032.
- Growth in digital ticketing and virtual concert experiences will enhance visitor accessibility.
- Increasing collaboration between event organizers and tourism boards will expand international attendance.
- Sustainable and eco-friendly festival models will gain stronger adoption across major regions.
- Boutique and niche festivals will grow as travelers seek authentic and localized experiences.
- Hybrid event formats combining live and digital elements will attract younger audiences.
- Regional cities beyond Paris will emerge as key hubs for cultural and music events.
- Government investment in cultural infrastructure and promotion will continue supporting sector expansion.
- Rising use of AI and analytics will improve audience targeting and event management efficiency.
- Expanding air and rail connectivity will strengthen France’s position as a global music tourism gateway.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the France Music Tourism market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the France Music Tourism market projected to grow between 2025 and 2032?
Which France Music Tourism market segment held the largest share in 2024?
What are the primary factors fueling the growth of the France Music Tourism market?
Who are the leading companies in the France Music Tourism market?
Which region commanded the largest share of the France Music Tourism market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 France Music Tourism Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global France Music Tourism Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 4,225.1 million → forecast year: USD 16,585.3 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 France Music Tourism Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. France Music Tourism Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 France Music Tourism Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 France Music Tourism Market Drivers
- 3.3 France Music Tourism Market Restraints & Challenges
- 3.4 France Music Tourism Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 France Music Tourism Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 France Music Tourism Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, France Music Tourism category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 France Music Tourism Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. France Music Tourism Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the France Music Tourism market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 France Music Tourism Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 France Music Tourism Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 France Music Tourism Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in France Music Tourism (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New France Music Tourism Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global France Music Tourism Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America France Music Tourism Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe France Music Tourism Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific France Music Tourism Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America France Music Tourism Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East France Music Tourism Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa France Music Tourism Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. France Music Tourism Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer