
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| France Plastic Welding Equipment Market Size 2024 | USD 418.63 million |
| France Plastic Welding Equipment Market, CAGR | 6.98% |
| France Plastic Welding Equipment Market Size 2032 | USD 718.13 million |
Market Overview
France Plastic Welding Equipment market size was valued at USD 418.63 million in 2024 and is anticipated to reach USD 718.13 million by 2032, at a CAGR of 6.98% during the forecast period (2024-2032).
The France plastic welding equipment market is experiencing steady growth driven by increasing demand for durable and cost-effective plastic joining solutions across various industries, including automotive, packaging, electronics, and construction. The rising emphasis on lightweight and fuel-efficient vehicles has accelerated the adoption of plastic components, thereby boosting the need for advanced welding technologies. Additionally, the expansion of the renewable energy sector and infrastructure development projects further contribute to market expansion. Technological advancements, such as automation and integration of IoT in welding systems, are enhancing operational efficiency and precision, attracting significant investments. Furthermore, stringent environmental regulations are encouraging manufacturers to adopt energy-efficient and low-emission welding equipment, promoting sustainability. The trend toward customized, application-specific equipment and the growing popularity of ultrasonic and laser welding techniques also support the market's upward trajectory. Collectively, these factors underscore a positive outlook for the plastic welding equipment market in France over the forecast period.
The geographical landscape of the France plastic welding equipment market is influenced by regional industrial strengths, with Northern France leading due to its strong automotive and manufacturing sectors. Southern France follows with significant demand driven by the aerospace, renewable energy, and medical device industries. Eastern France benefits from its proximity to neighboring countries and its automotive manufacturing hubs, while Western France thrives on packaging and agricultural sectors. Key players in the market include Leister Technologies AG, a leader in hot air and extrusion welding; Herrmann Ultraschalltechnik GmbH & Co. KG, known for ultrasonic welding solutions; Bielomatik Leuze GmbH & Co. KG, offering diverse welding technologies; Frimo Group GmbH, specializing in automotive applications; and RITMO S.p.A., which provides fusion welding equipment. Other important players include LPKF Laser & Electronics AG, Telsonic AG, and Mecasonic Group, contributing significantly to the technological advancement and market competition in France.
Market Insights
- The France plastic welding equipment market was valued at USD 418.63 million in 2024 and is projected to reach USD 718.13 million by 2032, growing at a CAGR of 6.98% during the forecast period (2024-2032).
- The global plastic welding equipment market was valued at USD 11,340.00 million in 2024 and is projected to reach USD 19,842.36 million by 2032, growing at a CAGR of 7.24% from 2024 to 2032.
- Increasing demand from industries like automotive, electronics, and medical devices is a significant driver for market growth.
- Technological advancements, including automation and IoT integration, are improving efficiency and precision in plastic welding.
- The shift towards sustainable and energy-efficient solutions is driving innovation and adoption of eco-friendly welding equipment.
- Competition is intensifying with key players such as Leister Technologies, Herrmann Ultraschalltechnik, and Frimo Group driving technological innovations and market expansion.
- Market restraints include high initial costs of advanced systems and the technical complexity of welding processes, which may deter smaller businesses.
- Regionally, Northern France leads with its robust automotive sector, followed by Southern France's aerospace and medical device industries.
Report scope
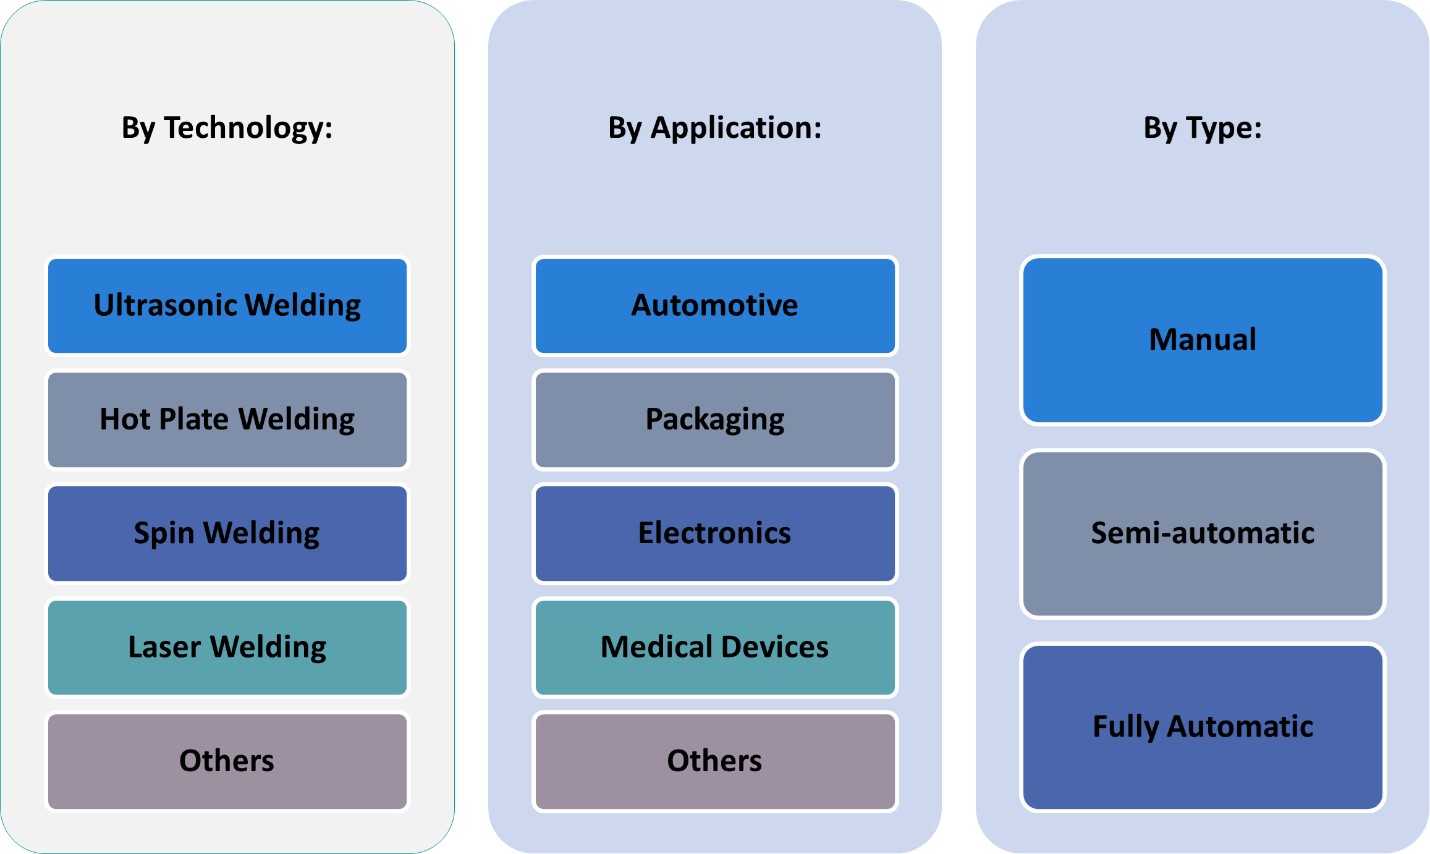
This report segments the France Plastic Welding Equipment Market as follows:
Market Drivers
Rising Demand from the Automotive Industry
One of the key drivers fueling the growth of the plastic welding equipment market in France is the increasing demand from the automotive sector. For instance, the French Automotive Industry Association highlights the growing use of plastic components in lightweight vehicle manufacturing to improve fuel efficiency and reduce emissions. These components require reliable and durable joining methods, significantly boosting the adoption of plastic welding technologies. Moreover, with the expansion of electric vehicle (EV) production in France, there is a heightened need for precision welding in battery housings, fluid reservoirs, and interior components. This growing reliance on plastic materials for both aesthetic and functional parts in vehicles is expected to sustain the demand for advanced welding equipment across the sector.
Technological Advancements and Automation
The integration of advanced technologies such as automation, robotics, and Industry 4.0 solutions into plastic welding processes is significantly transforming the market landscape. For instance, the European Welding Association emphasizes the adoption of IoT-enabled systems for real-time monitoring and predictive maintenance. Manufacturers are increasingly adopting automated welding equipment to enhance productivity, reduce labor costs, and achieve consistent weld quality. Technologies like ultrasonic, laser, and hot plate welding are gaining traction due to their ability to deliver high precision and speed. In addition, the incorporation of IoT-enabled systems allows real-time monitoring, predictive maintenance, and remote operation of welding equipment. These innovations not only improve operational efficiency but also align with modern manufacturing practices, making high-performance plastic welding solutions more accessible and appealing to industrial users in France.
Government Regulations and Sustainability Initiatives
Environmental regulations and sustainability goals are playing a pivotal role in shaping the plastic welding equipment market in France. The French government’s push for sustainable manufacturing practices and reduction of greenhouse gas emissions has encouraged industries to adopt energy-efficient equipment. Plastic welding methods, especially those that minimize material waste and lower energy consumption, are increasingly favored as part of this green transition. Furthermore, manufacturers are investing in recyclable and biodegradable plastic materials, which require specialized welding techniques. As environmental compliance becomes more stringent, the demand for innovative welding equipment that supports sustainable production is expected to rise, creating new growth opportunities for market players.
Expansion of Key End-Use Industries
Beyond the automotive sector, the expansion of other key industries such as packaging, electronics, medical devices, and construction is also contributing to market growth. In the packaging industry, the need for leak-proof, durable seals has driven the adoption of plastic welding solutions. The electronics industry, with its demand for miniaturized and thermally sensitive components, benefits from precise, low-heat welding techniques such as ultrasonic welding. Additionally, the rise in medical-grade plastic usage in healthcare applications has spurred the need for hygienic and contamination-free welding solutions. Meanwhile, the construction sector is utilizing plastic welding for pipes, insulation materials, and roofing membranes. This broadening application landscape ensures a stable and growing demand for plastic welding equipment across diverse segments of the French economy.
Market Trends
Technological Innovation Driving Equipment Modernization
One of the most prominent trends in the France plastic welding equipment market is the rapid integration of advanced technologies to enhance productivity, precision, and efficiency. For instance, the French government's French Tech 2030 program supports innovation in manufacturing technologies, including IoT-enabled systems for real-time monitoring and predictive maintenance. Manufacturers are increasingly investing in automated and digitally controlled welding systems, aligning with Industry 4.0 standards. In addition, innovations such as laser and ultrasonic welding are gaining popularity due to their ability to offer high-speed, non-contact, and energy-efficient solutions. The shift toward automation and smart welding solutions not only reduces human error but also ensures consistent quality across high-volume production. As French industries strive for higher manufacturing standards, the demand for cutting-edge, software-integrated welding equipment continues to rise, transforming traditional processes into more intelligent and streamlined operations.
Growing Application Scope in Automotive and Electronics Industries
The increasing use of plastic components across the automotive and electronics sectors has fueled a growing need for reliable plastic welding technologies. For instance, the French Automotive Industry Association highlights the adoption of lightweight plastic materials in vehicle manufacturing to meet stringent emissions regulations. As a result, there is a growing preference for plastic welding equipment that can handle complex geometries and maintain structural integrity in applications such as fuel tanks, bumpers, dashboards, and electric vehicle battery components. Meanwhile, the electronics industry demands highly precise and low-heat welding techniques for compact and delicate devices. Laser plastic welding, in particular, is gaining ground due to its ability to deliver fine, clean joints without compromising surrounding materials. These industry-specific requirements are prompting the development of specialized welding machines, encouraging manufacturers to diversify their equipment offerings to meet diverse production needs.
Sustainability and Energy Efficiency at the Forefront
Sustainability has emerged as a central theme in the France plastic welding equipment market. With increasing regulatory pressure to reduce carbon emissions and energy consumption, manufacturers and end-users are prioritizing eco-friendly welding technologies. Equipment that minimizes waste, consumes less power, and supports the use of recyclable materials is becoming more desirable. In response, leading players are designing machines that comply with environmental standards while maintaining high performance. Additionally, techniques such as hot gas and infrared welding are being optimized to reduce thermal input and material degradation. French government policies supporting green manufacturing practices are reinforcing this trend, pushing the industry toward more responsible and sustainable operations. Companies investing in environmentally conscious solutions are not only meeting compliance requirements but also enhancing their reputation and market competitiveness.
Customization and Versatility in Welding Solutions
As end-user demands grow increasingly complex, there is a marked shift toward customizable and flexible plastic welding solutions. Industries now require equipment capable of adapting to specific product designs, materials, and production volumes. This has led to the development of modular systems that can be tailored for different welding methods, such as vibration, spin, or hot plate welding, based on application needs. Manufacturers are also demanding systems that are easy to reconfigure for new production runs, enabling faster changeovers and reduced downtime. The ability to offer customized, application-specific machines gives equipment providers a significant competitive edge in the French market. This trend is particularly pronounced among small- and medium-sized enterprises seeking to remain agile and responsive to evolving customer expectations without incurring the cost of fully automated assembly lines.
Market Challenges Analysis
High Initial Investment and Cost Sensitivity Among SMEs
One of the primary challenges facing the France plastic welding equipment market is the high initial investment associated with advanced welding systems. For instance, the Bpifrance Le Lab survey highlights that SMEs in France often face financial constraints, which limit their ability to invest in high-tech equipment despite its long-term benefits. While modern technologies such as laser and ultrasonic welding offer superior precision and efficiency, they come with substantial capital costs, including the need for specialized software, training, and integration with existing production lines. This financial barrier is particularly pronounced among small- and medium-sized enterprises (SMEs), which make up a significant portion of France's manufacturing sector. Additionally, the lack of in-house technical expertise can further discourage investment in sophisticated welding systems, hindering market penetration and slowing the adoption rate of next-generation solutions.
Technical Complexity and Standardization Issues
Another key challenge is the technical complexity associated with various plastic welding processes and the lack of standardized practices across different industries. The effectiveness of plastic welding techniques is highly dependent on material type, part geometry, and application-specific requirements. As a result, equipment operators and engineers must possess specialized knowledge to ensure optimal weld strength and quality. However, the industry faces a shortage of skilled technicians trained in the nuances of each welding method, particularly as newer technologies enter the market. In addition, the absence of universally accepted standards for plastic welding processes can lead to inconsistencies in product quality, testing procedures, and regulatory compliance. This lack of harmonization across sectors not only complicates quality assurance but also creates uncertainty among end-users, who may be hesitant to adopt new methods without clear guidelines and proven outcomes. Addressing these technical and regulatory gaps will be essential to ensure sustained growth and reliability in the French plastic welding equipment market.
Market Opportunities
The France plastic welding equipment market presents significant growth opportunities driven by expanding applications in emerging industries and increasing demand for sustainable manufacturing solutions. As sectors such as electric vehicles (EVs), renewable energy, and medical devices continue to grow, the need for precision-engineered plastic components and reliable welding technologies is also rising. In particular, the EV sector offers immense potential, as manufacturers require advanced plastic welding methods for assembling battery housings, thermal management systems, and lightweight structural components. Similarly, the medical and pharmaceutical industries are driving demand for hygienic and non-contaminating welding solutions, such as ultrasonic and laser welding, to assemble critical single-use plastic devices. This shift toward high-value, application-specific equipment is expected to open new avenues for manufacturers and suppliers willing to invest in innovation and customization.
Additionally, the growing emphasis on sustainability and energy efficiency across French industries offers a favorable environment for the adoption of next-generation plastic welding equipment. Companies are actively seeking solutions that minimize waste, reduce energy consumption, and support the use of recyclable or biodegradable materials. This creates opportunities for equipment manufacturers to develop and market environmentally friendly systems that comply with evolving regulatory standards and support circular economy goals. Furthermore, the increasing integration of automation and digitalization in manufacturing processes presents an opportunity to offer smart, IoT-enabled plastic welding systems that deliver real-time monitoring, predictive maintenance, and enhanced process control. As end-users in France become more focused on operational efficiency, product traceability, and quality assurance, equipment providers that can deliver comprehensive, tech-driven solutions stand to gain a competitive advantage. Overall, the convergence of industry transformation, environmental priorities, and technological progress positions the plastic welding equipment market in France for sustained opportunity and strategic growth.
Market Segmentation Analysis:
By Type:
The France plastic welding equipment market can be segmented based on the type of systems used, which includes manual, semi-automatic, and fully automatic solutions. Manual welding systems are commonly used in low-volume, simple applications where flexibility and cost-efficiency are essential. These systems require skilled operators and are typically employed by small and medium-sized enterprises (SMEs) or for prototyping purposes. On the other hand, semi-automatic welding systems offer a balance between flexibility and efficiency, requiring less human intervention while maintaining a certain level of operator control. These systems are widely adopted in industries with moderate production volumes, where precision and speed are important but full automation may not be cost-effective. The fully automatic welding systems segment is experiencing significant growth, driven by industries that require high-volume, high-precision welding with minimal human input, such as the automotive and electronics sectors. These systems are often integrated with advanced robotics and IoT capabilities to offer increased productivity, reduced error rates, and greater consistency, particularly in large-scale manufacturing operations.
By Application:
The market for plastic welding equipment in France is also segmented by application, with significant growth driven by industries such as electronics, packaging, automotive, and medical devices. The electronics sector has seen increased demand for plastic welding due to the need for precise, reliable, and high-speed assembly of components like casings, connectors, and printed circuit boards. In the packaging industry, plastic welding technologies are crucial for ensuring durable, leak-proof seals in products ranging from food containers to industrial packaging. The automotive sector remains a key driver, with the demand for lightweight, durable plastic parts for both internal components and structural elements, particularly in electric vehicles (EVs), where welding is used to assemble battery housings and other critical parts. The medical devices segment also presents substantial opportunities, as plastic welding is essential for assembling sterile, non-contaminating devices such as syringes, IV bags, and diagnostic equipment. Collectively, these diverse applications are fostering a broad, dynamic demand for advanced plastic welding solutions across multiple industries in France.
Segments:
Based on Type:
- Manual
- Semi-automatic
- Fully Automatic
Based on Application:
- Electronics
- Packaging
- Automotive
- Medical Devices
- Others
Based on Technology:
- Ultrasonic Welding
- Hot Plate Welding
- Spin Welding
- Laser Welding
- Others
Based on the Geography:
- Northern France
- Southern France
- Eastern France
- Western France
Regional Analysis
Northern France
Northern France holds the largest share, accounting for approximately 35% of the market. This dominance is largely attributed to the region's industrial base, with major manufacturing hubs in cities such as Lille, Roubaix, and Dunkirk. Northern France is home to a large concentration of industries, particularly in automotive manufacturing, electronics, and heavy machinery, all of which rely heavily on plastic welding technologies. The region’s well-established infrastructure and proximity to key industrial centers in neighboring countries further strengthen its position as a key player in the market.
Southern France
In Southern France, the plastic welding equipment market captures around 25% of the total market share. The region is a prominent center for the aerospace, renewable energy, and medical device sectors. The growth of these industries, particularly in cities such as Toulouse and Marseille, has led to an increased demand for plastic welding solutions. Southern France is also known for its strong presence in the packaging industry, where plastic welding is used for packaging materials such as containers and film. Furthermore, the region's focus on sustainable and energy-efficient production has boosted the demand for advanced welding systems that support eco-friendly initiatives, further solidifying the region's market presence.
Eastern France
Eastern France, with its strategic location near the German and Swiss borders, holds a 20% share of the plastic welding equipment market. The region’s manufacturing and automotive industries are significant contributors to the demand for plastic welding equipment. Cities like Strasbourg and Mulhouse are known for their automotive manufacturing facilities, where high-precision plastic welding is crucial for assembling automotive components. The region also benefits from a robust industrial base that includes packaging, electronics, and healthcare manufacturing. Additionally, the presence of large multinational corporations in this area is driving the adoption of automated and high-precision welding solutions, particularly in industries requiring high standards for product safety and quality.
Western France
Western France contributes about 20% of the total market share, with a strong focus on the agricultural, food processing, and packaging industries. Cities such as Nantes and Rennes are central to the region’s industrial activities, with a significant concentration of food and beverage companies that rely on plastic welding for sealing and packaging. The region's growing emphasis on sustainable production practices has led to increased adoption of energy-efficient plastic welding systems. Western France also benefits from a flourishing small and medium-sized enterprise (SME) sector, where manual and semi-automatic plastic welding equipment is in demand due to its cost-effectiveness and flexibility. As the region continues to focus on green manufacturing solutions, the market for plastic welding equipment is poised for steady growth in the coming years.
Key Player Analysis
- Leister Technologies AG
- Herrmann Ultraschalltechnik GmbH & Co. KG
- Bielomatik Leuze GmbH & Co. KG
- Frimo Group GmbH
- RITMO S.p.A.
- LPKF Laser & Electronics AG
- Telsonic AG
- HPT Hochwertige Plastikteile GmbH
- Mecasonic Group
- CEMAS Elettra
Competitive Analysis
The France plastic welding equipment market is highly competitive, with several prominent players driving innovation and technological advancements. Leading companies in the market include Leister Technologies AG, Herrmann Ultraschalltechnik GmbH & Co. KG, Bielomatik Leuze GmbH & Co. KG, Frimo Group GmbH, RITMO S.p.A., LPKF Laser & Electronics AG, Telsonic AG, HPT Hochwertige Plastikteile GmbH, Mecasonic Group, and CEMAS Elettra. Companies are increasingly integrating automation, IoT, and digital technologies into their welding systems to enhance operational efficiency, reduce downtime, and improve product quality. This trend toward automation and smart manufacturing is becoming a key differentiator in the market. In terms of market strategies, players are focusing on customization and flexibility, offering tailored solutions for diverse industries such as automotive, electronics, medical devices, and packaging. Companies are also expanding their service portfolios, including maintenance and training programs, to strengthen customer relationships and create long-term value. Competitive pressure is rising as firms strive to meet the growing demand for eco-friendly and energy-efficient welding equipment, in line with sustainability initiatives and regulatory requirements. The increasing trend towards lightweight and recyclable materials is prompting companies to innovate new welding methods to support these materials. Additionally, companies are exploring regional expansions and strategic alliances to enhance their market presence and reach new customers.
Recent Developments
- In March 2025, Leister transferred its laser plastic welding business to Hymson Novolas AG, a subsidiary of Hymson Laser Technology Group Co. Ltd. The transition ensures continuity and further development of existing product lines, with a new Laser Technology Center established in Switzerland. Leister will now focus more on its core competencies: plastic welding (hot air, infrared) and industrial process heat.
- In February 2025, Herrmann continues to set industry standards with its ultrasonic welding solutions, particularly for medical devices and sensitive components. The company emphasizes individualized process development, intelligent process control, and digital quality monitoring for reproducible, high-strength welds. Herrmann will showcase new applications and integration options at K 2025, focusing on automation and sustainability in medical and packaging industries.
- In January 2025, Dukane highlighted its patented Q-Factor, Melt-Match®, Low Amplitude Preheat, and Ultra-High Frequency (260–400 Hz) vibration welding technologies, emphasizing their leadership in process control and diagnostics.
- In May 2024, Emerson launched the Branson™ GLX-1 Laser Welder, designed for the automated assembly of small, intricate plastic parts. The GLX-1 features a compact, modular design suitable for cleanroom environments, advanced servo-based actuation, and the ability to “un-weld” plastics for closed-loop recycling. It uses Simultaneous Through-Transmission Infrared® (STTlr) laser-welding technology for high efficiency, weld strength, and aesthetics. Enhanced connectivity, security, and data collection features support Industry 4.0 integration.
Market Concentration & Characteristics
The France plastic welding equipment market exhibits moderate to high concentration, with several key players dominating the market, while also providing room for smaller, niche companies to thrive. Leading manufacturers drive innovation through continuous research and development, focusing on enhancing product efficiency, precision, and automation. The market is characterized by a diverse range of welding technologies, including hot air, ultrasonic, laser, and vibration welding, each catering to specific industry needs. Key players are also increasingly offering customized solutions to meet the demands of industries such as automotive, electronics, medical devices, and packaging. Additionally, the trend toward sustainability has influenced market characteristics, with companies emphasizing eco-friendly and energy-efficient welding systems. The competitive landscape encourages differentiation through technological advancements, such as IoT integration and automation, while regional players contribute to the local demand with tailored solutions. The market's competitive nature fosters innovation and continuous improvements to meet evolving customer needs.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Technology and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- France’s plastic welding equipment market is expected to see consistent growth driven by advancements in manufacturing technologies.
- Increased demand from the automotive and packaging industries will continue to fuel the market.
- Environmental regulations are likely to encourage the use of eco-friendly materials and technologies in plastic welding.
- Automation and robotics integration in plastic welding processes will improve efficiency and precision.
- The shift towards energy-efficient solutions will influence the design and development of new equipment.
- The growth of the aerospace and medical sectors will present new opportunities for specialized plastic welding technologies.
- France’s emphasis on sustainability will push manufacturers to invest in recyclable and reusable plastic welding solutions.
- The market will witness a rise in demand for high-frequency and ultrasonic welding methods due to their precision and reduced operational costs.
- Ongoing research and development will lead to the introduction of more compact and user-friendly plastic welding equipment.
- France’s position as a leader in the European Union’s industrial sector will help expand the market’s global reach.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the France Plastic Welding Equipment?
What factors are driving the growth of the France Plastic Welding Equipment?
What are some challenges faced by the France Plastic Welding Equipment?
Who are the major players in the France Plastic Welding Equipment?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 France Plastic Welding Equipment Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Country & Subnational Markets Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 France Plastic Welding Equipment Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 418.63 million → 2032: USD 718.13 million)
- 2.1.2 Volume & Revenue – National Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 France Plastic Welding Equipment Segmentation Snapshot
- 2.2.1 Market Split by Subnational Area – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. France Plastic Welding Equipment Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 France Plastic Welding Equipment Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage Across Domestic Markets
- 3.2 France Plastic Welding Equipment Drivers
- 3.3 France Plastic Welding Equipment Restraints & Challenges
- 3.4 France Plastic Welding Equipment Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 France Plastic Welding Equipment Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 France Plastic Welding Equipment Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 National & Subnational Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, France Plastic Welding Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 France Plastic Welding Equipment Attractiveness Analysis
- 4.1.1 By Subnational Area – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Subnational Area – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Subnational Area – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Domestic Market Opportunity Scorecards
- 4.5.1 Priority Domestic Market 1
- 4.5.2 Priority Domestic Market 2
- 4.5.3 Priority Domestic Market 3
- 4.5.4 Priority Domestic Market 4
Note: Domestic market scorecards cover relevant states, provinces, territories, cities, or economic zones within the selected country. Numbered entries are populated with market names suited to the national administrative structure and research scope. Geographic share tables use one consistent, nonoverlapping set of areas.
Chapter 5. France Plastic Welding Equipment Cross-Border Trade & Market Access Analysis
- 5.1 National Trade & International Partner Overview
- 5.1.1 Export Value by Destination Country (2024)
- 5.1.2 Export Volume by Destination Country (2024) (Where Applicable)
- 5.1.3 Import Value by Source Country (2024)
- 5.1.4 Import Volume by Source Country (2024) (Where Applicable)
- 5.1.5 National & Partner-Country Trade Balances (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Destination Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 National Participation in Regional Trade & Economic Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter covers international trade relevant to France Plastic Welding Equipment in the selected country. Exports are analyzed by destination and imports by source. Domestic interregional flows are excluded from international trade totals. Goods, services, and digital offerings use applicable classifications; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 France Plastic Welding Equipment Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Multinational, National & Local Player Dynamics
- 6.2 France Plastic Welding Equipment Share Analysis – 2024
- 6.2.1 National Revenue Share by Company
- 6.2.2 National Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Subnational Area
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 National Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 France Plastic Welding Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure Across Domestic Markets
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in France Plastic Welding Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in France Plastic Welding Equipment
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. France Plastic Welding Equipment – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Subnational Market Analysis – Country Overview
- 8.1 Domestic Geographic Market Overview
- 8.1.1 Subnational Volume Share (Where Applicable)
- 8.1.2 Subnational Revenue Share
- 8.1.3 Market Volume by Subnational Area (Where Applicable)
- 8.1.4 Market Revenue by Subnational Area
- 8.1.5 Subnational Forecasts Through 2032
- 8.2 Cross-Area Segment Analysis Within the Country
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. France Plastic Welding Equipment – Priority Domestic Market 1
Chapter 10. France Plastic Welding Equipment – Priority Domestic Market 2
Chapter 11. France Plastic Welding Equipment – Priority Domestic Market 3
Chapter 12. France Plastic Welding Equipment – Priority Domestic Market 4
Chapter 13. France Plastic Welding Equipment Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Domestic Market Focus & Local Operating Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – National Market Sizing & Subnational Allocation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
