
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
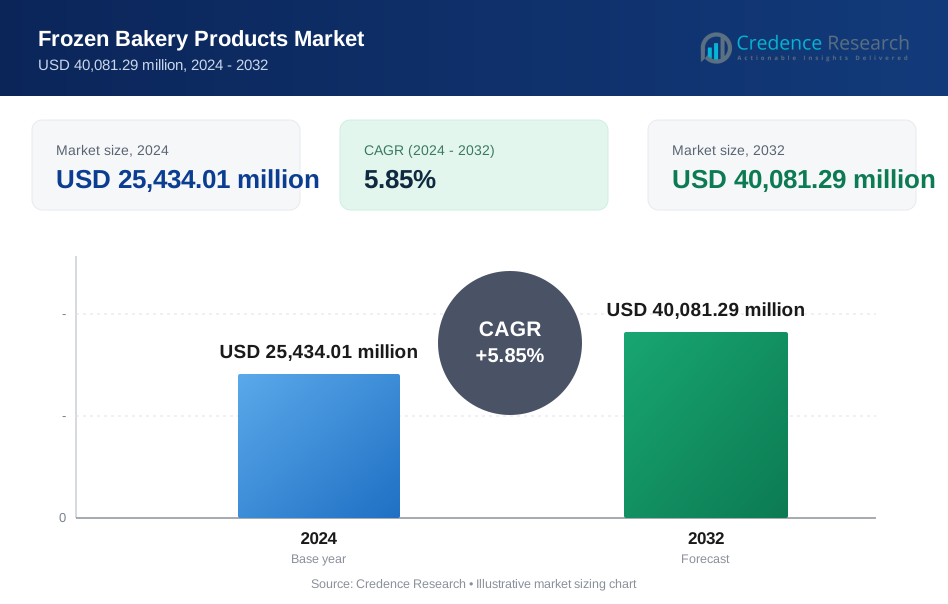
| Frozen Bakery Products Market Size 2024 | USD 25,434.01 million |
| Frozen Bakery Products Market, CAGR | 5.85% |
| Frozen Bakery Products Market Size 2032 | USD 40,081.29 million |
Market Overview
The global Frozen Bakery Products Market is projected to grow from USD 25,434.01 million in 2024 to an estimated USD 40,081.29 million based on 2032, with a compound annual growth rate (CAGR) of 5.85% from 2025 to 2032. Manufacturers continue to expand production capacities, invest in new product lines and upgrade freezing technologies to meet rising consumer demand.
Market growth reflects several key drivers and emerging trends. Convenience and ready-to-bake formats appeal to time-pressed consumers, while premium and artisanal frozen bakery offerings capture interest through unique flavors and cleaner label formulations. Rising at-home consumption of pastries, bread and snacks fuels demand, and foodservice operators increasingly rely on frozen bases to streamline kitchen operations and reduce waste. Technological advances in flash freezing and cryogenic methods preserve product quality, extend shelf life and unlock new applications for frozen bakery items in retail and institutional channels.
Regional demand patterns vary across the Americas, Europe and the Asia-Pacific. North America dominates the market, driven by strong retail penetration and established quick-service restaurant chains. Europe follows, supported by traditional bakery cultures and ongoing innovation in clean-label frozen doughs. The Asia-Pacific region exhibits the highest growth potential, propelled by urbanization, rising disposable incomes and expanding modern retail. Leading players shaping the competitive landscape include Grupo Bimbo, Aryzta AG, Flowers Foods Inc., General Mills Inc. and Kellogg Company. These companies invest in R&D, production capacity expansion and acquisitions to secure market share and respond swiftly to evolving consumer preferences.
Market Insights
- The global Frozen Bakery Products Market will rise from USD 25,434.01 million in 2024 to USD 40,081.29 million by 2032, driven by expanding production capacity and technological upgrades.
- Time-pressed consumers favor ready-to-bake breads and pastries that deliver consistent bakery quality with minimal effort.
- Health-focused shoppers seek clean-label and fortified frozen bakery items that offer nutritional benefits.
- High investment in specialized freezing systems and cold-chain infrastructure restricts participation by smaller manufacturers.
- Volatile prices of wheat, sugar and dairy ingredients pressure margins and compel frequent pricing adjustments.
- North America maintains market leadership through extensive retail penetration and advanced cold-chain logistics.
- Asia-Pacific shows the fastest growth, fueled by urbanization, rising incomes and modern retail expansion.
Report Scope
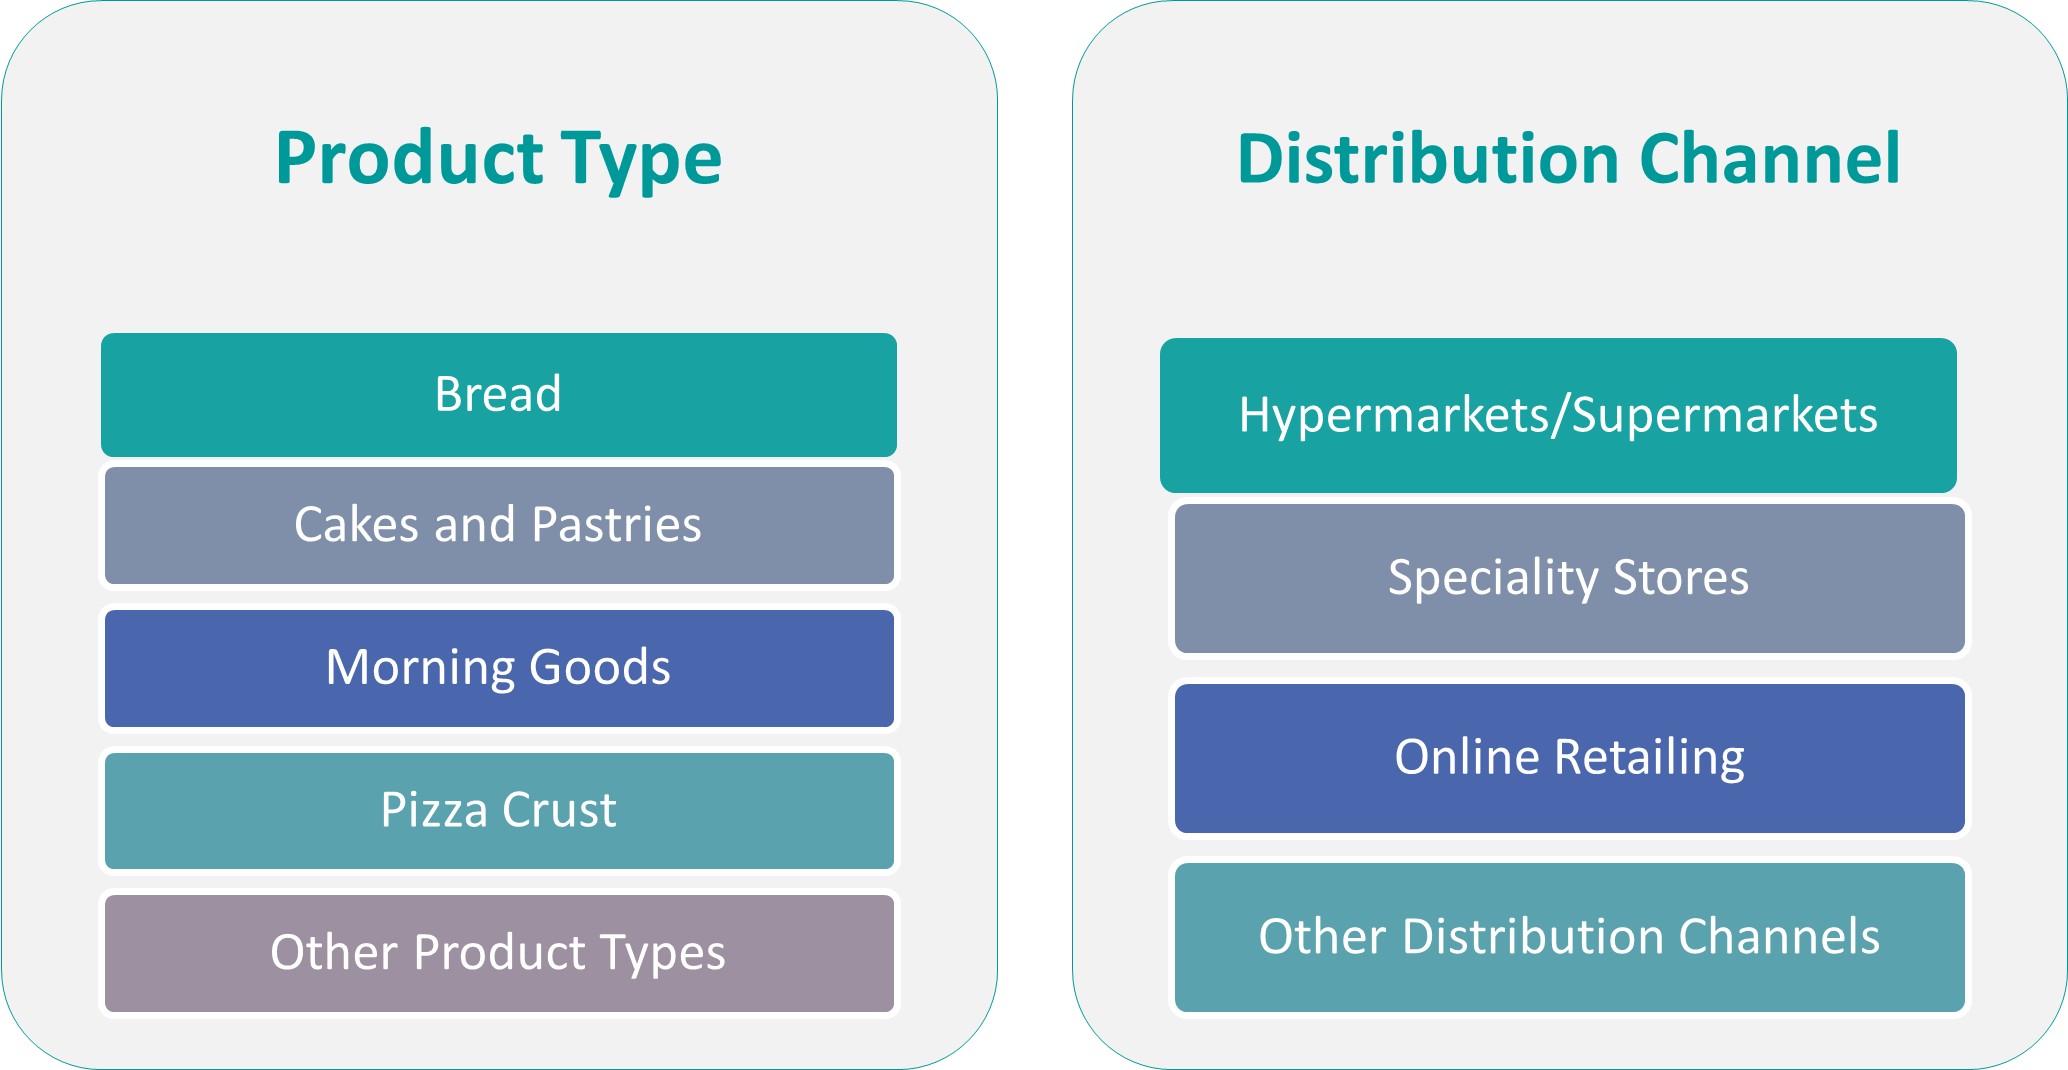
This report segments the Global Frozen Bakery Products Market as follows:
Market Drivers
Growth in Consumer Preference for Convenience Products
The global Frozen Bakery Products Market benefits from growing demand for ready-to-bake and ready-to-eat items among busy households. It supports time-pressed lifestyles by offering consistent quality without extensive preparation. Home cooks and working professionals value minimal effort combined with fresh taste. Retailers report rising sales of frozen croissants, par-baked loaves and snack bars in both chilled and frozen aisles. It aligns with the broader shift toward meal solutions that require limited handling. Manufacturers emphasize quick thaw cycles and foolproof baking instructions to maintain reliability.
- For instance, government surveys indicate that frozen bakery products account for over 60 million units sold annually across major retail chains, reflecting strong consumer demand for convenience-focused food solutions
Surge in Premium and Health-Focused Offerings
Innovation within the global Frozen Bakery Products Market drives uptake of artisanal, clean-label and fortified variants. It responds to consumer interest in whole grains, ancient grains and reduced-sugar formulations. Brands introduce flavors such as sourdough with seeds, multigrain rolls and protein-enriched doughs to capture niche segments. It expands beyond traditional white bread toward specialty items that command higher margins. Marketing teams highlight ingredient transparency and nutritional benefits on packaging. Retail data confirm that premium frozen lines deliver above-average category growth.
- For instance, over 15 million units of premium frozen bakery products, including whole grain and protein-enriched variants, were sold in the past year, highlighting the growing consumer preference for health-conscious options
Advances in Freezing and Production Technologies
Manufacturers implement state-of-the-art freezing techniques to preserve texture and flavor in the global Frozen Bakery Products Market. It leverages flash-freezing systems that lock in moisture and cell structure of dough and finished goods. Automation upgrades accelerate throughput, reduce labor costs and improve hygiene standards. It enables scalable output to meet seasonal peaks without quality compromise. Engineering teams focus on energy efficiency to lower operating expenses. Ongoing investment in cryogenic and spiral-freezing lines ensures product consistency.
Expansion of Distribution Channels and Retail Partnerships
Retailers and foodservice operators drive market growth for the global Frozen Bakery Products Market through broader availability and co-branding initiatives. It secures shelf space in supermarkets, convenience stores and club outlets across urban and suburban regions. Quick-service chains integrate frozen dough solutions to streamline kitchen workflows and reduce on-site labor. It forges private-label partnerships that enhance retailer margins and consumer loyalty. Logistics providers optimize cold-chain networks to support just-in-time deliveries. Collaborative promotions between manufacturers and retailers raise category visibility.
Market Trends
Integration of Nutrient-Rich Ingredients Drives Product Innovation
The integration of alternative flours, plant-based proteins and fiber sources shapes product development in the global Frozen Bakery Products Market. It meets consumer demand for nutrient-dense snacks, sweet and savory varieties. Brands introduce doughs that incorporate chickpea, oat and ancient grain blends to boost nutritional profile. It relies on clean label claims, removing artificial colors, flavors and preservatives. Manufacturers run pilot lines that include functional additives such as probiotics or enriched vitamins. It aligns with health and wellness trends that appeal to label-conscious shoppers.
- For instance, in 2021, Cargill invested 45 million USD in Poland to add soluble fiber to its European product portfolio, including bakery items, to offer customers sugar-free alternatives
Expansion of Digital Channels and Direct-to-Consumer Strategies
Retailers invest in e-commerce platforms and direct-to-consumer models to increase accessibility within the global Frozen Bakery Products Market. It enables targeted promotions through subscription services and bundled offerings. Brands collect real-time data on purchasing behavior to tailor product launches and refine inventory. It supports rapid deployment of limited-edition flavors and seasonal varieties. Technology teams integrate cold-chain tracking software that ensures product integrity through last-mile delivery. It opens new revenue streams and reduces dependence on brick-and-mortar shelf space.
- For instance, the global frozen bakery products market has seen a significant shift, with over 70% of major brands adopting direct-to-consumer strategies to enhance customer engagement and optimize distribution
Market Challenges
High Capital Expenditure and Cold-Chain Infrastructure Requirements
The global Frozen Bakery Products Market demands significant investment in specialized equipment and storage facilities. Firms must fund advanced freezing systems to maintain product quality. It faces challenges in network construction for cold-chain coverage across regions. Operators require strict handling protocols to prevent temperature deviations. It increases operational complexity and elevates maintenance costs. Companies encounter pressure to optimize energy consumption while ensuring reliable performance. It limits entry for smaller players that lack scale or capital reserves.
- For instance, Suprima Bakeries, an Australian bakery supplier, launched its Artisan Frozen Dough line in January 2023 to help bakers modify their menu offerings and serve different types of bread throughout the week
Volatile Raw Material Prices and Supply Chain Disruptions
Manufacturers in the global Frozen Bakery Products Market struggle with variable costs for wheat, sugar and dairy ingredients. It exposes profit margins to commodity market shifts. Producers must secure long-term contracts to mitigate price swings. It complicates budgeting and forces frequent price adjustments. Transport delays and geopolitical events can disrupt supply routes for packaging materials. It demands robust contingency plans to maintain production continuity. It underscores the need for diversified sourcing strategies and stronger supplier relationships.
Market Opportunities
Penetration into Emerging Economies and Health-Focused Segments
Urbanization and rising incomes create robust demand in developing regions within the global Frozen Bakery Products Market. It allows manufacturers to introduce value-added and region-specific flavors. Consumers seek healthier alternatives that contain whole grains, probiotics and plant proteins. It encourages product diversification beyond traditional white bread and pastries. Bakery firms can partner with local retailers to tailor offerings to cultural preferences. It supports premium pricing and brand differentiation. Suppliers gain from scale by combining global expertise with local insights.
Innovation in E-Commerce Channels and Sustainable Packaging Solutions
Growth in online grocery and meal kit sectors presents new sales avenues for frozen bakery. It provides direct access to consumer data and customization options. Companies can launch subscription-based offerings for delivered fresh-bake kits. It partners with logistics providers to ensure cold-chain integrity. Sustainable packaging innovation reduces plastic waste and attracts eco-conscious shoppers. It enhances brand image and meets regulatory standards for recyclability. Retailers benefit from co-branded campaigns that drive category growth.
Market Segmentation Analysis
By Product Type
The global Frozen Bakery Products Market divides product offerings across bread, cakes and pastries, morning goods, pizza crust and other types. It assigns the largest share to bread due to reliable shelf life and everyday consumption. Cakes and pastries capture premium segments through artisanal flavors and decorative finishes. Morning goods meet breakfast routines with croissants and Danish pastries that require minimal preparation. Pizza crust benefits from home-delivery and quick-service trends seeking convenience. Other product types include savory snacks and specialty items that cater to niche tastes. It drives portfolio diversification and addresses evolving consumer preferences.
By Distribution Channel
The global Frozen Bakery Products Market channels distribution through hypermarkets/supermarkets, specialty stores, online retailing and other outlets. It depends on hypermarkets and supermarkets for broad reach and volume sales. Specialty stores showcase premium and artisanal lines that appeal to discerning shoppers. Online retailing supports direct-to-consumer engagement via subscription services and home delivery. It enables real-time demand tracking and faster product launches. Other channels include convenience stores and foodservice distributors that supply on-the-go and institutional needs. It emphasizes omnichannel strategies to maximize coverage and consumer access.
Segments
Based on Product Type
- Bread
- Cakes and Pastries
- Morning Goods
- Pizza Crust
- Other Product Types
Based on Distribution Channel
- Hypermarkets/Supermarkets
- Specialty Stores
- Online Retailing
- Other Distribution Channels
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America Dominance through Retail Penetration and Innovation
The global Frozen Bakery Products Market in North America benefits from deep retail penetration and established cold-chain logistics. It captures consumer interest through a broad range of ready-to-bake breads and pastries. Retail giants secure shelf space for both mainstream and premium frozen lines. It invests in promotional campaigns and private-label partnerships. Technology firms refine temperature-control software to ensure product integrity. It adapts to seasonal demand by launching limited-edition flavors. Companies pursue mergers to optimize distribution and scale operations.
European Strength from Artisan Traditions and Regulatory Support
The global Frozen Bakery Products Market in Europe draws strength from centuries-old baking culture and stringent quality standards. It enjoys strong demand for artisanal sourdough, multigrain loaves and gourmet tarts. Supermarkets and specialty grocers stock diverse frozen selections reflecting regional tastes. It leverages Protected Designation of Origin labels to differentiate premium products. Manufacturers channel investment into energy-efficient spiral freezers. It sustains growth with product reformulation to comply with clean-label regulations.
Asia-Pacific Growth Driven by Urbanization and Modern Retail Expansion
The global Frozen Bakery Products Market in Asia-Pacific registers rapid growth thanks to urbanization and rising incomes. It penetrates newly built supermarkets and convenience outlets in major cities. Foodservice chains adopt frozen dough for efficient back-of-house operations. It builds partnerships with e-commerce platforms for home-delivery solutions. Manufacturers tailor spice profiles and local flavors to match cultural preferences. It funds capacity expansion in China, India and Southeast Asian hubs.
Key players
- Kellogg Co.
- co.in (U.S.)
- Conagra Brands, Inc. (U.S.)
- London Dairy Co. Ltd (U.K.)
- Danone SA (France)
- ADM (U.S.)
- Daiya Foods Inc. (Canada)
- Grupo Bimbo S.A.B. de C.V. (Mexico)
- Associated British Foods PLC (U.K.)
- General Mills Inc. (U.S.)
- Lantmännen Unibake (Denmark)
- Aryzta AG (Switzerland)
- Vandemoortele NV (Belgium)
- Europastry S.A. (Spain)
- Cole’s Quality Food Inc. (U.S.
Competitive Analysis
Competition in the global Frozen Bakery Products Market centers on product innovation, distribution network strength and brand partnerships. It highlights how established leaders secure private-label agreements with major retailers to ensure consistent shelf presence. Regional specialists build loyal followings by matching flavors to local tastes. Major companies invest heavily in R\&D to refine freezing processes and develop sustainable packaging. It drives faster responsiveness and maintains product integrity. Value-driven brands compete on price and convenience by optimizing manufacturing efficiency. It pressures smaller players to focus on niche offerings or lean operations. Retail alliances and co-branding initiatives intensify rivalry by expanding promotional channels. It underscores the role of digital engagement and direct-to-consumer platforms in capturing consumer insights. Strategic mergers and joint ventures reshape market structure and raise entry barriers for new competitors.
Recent Developments
- In August 2024, WK Kellogg Co. announced a supply chain modernization plan costing between $450 million and $500 million to upgrade infrastructure and technology at its Battle Creek, MI; Lancaster, PA; and Belleville, ON plants.
- On December 17, 2024, Conagra Brands published its “Future of Frozen Food 2025” report highlighting spicy-flavor demand and indulgent in-home dining trends.
- In 2025, Danone continues to execute its “Renew Danone” strategic plan focused on reconnecting with sustainable, profitable growth.
- In May 2025, Daiya Foods unveiled reformulated dairy-free cream cheese made with its Oat Cream™ blend for improved texture and spreadability.
- In May 2025, ABF interim results note early signs of improvement in UK trading conditions, despite challenges in H2 2025.
- In March 2025, Vandemoortele’s 2024 annual report states Délifrance’s frozen bakery activities achieved a turnover of ~€930 million with over 3,200 employees.
Market Concentration and Characteristics
The global Frozen Bakery Products Market features a moderate to high concentration, with a handful of multinational firms commanding substantial share while numerous regional and niche players occupy smaller segments. It experiences consolidation through mergers and acquisitions that strengthen distribution networks and production capacity. Industry leaders leverage extensive cold-chain logistics and private-label partnerships to secure retail shelf space. It faces pressure from cost-sensitive competitors that optimize operations to offer value-priced products. Market characteristics include rigorous quality standards, significant capital requirements for freezing infrastructure and robust compliance with food safety regulations. It rewards scale, innovation and strategic alliances.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Manufacturers will integrate AI-driven quality control to optimize freezing cycles. It will reduce waste and enhance texture consistency across diverse product lines.
- Plant-based and functional ingredient incorporation will expand portfolio offerings. It will attract health-conscious consumers seeking nutritious, convenient bakery solutions
- Cold-chain logistics will undergo digital transformation through blockchain integration. It will ensure traceability and strengthen consumer confidence in product safety.
- E-commerce penetration will fuel direct-to-consumer subscriptions for frozen bakery kits. It will enable personalized offerings and generate actionable data on buying behavior.
- Sustainable packaging innovations will emerge to reduce environmental impact. It will leverage compostable materials and optimize packaging designs for logistics efficiency.
- Regional customization will become critical as emerging markets drive growth. It will prompt manufacturers to tailor flavors and formats to local consumer preferences.
- Automated production lines will scale up to meet seasonal and peak demands. It will accelerate throughput while maintaining rigorous hygiene and quality standards.
- Collaborative partnerships between retailers and bakers will intensify promotional campaigns. It will enhance shelf visibility and shorten time-to-market for limited-edition products.
- Regulatory focus on clean-label transparency will shape ingredient sourcing practices. It will compel suppliers to adopt clear documentation and simplify ingredient lists.
- Strategic M\&A activity will consolidate the market around top-tier global players. It will enable capacity expansion and foster technological sharing across regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in Consumer Preference for Convenience Products
Busy lifestyles and the need for quick meal solutions are driving demand for frozen bakery products that offer consistent quality with minimal preparation. Ready-to-bake and ready-to-eat formats appeal to both home cooks and foodservice operators seeking efficiency.
Surge in Premium and Health-Focused Offerings
Consumers are increasingly seeking clean-label, fortified, and artisanal frozen bakery products, such as whole grain and protein-enriched variants. This trend is expanding the market beyond traditional offerings and supporting higher-margin product lines.
Advances in Freezing and Production Technologies
Innovations in flash freezing, cryogenic methods, and automation are improving product quality, extending shelf life, and enabling scalable production. These technological upgrades help manufacturers meet rising demand and maintain product consistency.
Expansion of Distribution Channels and Retail Partnerships
Broader availability through supermarkets, specialty stores, and online retailing, along with private-label partnerships and improved cold-chain logistics, is increasing market penetration and accessibility for consumers across regions.
Penetration into Emerging Economies and Health-Focused Segments
Urbanization, rising disposable incomes, and growing health awareness in emerging markets are creating new opportunities for frozen bakery products, especially those with region-specific flavors and nutritional enhancements.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate of the global Frozen Bakery Products Market?
What are the main drivers of growth in the frozen bakery products market?
Which regions are leading the global Frozen Bakery Products Market?
What are the current trends in the frozen bakery products market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Bread
- 1.2.2 Cakes and Pastries
- 1.2.3 Morning Goods
- 1.2.4 Pizza Crust
- 1.2.5 Other Product Types
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 25,434.01 million → 2032: USD 40,081.29 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Frozen Bakery Products Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Frozen Bakery Products Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Frozen Bakery Products Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Frozen Bakery Products Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Frozen Bakery Products Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Frozen Bakery Products Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Frozen Bakery Products Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Frozen Bakery Products Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 25,434.01 million → 2032: USD 40,081.29 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Frozen Bakery Products Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Bread
- 12.3.7.2 Cakes and Pastries
- 12.3.7.3 Morning Goods
- 12.3.7.4 Pizza Crust
- 12.3.7.5 Other Product Types
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 Segment Growth Comparison
- 12.5 Segment Attractiveness and Priority Matrix
Chapter 13 Global Frozen Bakery Products Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Frozen Bakery Products Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Frozen Bakery Products Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Grupo Bimbo S.A.B. de C.V.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Aryzta AG
- 17.4 Flowers Foods Inc.
- 17.5 General Mills Inc.
- 17.6 Kellogg Company
- 17.7 Vandemoortele NV
- 17.8 Associated British Foods PLC
- 17.9 Europastry S.A.
- 17.10 Lantmännen Unibake
- 17.11 Conagra Brands, Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
