
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Edible Gold Market Size 2023 | USD 128.62 Million |
| Edible Gold Market, CAGR | 9.00% |
| Edible Gold Market Size 2032 | USD 282.77 Million |
Market Overview
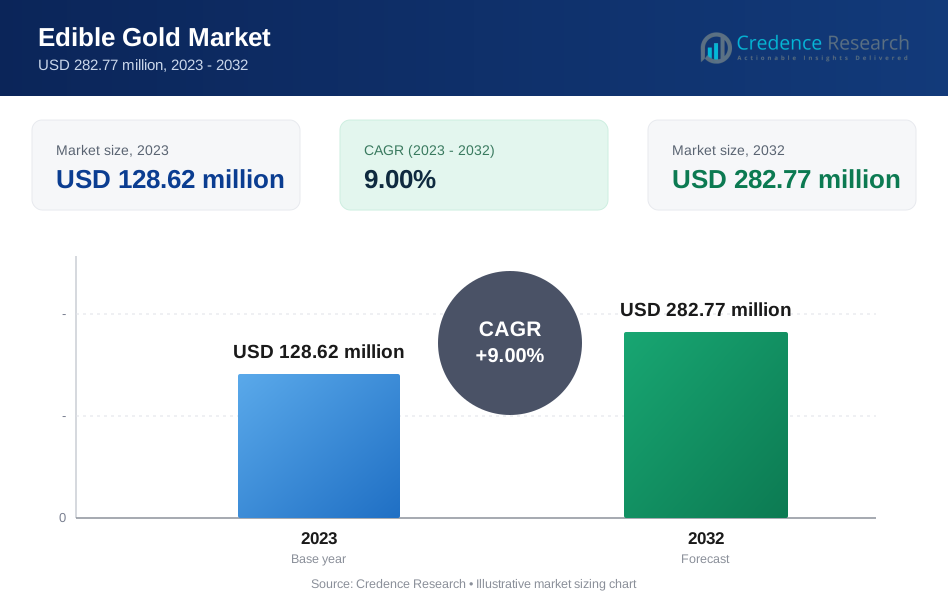
The edible gold market is projected to grow from USD 128.62 million in 2023 to USD 282.77 million by 2032, expanding at a compound annual growth rate (CAGR) of 9.00%.
The growth of the edible gold market is driven by increasing consumer interest in luxurious and visually appealing gourmet experiences, especially in premium confections, beverages, and fine dining. Social media trends that highlight extravagant eating and dining experiences also significantly contribute to the demand for edible gold. Furthermore, the expansion of the hospitality and event industry, which frequently incorporates edible gold in celebratory and high-end offerings, continues to propel market growth. Innovations in product application and the rising disposable income among consumers globally further fuel the adoption of edible gold in various culinary applications.
Geographically, the edible gold market is dominated by North America and Europe, where luxury dining and high-end culinary experiences are highly valued. Asia Pacific is also witnessing rapid growth due to rising affluence and increased exposure to Western dining trends, particularly in countries like China and India. Key players in the market include Cornucaupia, DeLafée, Silver Star, and The Gold Leaf. These companies are pivotal in driving innovation and the accessibility of edible gold products. Their strategies often involve enhancing distribution channels, expanding product portfolios, and engaging in partnerships to cater to a growing global clientele.
Market Drivers
Rising Popularity of High-End Dining
The global fine dining sector is experiencing robust growth, characterized by a demand for unique and visually stunning culinary presentations. Edible gold meets this need by enabling chefs to infuse their dishes with sophistication and a sense of spectacle, thus attracting diners who seek memorable and exceptional dining experiences. This trend not only enhances the dining experience but also supports the expansion of the edible gold market.
Social media influence
In the era of Instagram and Pinterest, the visual appeal of food is more crucial than ever. For instance, a study found that nearly 69% of millennials take a photo or a video of their food before eating. This trend is particularly evident in the popularity of “foodstagramming,” where users share images of their meals on social media. Edible gold, with its striking visual quality, makes dishes highly photogenic and shareable on social media platforms. For example, in Dhaka, gold-wrapped doughnuts, gold-plated pizzas, and gold-leaf-wrapped burgers are available in a number of countries around the world. The Gold Jilapi, a delicacy wrapped in gold foil, was completely sold out in less than a week after being reviewed by prominent food bloggers and social media influencers.
Ingredient Versatility and Cultural Significance
Edible gold’s versatility extends across various culinary applications. For instance, it is used to gild the tops of chocolates or truffles, decorate cakes and cupcakes, add a shimmering touch to fruit platters, and enhance the presentation of gourmet dishes in high-end restaurants. It can also be used to add a luxurious touch to savory dishes and cocktails. In regions like Asia, gold holds profound cultural significance, symbolizing wealth, prosperity, and good fortune. For example, in India, thin gold foils known as ‘varak’ are traditionally layered atop sweets like ‘barfi’ and ‘laddu’ during festive occasions. The shimmering gold not only enhances the visual appeal but also signifies the importance of the celebration. This cultural aspect makes edible gold particularly appealing during festive occasions and celebrations, boosting its market appeal. For instance, during the Chinese New Year, nearly everyone stops working and takes time to reconnect with their families. During this time, the consumption of gold increases, indicating the cultural significance and market demand for gold.
Perception of Health Benefits
Although scientifically unproven, some consumers attribute health benefits to edible gold, associating it with the positive properties of the precious metal. For instance, some believe that edible gold can treat respiratory conditions such as asthma. In traditional Indian medicine, gold in the form of nanoparticles, known as swarna bhasma, is combined with honey, ghee, and milk to treat asthma. Edible gold is also thought to boost the immune system by increasing white blood cell production, which helps the body fight off infection. Some contemporary researchers have concluded that edible gold has an incredibly positive effect on nerve structure and the brain. It is also believed to relieve stress, repair the brain, and boost the body’s immune response to oxidative stress. This perception, albeit limited, contributes to the product’s allure and supports market growth, as consumers are drawn to both its aesthetic and purported health benefits. For example, a study on consumer preferences towards edible oil in central Chennai district concluded that health benefits, chemical-free, quantity, and advertising are the most important factors influencing consumer preferences for edible oil. Hence, the perceived health benefits of edible gold could potentially influence consumer preferences and support market growth.
Market Trends
Innovative Visual Enhancements and Expanded Product Forms
In the culinary world, presentation remains a cornerstone of dining experiences, and edible gold is at the forefront of enhancing the visual appeal of dishes and drinks. For instance, chefs and mixologists are increasingly using edible gold in creative ways. They create intricate geometric patterns in plated desserts and suspend delicate gold leaf flakes elegantly within craft cocktails.
Beyond the traditional large flakes, the market has seen a rise in the popularity of microgold flakes and edible gold dust. These finer forms offer a subtle sophistication that is perfect for dusting over desserts, creating shimmering effects in beverages, or adding an understated elegance to savory appetizers. For example, in Dhaka, gold-wrapped doughnuts, gold-plated pizzas, and gold-leaf-wrapped burgers are available in a number of countries around the world. The Gold Jilapi, a delicacy wrapped in gold foil, was completely sold out in less than a week after being reviewed by prominent food bloggers and social media influencers.
This trend towards diversified forms of edible gold allows for its broader use in a variety of culinary applications, appealing to both professional chefs and culinary enthusiasts seeking to elevate their creations.
Flavor Innovation, Sustainability, and Consumer Accessibility
While edible gold is traditionally tasteless, recent market innovations have introduced flavored gold products, infusing this luxurious ingredient with tastes like rose, chocolate, and even chili pepper. For instance, Optimum Nutrition offers a naturally flavored Gold Standard 100% whey protein powder. Such innovations open new avenues for culinary creativity and cater to consumers eager to explore adventurous flavors in their dishes and drinks.
As global awareness of environmental sustainability grows, the demand for ethically sourced and sustainably produced edible gold is increasing. Manufacturers are responding by improving their sourcing practices and adopting eco-friendly packaging solutions to minimize their environmental footprint. For example, some jewelry brands are now using'sustainable gold’, which is sourced responsibly and meets international best practice environmental and social standards. Another significant trend is the democratization of edible gold through DIY kits and enhanced online availability, which broadens its reach beyond professional kitchens. Home cooks can now experiment with this extravagant ingredient, adding a touch of luxury to home-prepared meals. For instance, Tammy Holmes offers a DIY crystal candy kit that includes edible gold among its ingredients.
Market Challenge Analysis
Financial Accessibility and Consumer Value Perception Challenges
Edible gold, inherently a luxury product, faces significant market challenges primarily due to its high cost. The value of gold itself, coupled with the complexities involved in refining it for consumption, substantially elevates its price. This makes edible gold a viable option almost exclusively for high-end establishments and luxury goods, thus limiting its accessibility to a broader consumer base. Additionally, not all consumers perceive edible gold as a valuable addition to their culinary experiences. Given its lack of flavor enhancement or nutritional benefits, many regard it as an unnecessary extravagance. Overcoming this perception is a key challenge for the industry, which must convincingly articulate and demonstrate the unique experience and visual appeal that edible gold can offer, aiming to shift consumer perspectives towards viewing it as a worthwhile indulgence.
Regulatory, Ethical, and Practical Considerations
The use of edible gold is also subject to a diverse regulatory landscape, which varies significantly from one country to another. Manufacturers are tasked with navigating these complex regulatory environments to ensure that their products meet all applicable safety standards and are properly labeled for consumer use. Moreover, the ethical sourcing of gold becomes increasingly critical as consumers become more environmentally conscious and socially aware. The gold mining industry is often criticized for its environmental and social impacts, which can deter ethically-minded consumers from purchasing products unless the gold is sourced responsibly and sustainability practices are clearly communicated. Furthermore, challenges related to the availability and practical use of edible gold persist. Its limited availability compared to more common culinary ingredients poses logistical challenges for both professional chefs and home cooks. Additionally, the limited shelf life and specific storage requirements of edible gold leaf can complicate its use and quality maintenance. The ingredient’s restriction to mostly aesthetic purposes further limits its culinary applications, as it does not contribute flavor or texture to dishes, potentially constraining its appeal to chefs and food enthusiasts who prioritize taste and culinary innovation.
Market segmentation analysis:
By Type:
In the edible gold market, segmentation by type includes powder, leaf, flakes, and crumbs, each serving distinct aesthetic and culinary purposes. Edible gold powder is primarily used for its ease of application in beverages and fine pastries, offering a subtle shimmer. Gold leaf, known for its delicate yet dramatic visual appeal, is popularly used in high-end culinary presentations and luxury confections. Flakes and crumbs provide a versatile option for garnishing and adding a touch of luxury to both sweet and savory dishes. The choice of type largely depends on the desired visual impact and the specific application within culinary creations. Each form of edible gold caters to different segments of the culinary industry, ranging from gourmet cooking and fine dining to luxury baking and beverage making, illustrating the versatility and adaptability of edible gold across various culinary domains.
By Purity Type:
Segmentation of the edible gold market by purity type includes categories such as less than 95% purity, between 95% and 97% purity, and greater than or equal to 97% purity. Each purity level caters to different market needs and quality standards expected by consumers. Gold with less than 95% purity is typically utilized where slight impurities do not affect the application's outcome, often in decorative arts. In contrast, gold with a purity between 95% and 97% finds a balance between cost and high visual quality, making it suitable for culinary applications where both value and appearance are important. The highest demand is for gold with a purity of 97% or more, preferred in luxury culinary and artistic uses where only the highest quality material is acceptable. This segmentation allows suppliers to cater to diverse consumer preferences and application requirements, ensuring a broad market reach and satisfaction across various consumer bases.
Segments:
Based on type:
- Powder
- Leaf
- Flakes
- Crumbs
Based on Purity Type:
- Purity less than 95%
- Purity between 95% and 97%
- Purity greater than or equal to 97%
Based on the distribution channel:
- Offline
- Online
Based on the application:
- Foods
- Beverages
- Cosmetics
- Others
Based on the geography:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Asia-Pacific
Asia-Pacific dominates the market, capturing a substantial 45% share. This region's dominance can be attributed to the deep-rooted cultural significance of gold in culinary practices, particularly in countries like India, where gold is used in traditional sweets and beverages. Additionally, the growing affluence and the desire for opulent dining experiences in countries like China and Japan have fueled the demand for edible gold.
Europe
Europe closely follows, capturing approximately 15% of the global market share. The region's demand for edible gold is driven by factors such as the pursuit of unique culinary experiences, the influence of haute cuisine, and the growing trend of molecular gastronomy. Countries like France, Italy, and Switzerland are key contributors to the region's market growth, with renowned chefs and luxury establishments incorporating edible gold into their offerings.
Key Player Analysis
- Cornucaupia
- Delafã©E
- Easy Leaf Products
- Horikin
- Lymm Wrights
- Manetti
- Noris
- Silver Star
- The Gold Leaf Company
- Wandb Gold Leaf
Competitive Analysis
The competitive landscape of the edible gold market features several key players who specialize in the production and distribution of this luxurious product. Cornucaupia and DeLafée are prominent for their high-quality gold leaf products, often used in high-end culinary and artistic applications. Easy Leaf Products and Horikin are noted for their innovative approaches to product variety and application techniques, expanding usability across different culinary fields. Lymm Wrights, Manetti, and Noris are established players with strong historical backgrounds, providing them credibility and trust within the market. Silver Star and The Gold Leaf Company focus on delivering both variety and affordability, making edible gold more accessible. Wandb Gold Leaf distinguishes itself by offering specialized products tailored to the needs of professional chefs and luxury food manufacturers. Each company contributes to a dynamic market environment through strategic marketing, product development, and geographic expansion efforts.
Market Concentration and Characteristics
The edible gold market exhibits a moderate level of market concentration, with a few key players dominating the industry. These leading companies, including Cornucaupia, DeLafée, and Manetti, hold substantial market shares due to their established brand reputations, extensive product lines, and global distribution networks. The market is characterized by its niche appeal, primarily catering to luxury sectors such as high-end dining, gourmet confectionery, and premium beverages. Innovation plays a critical role in this market, with companies continually exploring new forms and applications of edible gold to differentiate their offerings and captivate high-end consumers. Additionally, the market dynamics are influenced by trends in luxury spending, the influence of social media on dining aesthetics, and growing consumer interest in unique and extravagant culinary experiences. As a result, competitive strategies often focus on product quality, brand prestige, and tapping into emerging markets where luxury consumption is on the rise.
Report Coverage
The research report offers an in-depth analysis based on type, purpose type, distribution channel, application, and geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued growth in the luxury dining and confectionery sectors will drive demand for edible gold.
- Innovations in product forms, such as nano-gold or biodegradable options, are likely to emerge.
- Expansion in e-commerce will improve accessibility and boost sales in global markets.
- Increased consumer interest in unique and Instagrammable food presentations will propel market growth.
- Greater emphasis on ethical sourcing and sustainability practices will influence manufacturing and supply chains.
- Flavored edible gold products will gain popularity, catering to consumer demand for novel culinary experiences.
- The introduction of DIY edible gold kits will encourage use in home cooking and small-scale events.
- Partnerships with celebrity chefs and high-profile events will enhance brand visibility and market reach.
- Regulatory frameworks will evolve, potentially impacting market dynamics and product compliance.
- The Asia-Pacific region will see rapid market expansion due to increasing disposable incomes and cultural affinity for luxury goods.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Popularity of High-End Dining
The global fine dining sector is expanding, with chefs and restaurants seeking unique ways to create memorable, visually stunning culinary experiences. Edible gold is increasingly used to add sophistication and spectacle to dishes, attracting diners who value luxury and exclusivity.
Social Media Influence
Platforms like Instagram and Pinterest have amplified the importance of food aesthetics, making visually striking ingredients like edible gold highly desirable. Viral trends and influencer endorsements drive consumer curiosity and demand for gold-adorned foods and beverages.
Ingredient Versatility and Cultural Significance
Edible gold is used across a wide range of culinary applications, from luxury confections to traditional sweets in Asia, where gold symbolizes prosperity and celebration. Its adaptability and cultural resonance, especially during festivals and special occasions, boost its market appeal.
Perception of Health Benefits
Although not scientifically proven, some consumers believe edible gold offers health benefits, such as boosting immunity or relieving stress. This perception, combined with its luxury status, enhances its allure and supports market growth.
Expansion of Hospitality and Event Industry
The growing number of luxury events, weddings, and high-profile celebrations has increased the use of edible gold in premium offerings. Hotels, caterers, and event planners incorporate edible gold to elevate the perceived value and exclusivity of their services.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the edible gold market?
What factors are driving the growth of the edible gold market?
What are the key segments within the edible gold market?
What are some challenges faced by the edible gold market?
Who are the major players in the edible gold market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Powder
- 1.2.2 Leaf
- 1.2.3 Flakes
- 1.2.4 Crumbs
- 1.3 By Application
- 1.3.1 Foods
- 1.3.2 Beverages
- 1.3.3 Cosmetics
- 1.3.4 Others
- 1.4 By Purity Type
- 1.4.1 Purity less than 95%
- 1.4.2 Purity between 95% and 97%
- 1.4.3 Purity greater than or equal to 97%
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 128.62 million → 2032: USD 282.77 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Edible Gold Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Edible Gold Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Edible Gold Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Edible Gold Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Edible Gold Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Edible Gold Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Edible Gold Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Edible Gold Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 128.62 million → 2032: USD 282.77 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Edible Gold Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Powder
- 12.3.7.2 Leaf
- 12.3.7.3 Flakes
- 12.3.7.4 Crumbs
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Foods
- 12.4.7.2 Beverages
- 12.4.7.3 Cosmetics
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Purity Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Purity less than 95%
- 12.5.7.2 Purity between 95% and 97%
- 12.5.7.3 Purity greater than or equal to 97%
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Edible Gold End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Edible Gold Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Edible Gold Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Edible Gold Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Cornucaupia
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 DeLafée
- 18.4 Easy Leaf Products
- 18.5 Horikin
- 18.6 Lymm Wrights
- 18.7 Manetti
- 18.8 Noris
- 18.9 Silver Star
- 18.10 The Gold Leaf Company
- 18.11 Wandb Gold Leaf
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

