
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Generator Control Units Market Size 2024 | USD 690.71 Million |
| Generator Control Units Market, CAGR | 5.83% |
| Generator Control Units Market Size 2032 | USD 1,086.84 Million |
Market Overview
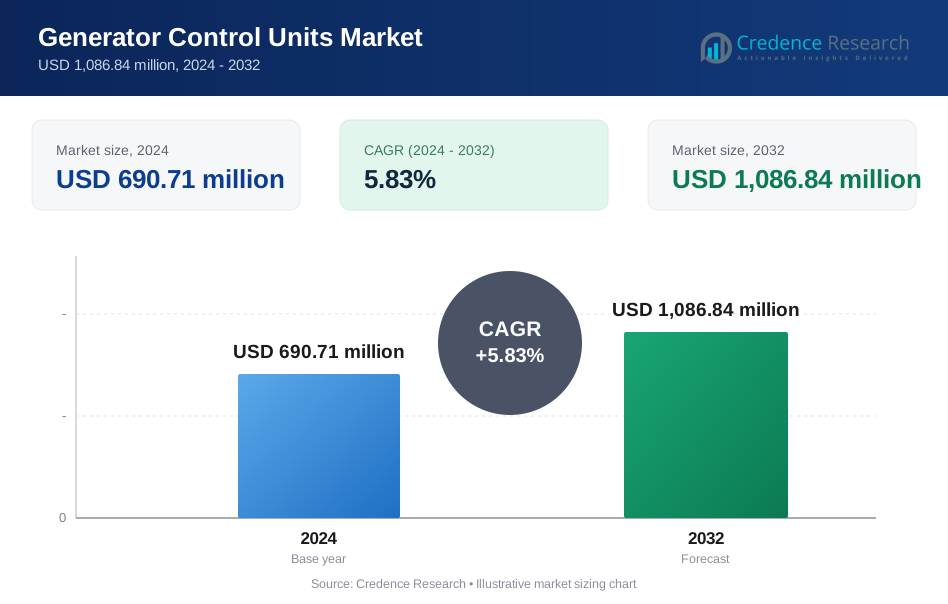
The Generator Control Units Market is projected to grow from USD 690.71 million in 2024 to USD 1,086.84 million by 2032, at a compound annual growth rate (CAGR) of 5.83%.
The Generator Control Units market is primarily driven by rising demand across sectors like industrial, commercial, and healthcare, where reliable power backup is essential. Technological advancements in control units, such as automation and remote monitoring, enhance operational efficiency and reduce maintenance needs, making these units more attractive to users. Additionally, the integration of smart technologies allows real-time data tracking and predictive maintenance, further propelling market growth. Increasing energy consumption, particularly in emerging economies, and a growing focus on renewable energy solutions also contribute to the demand for efficient and adaptable generator control systems globally.
North America and Europe hold substantial shares in the Generator Control Units (GCU) market, driven by robust infrastructure, industrial sectors, and strong adoption of advanced power control technologies. North America's market dominance is supported by high demand in critical sectors like healthcare and data centers, while Europe benefits from increased adoption of renewable energy sources, necessitating advanced GCUs for grid stability. Key players such as GE, Comap, DSE, and Kohler are instrumental in driving innovation, focusing on integrating IoT and smart control features. Companies like Emerson, Deif, and Smartgen further strengthen market growth with digitalization and enhanced cybersecurity solutions.
Market Drivers
Increasing Demand for Reliable Power Supply The rising need for uninterrupted power in various industries fuels the demand for Generator Control Units (GCUs), particularly within sectors like manufacturing, healthcare, and data centers. These industries depend on consistent power to safeguard operations and prevent financial losses during power disruptions. For instance, data centers require GCUs to ensure continuous operations and prevent data loss during power outages. GCUs facilitate a seamless switch from utility power to generator power, ensuring continuous operations without compromising productivity. The residential sector is also witnessing increased GCU demand due to remote work trends and reliance on electronic devices. Home generators equipped with GCUs offer peace of mind during outages by efficiently managing power transitions and ensuring reliable backup solutions.
Growing Adoption of Renewable Energy Sources As renewable energy sources like solar and wind power become integral to the global power landscape, the need for hybrid power systems incorporating GCUs has grown. These units are pivotal in balancing and optimizing hybrid systems that blend renewable energy with traditional generators. For example, GCUs are essential in managing the integration of solar power with diesel generators in hybrid systems. GCUs ensure a stable power supply by harmonizing the complexities of renewable energy with conventional power sources, thereby enhancing system efficiency and reliability. This integration is critical for meeting energy demands sustainably, supporting the global transition toward environmentally friendly energy solutions.
Advancements in GCU Technology Technological advancements in GCUs, including the development of smart units, drive market growth by enhancing operational capabilities and reducing maintenance needs. Smart GCUs incorporate advanced features like remote monitoring, predictive maintenance, and Internet of Things (IoT) integration, making power management more efficient and secure. Digitalization further contributes to the market as digital GCUs offer enhanced data analytics, remote control, and cybersecurity measures, addressing the increasing digitalization trend in power generation. These technological innovations significantly improve efficiency, reliability, and overall performance of GCUs.
Stringent Regulations and Infrastructure Growth in Emerging Markets Stricter emission standards imposed by governments globally have propelled demand for efficient GCUs that support regulatory compliance. By optimizing generator engine performance, GCUs minimize emissions, helping industries meet environmental standards. Additionally, increasing fuel costs highlight the need for fuel-efficient generators, with GCUs playing a key role in optimizing load management and reducing operational costs. In emerging markets, rapid urbanization and infrastructure development further drive GCU adoption, as these units are crucial for ensuring reliable power across new projects like hospitals, schools, and commercial establishments, catering to the growing demand for consistent energy solutions.
Market Trends
Surging Demand for Reliable Power and Integration with Renewable Energy The growing need for reliable power across critical infrastructure, remote sites, and areas with limited grid access is boosting the Generator Control Units (GCUs) market. Industries like healthcare, data centers, and telecommunications depend on continuous power to prevent operational interruptions, with GCUs enabling seamless transitions during outages. For remote or off-grid locations, GCUs facilitate efficient power generation and distribution, providing an essential solution where grid connections are sparse. Alongside traditional power, the integration of renewable energy sources is driving GCU adoption, particularly in hybrid power systems that combine solar, wind, and conventional generators. GCUs play an instrumental role in these systems by stabilizing energy flows and balancing sources for efficient and sustainable power distribution. Furthermore, in microgrids-localized, autonomous power systems that can operate independently from the main grid-GCUs are critical for optimizing performance and ensuring reliable power management, enhancing energy security in both rural and urban settings.
Technological Innovations and Regulatory Drivers Transforming GCU Landscape Advances in technology are reshaping GCUs, with smart GCUs gaining traction due to their ability to offer remote monitoring, predictive maintenance, and IoT integration, which streamlines power management and bolsters reliability. For example, smart GCUs can predict maintenance needs and alert operators before issues arise. Digitalization further supports this trend, as digital GCUs incorporate data analytics, enhanced cybersecurity, and remote access features, meeting the rising demand for efficient and secure power systems in an increasingly connected environment. Regulatory standards for emissions have also intensified the need for GCUs, as governments worldwide enforce strict emission norms. GCUs help manage generator performance to minimize emissions, supporting compliance while boosting fuel efficiency through optimal load management. Emerging markets, experiencing rapid urbanization and infrastructure expansion, also exhibit a strong demand for GCUs, which are crucial for powering essential infrastructure like hospitals, schools, and commercial establishments. Together, these regulatory and technological advancements underscore GCUs' vital role in supporting fuel efficiency, environmental sustainability, and resilient power systems across diverse industries and regions.
Market Challenges Analysis
Challenges in Renewable Integration and Cybersecurity Concerns Integrating renewable energy sources like solar and wind with traditional power systems presents notable challenges for Generator Control Units (GCUs) due to the variable nature of renewables. The intermittency of solar and wind energy often causes fluctuations in power inputs, necessitating GCUs with the capability to adapt to these variations and maintain grid stability. For instance, the National Renewable Energy Laboratory (NREL) highlights that the variability of renewable energy sources requires advanced control algorithms to balance power loads effectively. Synchronizing multiple power sources, including traditional generators and renewables, requires advanced control algorithms that can seamlessly balance power loads, posing a complex technical hurdle. Meanwhile, the increasing digitization and connectivity of GCUs introduce vulnerabilities to cyber threats. As cyberattack risks grow, safeguarding GCUs from potential breaches becomes critical; a compromised control unit could lead to serious disruptions, including power outages and system failures. Therefore, implementing robust cybersecurity measures, such as encryption, firewalls, and real-time intrusion detection systems, is essential to protect these units from cyber threats and ensure reliable operation.
Cost, Standardization, and Technical Complexity The high initial costs of implementing advanced GCUs equipped with AI, machine learning, and IoT integration are significant challenges, as these technologies require substantial investment. Justifying these costs involves evaluating long-term benefits, including enhanced efficiency, reduced maintenance, and improved reliability. Standardization issues add further complexity; the lack of universal protocols and interface standards complicates interoperability between different GCU systems, often causing compatibility challenges when integrating units from multiple manufacturers. This lack of standardization not only impacts seamless operation but also leads to increased integration costs. Moreover, the technical complexity of GCUs, particularly in designing sophisticated control algorithms to optimize performance, demands specialized skills. Yet, the industry faces a skill gap, with a limited number of professionals proficient in GCU technology, which can hinder efficient installation, maintenance, and troubleshooting. Addressing these technical and financial obstacles is essential for facilitating broader adoption and smoother deployment of GCUs across diverse power generation scenarios.
Market Segmentation Analysis:
By Type:
The Generator Control Unit (GCU) market is segmented into analog-based and digital-based units. Analog-based GCUs, though simpler in design, remain preferred in applications requiring basic functionality due to their reliability and cost-effectiveness. However, digital-based GCUs dominate the market owing to their advanced features, such as remote monitoring, predictive maintenance, and IoT integration. These digital units are increasingly favored as industries focus on optimizing power management systems through sophisticated data analytics and real-time diagnostics. Digital GCUs also enhance operational efficiency and adaptability, allowing seamless integration with complex power networks and hybrid systems. The growth of digital GCUs reflects an industry-wide shift toward smart, data-driven control systems, especially in sectors where operational precision and monitoring are paramount.
By Application: The GCU market also spans diverse applications, including power plants, transportation, industrial manufacturing, and other specialized areas. Power plants, particularly renewable and hybrid plants, increasingly adopt GCUs for efficient power management and grid synchronization. In the transportation sector, GCUs play a vital role in maintaining power reliability for rail, marine, and aviation applications. Industrial manufacturing is a significant segment, utilizing GCUs to ensure uninterrupted operations and protect critical equipment during power fluctuations. Other applications include commercial buildings and remote locations where backup power is essential. This broad application spectrum highlights the versatility of GCUs, which adapt across industries that demand reliable power management solutions to meet operational and regulatory requirements.
Segments:
Based on Type:
- Analog Based
- Digital Based
Based on Application:
- Power Plant
- Transportation
- Industrial Manufacturing
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a substantial share in the Generator Control Units (GCU) market, driven by advanced infrastructure and a high demand for reliable power across various industries. With approximately 30% of the global market share, North America benefits from its focus on integrating advanced digital-based GCUs in sectors like healthcare, data centers, and manufacturing. The region’s adoption of renewable energy sources, coupled with stringent environmental regulations, has spurred the use of hybrid and smart GCU systems that optimize power management and minimize emissions. Furthermore, the presence of prominent GCU manufacturers and a strong emphasis on energy security support the market’s growth. This trend is anticipated to continue as North American industries increasingly adopt IoT-enabled and cybersecurity-enhanced GCU solutions to meet complex energy needs.
Asia-Pacific The Asia-Pacific region also commands a significant market share, accounting for roughly 25% of the global GCU market. Rapid industrialization, urbanization, and infrastructure expansion in countries such as China, India, and Japan are key factors driving demand. The region’s increasing power requirements, especially in off-grid and remote areas, emphasize the need for reliable backup power solutions, where GCUs play a crucial role. In addition, the region’s push toward renewable energy adoption, especially in China and India, has accelerated the integration of hybrid power systems, further boosting the demand for advanced GCUs. As Asia-Pacific continues its economic growth, the GCU market is set to expand, with digital and hybrid control units being adopted widely to support the region’s energy diversification and infrastructure modernization goals.
Key Player Analysis
- GE
- Comap
- DSE
- Kohler
- Emerson
- Avionic Instruments
- Deif
- Beckwith
- Smartgen
- Jenoptik
- HCT
- Lamar Technologies
- Dongguan Tuan Cheng
- Harsen
Competitive Analysis
The competitive landscape of the Generator Control Units (GCU) market is characterized by the presence of several leading players, including GE, Comap, DSE, Kohler, Emerson, Avionic Instruments, Deif, Beckwith, Smartgen, Jenoptik, HCT, Lamar Technologies, Dongguan Tuan Cheng, and Harsen. These companies focus on innovation and technological advancements, with many investing in smart GCUs that feature remote monitoring, predictive maintenance, and IoT integration. This focus on advanced technology enables companies to offer customizable solutions tailored to specific applications, enhancing their competitive edge. Furthermore, digitalization and cybersecurity are becoming increasingly important, with firms investing in robust security measures to protect their systems from cyber threats. The ongoing competition fosters continuous improvement in efficiency and reliability, driving growth in the GCU market as companies work to meet the rising demand for dependable power management solutions across various industries.
Recent Developments
- In July 2024, Kohler Energy announced an enhanced engine design for its KD Series generators, which incorporates improved generator performance, reduced emissions, and future-readiness for alternative fuels. The upgrade includes moving the engine control unit to the side for easier access.
- In April 2024, GE Vernova’s Gas Power business secured an order for its 7HA.03 combined-cycle plant equipment from Louisville Gas and Electric Company and Kentucky Utilities Company. The order includes GE’s integrated Mark VIe control system for gas turbine performance management.
- In 2023, Emerson sold a majority stake in its climate technologies business, which includes control systems, to Blackstone. The deal was approved by the Competition Commission of India.
Market Concentration & Characteristics
The market for Generator Control Units (GCUs) exhibits moderate concentration, characterized by a blend of established players and emerging companies. Leading firms leverage advanced technologies, such as smart GCUs equipped with IoT capabilities and predictive analytics, to differentiate their offerings. This focus on innovation drives competition, as companies strive to enhance efficiency, reliability, and user experience. Additionally, the market features a diverse range of applications, spanning industrial manufacturing, power plants, and transportation, which encourages specialization among manufacturers. The ongoing trend towards renewable energy integration further shapes the market dynamics, as GCUs must adapt to the unique requirements of hybrid systems. Moreover, stringent regulatory standards regarding emissions and fuel efficiency compel manufacturers to continuously improve their product performance. This combination of competitive rivalry and regulatory pressure fosters a dynamic environment, prompting companies to invest in research and development to stay ahead and meet the evolving needs of their customers.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market for Generator Control Units is expected to witness significant growth driven by increasing demand for reliable power supply across various sectors.
- The integration of renewable energy sources will become a critical factor, prompting advancements in GCU technology to manage hybrid systems effectively.
- Smart GCUs equipped with IoT capabilities will dominate the market, enhancing operational efficiency through remote monitoring and predictive maintenance.
- The trend toward digitalization will lead to the development of advanced digital GCUs offering improved data analytics and cybersecurity features.
- Governments will continue to impose stringent emission standards, compelling manufacturers to innovate and optimize engine performance.
- The rising cost of fuel will drive demand for more fuel-efficient generators, reinforcing the importance of GCUs in optimizing load sharing.
- Emerging markets will present new opportunities as rapid urbanization increases the need for reliable power solutions in developing countries.
- Investment in infrastructure development will spur demand for GCUs, particularly in sectors like healthcare, education, and telecommunications.
- As cyber threats become more prevalent, there will be a growing focus on enhancing cybersecurity measures within GCU systems.
- Collaborations and partnerships among industry players will intensify, fostering innovation and expanding product offerings to meet diverse customer needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Demand for Reliable Power Supply
Industries such as healthcare, data centers, and manufacturing require uninterrupted power to avoid operational disruptions and financial losses, driving the adoption of generator control units that ensure seamless power transitions and backup.
Growing Adoption of Renewable Energy Sources
The integration of solar and wind energy into power systems necessitates advanced GCUs to manage hybrid setups, balance variable inputs, and maintain grid stability, supporting the global shift toward sustainable energy.
Advancements in GCU Technology
Technological innovations, including smart GCUs with IoT integration, remote monitoring, and predictive maintenance, enhance operational efficiency and reduce downtime, making these solutions more attractive to end-users.
Stringent Emission Regulations and Fuel Efficiency Requirements
Governments are imposing stricter emission standards and fuel efficiency mandates, prompting industries to adopt GCUs that optimize generator performance, minimize emissions, and reduce operational costs.
Infrastructure Growth in Emerging Markets
Rapid urbanization and infrastructure development in emerging economies are increasing the need for reliable backup power solutions, boosting demand for GCUs in sectors such as healthcare, education, and commercial construction.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Generator Control Units market?
What factors are driving the growth of the Generator Control Units market?
What are the key segments within the Generator Control Units market?
What are some challenges faced by the Generator Control Units market?
Who are the major players in the Generator Control Units market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Analog Based
- 1.2.2 Digital Based
- 1.3 By Application
- 1.3.1 Power Plant
- 1.3.2 Transportation
- 1.3.3 Industrial Manufacturing
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 690.71 million → 2032: USD 1,086.84 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Generator Control Units Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Generator Control Units Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Generator Control Units Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Generator Control Units Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Generator Control Units Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Generator Control Units Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Generator Control Units Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Generator Control Units Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 690.71 million → 2032: USD 1,086.84 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Generator Control Units Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Analog Based
- 12.3.7.2 Digital Based
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Power Plant
- 12.4.7.2 Transportation
- 12.4.7.3 Industrial Manufacturing
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Generator Control Units End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Generator Control Units Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Generator Control Units Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Generator Control Units Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 GE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Comap
- 18.4 DSE
- 18.5 Kohler
- 18.6 Emerson
- 18.7 Deif
- 18.8 Smartgen
- 18.9 Jenoptik
- 18.10 Beckwith
- 18.11 Avionic Instruments
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

