
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electric Aircraft Market Size 2024 | USD 12,320.0 million |
| Electric Aircraft Market, CAGR | 20.40% |
| Electric Aircraft Market Size 2032 | USD 54,403.0 million |
Market Overview
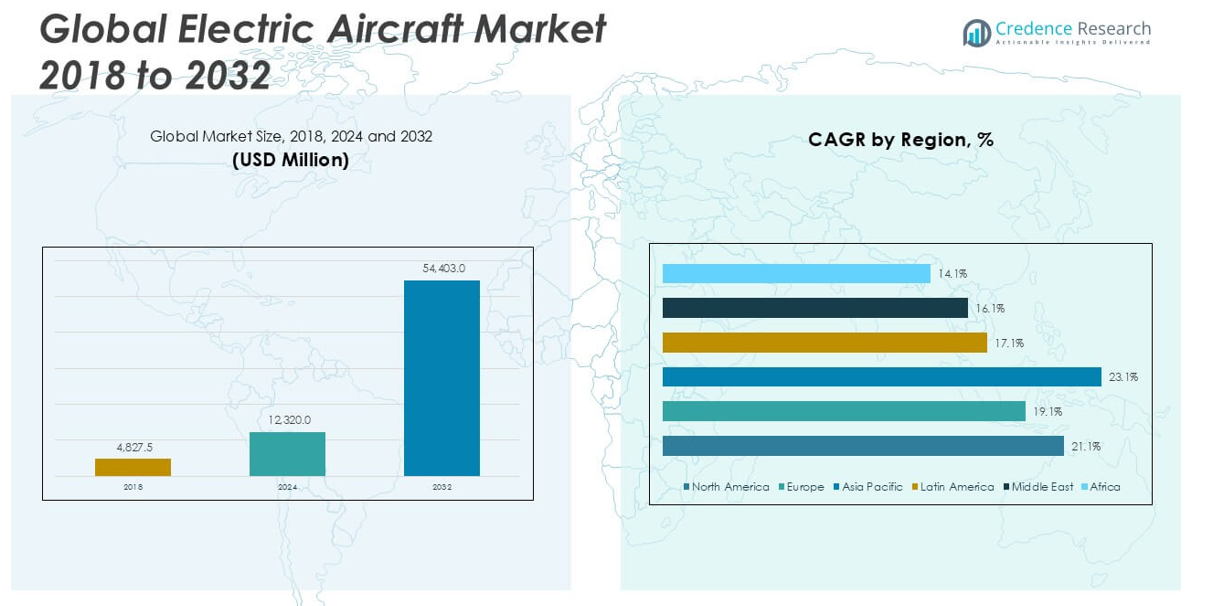
The Electric Aircraft market size was valued at USD 4,827.5 million in 2018, increased to USD 12,320.0 million in 2024, and is anticipated to reach USD 54,403.0 million by 2032, at a CAGR of 20.40% during the forecast period.
The Electric Aircraft market is driven by leading companies such as Airbus SE, Boeing, Joby Aviation, Eviation Aircraft, Pipistrel (Textron), Embraer, Vertical Aerospace, Lilium GmbH, Ampaire Inc., Beta Technologies, Wright Electric, Dufour Aerospace, ZeroAvia, and Bye Aerospace. These key players focus on expanding their electric aircraft portfolios through technological advancements and strategic collaborations to gain a competitive edge. North America leads the global Electric Aircraft market, holding a significant 35.0% market share in 2024, supported by strong investments, favorable regulations, and rapid adoption of electric aviation technologies. Europe and Asia Pacific follow closely, driven by sustainability initiatives and growing urban air mobility projects.
Market Insights
- The Electric Aircraft market was valued at USD 4,827.5 million in 2018, reached USD 12,320.0 million in 2024, and is expected to hit USD 54,403.0 million by 2032, growing at a CAGR of 20.40% during the forecast period.
- Growing environmental concerns, strict emission regulations, and advancements in battery technology are key drivers boosting the adoption of electric aircraft globally.
- Hybrid-electric technology holds the largest market share by technology due to its extended range and improved reliability, while North America leads the market with a 35.0% regional share in 2024.
- Companies like Airbus, Boeing, Joby Aviation, and Eviation Aircraft are focusing on strategic partnerships and product innovation to strengthen their market positions amid rising competition.
- Limited battery capacity, high development costs, and underdeveloped charging infrastructure are significant restraints that may slow the widespread adoption of electric aircraft, especially for long-distance flights.
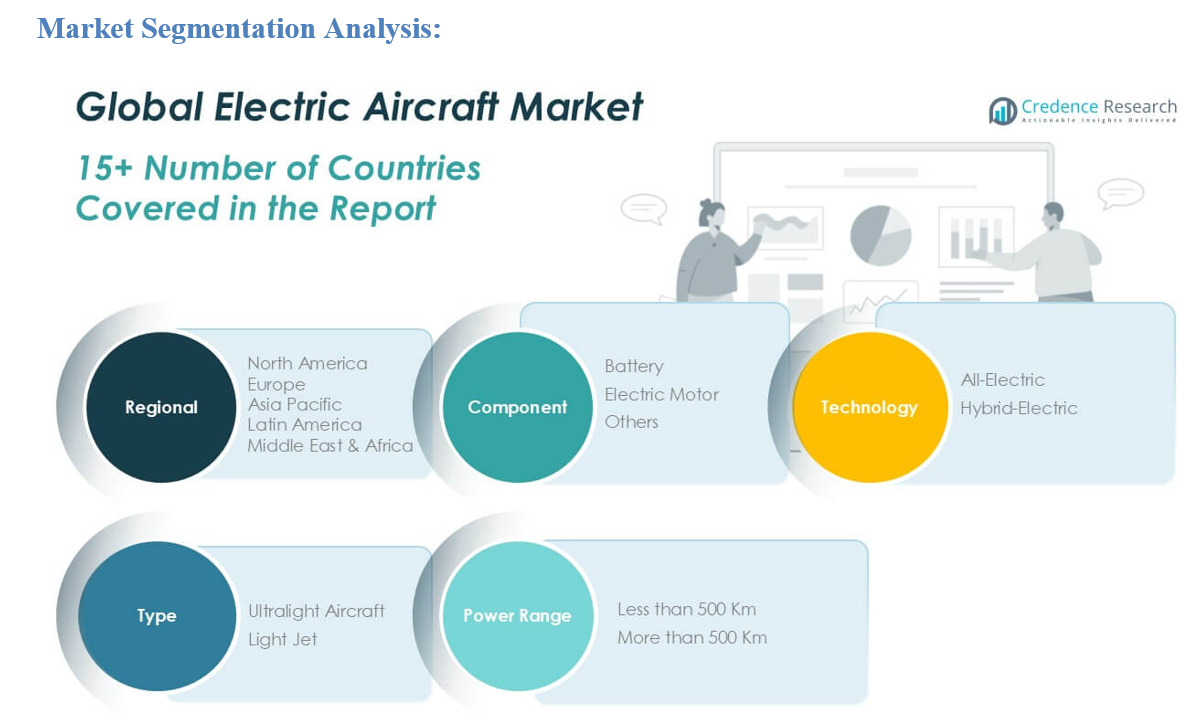
Market Segmentation Analysis:
By Component:
The battery segment dominates the Electric Aircraft market by component, accounting for the largest market share in 2024. The increasing adoption of advanced, lightweight, and high-capacity batteries significantly drives this segment's growth. Demand for efficient energy storage solutions and longer flight ranges enhances battery integration in electric aircraft. In contrast, the electric motor segment is also growing steadily due to technological advancements improving power-to-weight ratios. Other components, including controllers and power electronics, support the system but hold a smaller market share compared to batteries and motors.
- For instance, Pipistrel’s Velis Electro is powered by a 24.8 kWh battery system, enabling it to complete flights of up to 50 minutes with an additional reserve, demonstrating efficient energy storage integration in light electric aircraft.
By Technology
The hybrid-electric segment leads the Electric Aircraft market by technology, capturing the dominant market share in 2024. The strong preference for hybrid systems is driven by their extended range, improved reliability, and gradual transition from conventional to fully electric propulsion. All-electric aircraft, though advancing, currently face limitations due to battery capacity and range constraints, especially in commercial aviation. The increasing focus on sustainability, fuel efficiency, and regulatory support for low-emission aviation significantly propels the hybrid-electric segment’s growth within the forecast period.
- For instance, Ampaire’s Electric EEL hybrid-electric aircraft has successfully demonstrated flight ranges exceeding 1,609 kilometers using a combination of a 200 kW electric motor and a traditional combustion engine, significantly extending operational range.
By Type
The ultralight aircraft segment holds the largest share in the Electric Aircraft market by type in 2024. These aircraft are widely adopted due to their lower operating costs, simplified regulatory approval, and suitability for short-distance, low-capacity applications. The increasing use of ultralight electric aircraft for recreational flying, pilot training, and aerial surveillance drives segment growth. The light jet segment, although growing, still lags behind due to technological and regulatory hurdles related to battery efficiency and flight endurance in larger aircraft models.
Market Overview
Rising Environmental Concerns and Emission Regulations
The growing focus on reducing carbon emissions and addressing climate change strongly drives the electric aircraft market. Governments and international aviation authorities are implementing stringent emission regulations, prompting manufacturers to develop sustainable, low-emission alternatives. Electric aircraft offer a viable solution to the aviation industry's carbon footprint, aligning with global sustainability goals. The push for greener aviation is encouraging airlines and aircraft manufacturers to invest heavily in electric propulsion systems, boosting market expansion across both commercial and private aviation sectors.
- For instance, ZeroAvia successfully completed a hydrogen-electric flight of a six-seat Piper M-Class aircraft over 402 kilometers in 2021, achieving zero-emission operation and setting a benchmark for sustainable aviation targets.
Advancements in Battery Technology
Rapid improvements in battery technology significantly contribute to the growth of the electric aircraft market. Innovations such as higher energy density, faster charging capabilities, and longer battery life are enabling electric aircraft to achieve greater range and efficiency. The development of next-generation solid-state batteries and lightweight materials further enhances aircraft performance. These advancements reduce operational costs and improve flight feasibility, making electric aircraft more commercially attractive and operationally viable for various applications including passenger transport, cargo, and urban air mobility.
- For instance, Bye Aerospace’s eFlyer 2 employs a lithium-ion battery system with a demonstrated energy density of 260 Wh/kg, supporting flight durations exceeding three hours on a single charge.
Growing Demand for Urban Air Mobility
The increasing interest in urban air mobility (UAM) solutions is a major growth driver for the electric aircraft market. Electric Vertical Take-Off and Landing (eVTOL) aircraft are gaining popularity for short-distance, intra-city transportation, driven by the need to alleviate urban traffic congestion. Companies and governments are investing in electric air taxis and infrastructure to support this emerging segment. The potential for efficient, low-noise, and sustainable urban transport is accelerating the development and commercialization of electric aircraft for urban mobility services.
Key Trends & Opportunities
Strategic Collaborations and Investments
The electric aircraft market is witnessing a surge in partnerships, mergers, and investments aimed at accelerating technological progress. Aircraft manufacturers, battery developers, and aviation startups are collaborating to bring electric propulsion solutions to market faster. Government grants and venture capital funding are further supporting research and commercialization efforts. These strategic collaborations open significant opportunities for companies to leverage shared expertise, reduce development time, and meet the growing demand for sustainable aviation solutions.
- For instance, in 2021, United Airlines and Archer Aviation announced a partnership including an order for 200 eVTOL aircraft, backed by a $1 billion investment, to advance urban air mobility and sustainable air transport.
Expansion of Charging Infrastructure
The gradual expansion of electric aircraft charging and maintenance infrastructure presents key market opportunities. Airport authorities and urban planners are increasingly focusing on developing dedicated charging stations and support systems for electric aircraft. Building a reliable, standardized infrastructure network is crucial to facilitating the large-scale adoption of electric aviation, particularly for regional flights and urban air mobility. This trend is expected to create new revenue streams for infrastructure providers and contribute to the overall market growth.
- For instance, Lilium is working with Ferrovial to develop at least ten vertiports across Florida, with each designed to accommodate high-frequency electric air taxi operations and charging needs.
Key Challenges
Limited Battery Capacity and Flight Range
Despite technological advancements, limited battery capacity and restricted flight range remain significant challenges in the electric aircraft market. Current battery technologies are not yet capable of supporting long-haul flights, restricting electric aircraft use primarily to short-distance travel. The heavy weight of batteries also impacts payload capacity and aircraft efficiency. Overcoming these limitations will require substantial progress in battery energy density and lightweight material integration to make electric aircraft competitive with conventional alternatives.
High Initial Investment and Certification Complexity
The electric aircraft industry faces challenges related to high development costs and complex certification processes. Designing, testing, and certifying electric propulsion systems under rigorous safety standards require significant financial resources and time. The regulatory environment for electric aviation is still evolving, creating uncertainty for manufacturers and investors. These barriers can delay product launches and limit market entry for smaller companies without substantial capital backing or regulatory expertise.
Underdeveloped Supporting Infrastructure
The lack of established charging, maintenance, and operational infrastructure for electric aircraft presents a critical obstacle to market growth. Airports, especially in developing regions, are not yet equipped to support electric aircraft operations. The absence of standardized charging protocols and limited support facilities hampers the scalability of electric aviation. Addressing this challenge will require coordinated efforts between governments, airport authorities, and industry stakeholders to build a comprehensive and accessible infrastructure network.
Regional Analysis
North America
North America held a dominant position in the Electric Aircraft market in 2024, with a market size of USD 4,312.0 million, growing from USD 1,931.0 million in 2018. The region is projected to reach USD 16,320.9 million by 2032, advancing at a robust CAGR of 18.7% during the forecast period. In 2024, North America accounted for approximately 35.0% of the global market share, driven by strong technological advancements, supportive government policies, and significant investments in electric aviation infrastructure. The United States leads the region, with increasing adoption of electric aircraft for both commercial and urban air mobility applications.
Europe
Europe represented a significant share of the Electric Aircraft market in 2024, valued at USD 3,449.6 million, up from USD 1,264.8 million in 2018. The market is anticipated to reach USD 16,320.9 million by 2032, progressing at a CAGR of 21.6% during the forecast period. Europe contributed around 28.0% to the global market share in 2024, driven by stringent environmental regulations and ambitious sustainability goals set by the European Union. Countries such as Germany, France, and the UK are actively supporting the development and deployment of electric aircraft, with growing initiatives for greener aviation solutions and urban air mobility systems.
Asia Pacific
The Asia Pacific Electric Aircraft market experienced rapid growth from USD 999.3 million in 2018 to USD 3,080.0 million in 2024 and is expected to reach USD 16,429.7 million by 2032, registering the highest CAGR of 23.9% during the forecast period. Asia Pacific accounted for approximately 25.0% of the global market share in 2024, with China and Japan leading advancements in electric aviation technologies. Increasing urbanization, rising air traffic, and substantial investments in electric vertical take-off and landing (eVTOL) infrastructure are fueling market expansion in the region, along with strong government backing to reduce aviation-related carbon emissions.
Latin America
Latin America’s Electric Aircraft market grew from USD 226.9 million in 2018 to USD 616.0 million in 2024 and is projected to reach USD 3,264.2 million by 2032, expanding at a CAGR of 23.4% during the forecast period. In 2024, Latin America held nearly 5.0% of the global market share. The region shows growing interest in sustainable aviation solutions, particularly in Brazil and Mexico, where urban air mobility projects are emerging. The increasing need for efficient and cost-effective transportation in densely populated cities is expected to support the gradual adoption of electric aircraft across the region.
Middle East
The Middle East Electric Aircraft market expanded from USD 289.7 million in 2018 to USD 492.8 million in 2024 and is forecasted to reach USD 1,088.1 million by 2032, growing at a CAGR of 10.1% during the forecast period. In 2024, the region contributed approximately 4.0% to the global market share. The Middle East is focusing on modernizing its aviation sector with smart and eco-friendly solutions, especially in the United Arab Emirates and Saudi Arabia. Regional initiatives to develop smart cities and integrate urban air mobility systems are expected to gradually enhance the demand for electric aircraft.
Africa
Africa’s Electric Aircraft market grew from USD 115.9 million in 2018 to USD 369.6 million in 2024 and is expected to reach USD 979.3 million by 2032, registering a CAGR of 13.2% during the forecast period. In 2024, Africa held nearly 3.0% of the global market share. While the market is still in its early stages, rising interest in affordable, low-emission transportation options is driving slow but steady growth. Countries such as South Africa and Kenya are exploring electric aviation to improve regional connectivity and reduce dependence on conventional fuels, presenting long-term opportunities despite current infrastructure challenges.
Market Segmentations:
By Component
- Battery
- Electric Motor
- Others
By Technology
- All-Electric
- Hybrid-Electric
By Type
- Ultralight Aircraft
- Light Jet
By Power Range
- Less than 500 Km
- More than 500 Km
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Electric Aircraft market is highly competitive and rapidly evolving, with key players focusing on technological advancements, strategic partnerships, and product innovation to strengthen their market positions. Leading companies such as Airbus SE, Boeing, Joby Aviation, and Eviation Aircraft are heavily investing in research and development to improve battery efficiency, enhance flight range, and reduce operating costs. Startups like Lilium GmbH, Vertical Aerospace, and Beta Technologies are driving innovation in electric vertical take-off and landing (eVTOL) aircraft, targeting urban air mobility solutions. Major aerospace manufacturers are collaborating with technology providers to accelerate product development and gain regulatory approvals. Market participants are also actively pursuing mergers, acquisitions, and funding rounds to expand their portfolios and global reach. The competitive environment is marked by the race to achieve commercial viability, cost efficiency, and safety compliance, with companies striving to secure early-mover advantages in both regional and short-haul aviation markets.
Key Player Analysis
- Airbus SE
- Boeing
- Joby Aviation
- Eviation Aircraft
- Pipistrel (Textron)
- Embraer
- Vertical Aerospace
- Lilium GmbH
- Ampaire Inc.
- Beta Technologies
- Wright Electric
- Dufour Aerospace
- ZeroAvia
- Bye Aerospace
Recent Developments
- In May 2025, a U.S.-based startup, Whisper Aero, announced its plans to design and prototype a series of hybrid-electric autonomous cargo aircraft over the next three years. The project is being supported through funding from the U.S. Air Force, underlining the military’s growing interest in advanced, sustainable aviation technologies.
- In October 2023, GE Aerospace researchers plan to build and demonstrate a small engine prototype powered by fuel cells and sustainable aviation fuel (SAF) to help promote more sustainable flight. Secured USD 4.5 million in Phase 2 funding under the ARPA-E REEACH program to build and demonstrate a 25 kW small-scale power generation subsystem combining a solid oxide fuel cell and turbofan engine Gas tanks use SAF.
- In September 2023, A consortium led by Honeywell International recently launched a European Clean Aviation project that will develop a new generation of hydrogen fuel cells for the aviation industry. The Project involves multidisciplinary collaboration between 18 partners from 10 European countries to develop an aerospace-qualified megawatt-class fuel cell propulsion system powered by hydrogen.
- In June 2023, A team of MIT engineers have unveiled the creation of a 1-megawatt motor that could be an important step toward electrifying larger airplanes. The team designed and tested the main components of the engine and presented, through detailed calculations, that the combined components could operate as a whole to produce one megawatt of power at this weight and size, compared with the competitive size of today's small-engine aircraft.
- In June 2023, The Pentagon awarded a contract worth over USD 2 billion for the upcoming batch of F-35 engines to Pratt & Whitney. The deal for Lot 17 F135 engines, totaling USD 2.02 billion, is predicted to be completed by December 2025.
- In May 2023, Alaska Airlines demonstrated a Bombardier Q400 regional turbojet that is equipped with a hydrogen-electric propulsion system at ZeroAvia to expand the reach and applicability of its zero-emissions flight technology. ZeroAvia, a U.S. leader in the design and manufacture of zero-emission hydrogen-electric aircraft propulsion systems, will develop the 76-seat Q400 aircraft.
- In January 2023, Eviation Aircraft secured a contract from Aerus, an emerging regional airline in Mexico, for the supply of 30 of its commuter Alice aircraft. Aerus intends to utilize Alice for middle-mile travel across regions including Nuevo León, Tamaulipas, Coahuila, and Veracruz, providing historically underserved communities in northern areas of the country with access to carbon-free, cost-effective, and convenient air travel.
Market Concentration & Characteristics
The Electric Aircraft Market is moderately concentrated, with a mix of established aerospace leaders and emerging electric aviation startups driving competition. It features strong participation from companies such as Airbus, Boeing, Joby Aviation, and Eviation Aircraft, which are investing in research, development, and strategic partnerships to advance electric propulsion technologies. It is characterized by rapid innovation, a high degree of technological collaboration, and growing regulatory involvement aimed at setting safety and efficiency standards. The market shows a clear focus on urban air mobility, short-haul flights, and sustainable aviation solutions, with manufacturers prioritizing battery efficiency, lightweight materials, and cost-effective designs. Demand is centered on ultralight aircraft and electric vertical take-off and landing (eVTOL) models, while larger commercial electric aircraft remain under development. The market reflects high barriers to entry due to certification complexity, capital requirements, and the need for extensive technical expertise. It is also influenced by infrastructure readiness and the gradual establishment of charging networks, which currently limit large-scale deployment. Players in this space are racing to develop viable electric aircraft that meet both performance expectations and emerging regulatory frameworks.
Report Coverage
The research report offers an in-depth analysis based on Component, Technology, Type, Power Range and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Electric Aircraft market will see strong growth driven by increasing demand for sustainable aviation solutions.
- Hybrid-electric and all-electric propulsion systems will become more commercially viable with advancements in battery technology.
- Urban air mobility applications such as air taxis and eVTOL aircraft will gain significant traction in major cities.
- Key market players will continue to invest heavily in research and development to improve aircraft range and efficiency.
- Regulatory bodies will introduce clear certification pathways and safety standards tailored for electric aviation.
- Charging infrastructure for electric aircraft will gradually expand across regional airports and urban centers.
- Strategic collaborations between aerospace companies, battery manufacturers, and technology providers will increase.
- Demand for ultralight and short-haul electric aircraft will dominate the market in the near term.
- Competitive pressure will intensify as new entrants and startups challenge established aerospace companies.
- Government support through funding, subsidies, and sustainability policies will play a critical role in accelerating adoption.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Emission Regulations and Environmental Concerns
Governments and international aviation authorities are enforcing strict emission standards, pushing manufacturers and airlines to adopt electric aircraft as a sustainable alternative to conventional aviation, thereby accelerating market growth.
Advancements in Battery Technology
Rapid improvements in battery energy density, charging speed, and lifecycle are enabling electric aircraft to achieve longer ranges and greater operational efficiency, making them more commercially viable for a wider range of applications.
Growth of Urban Air Mobility (UAM)
The rising demand for efficient, low-emission transportation in congested urban areas is driving investments in electric vertical take-off and landing (eVTOL) aircraft and supporting infrastructure, expanding the market for electric aircraft in urban mobility solutions.
Strategic Collaborations and Investments
Major aerospace companies, startups, and technology providers are forming partnerships and securing funding to accelerate the development and commercialization of electric aircraft, fostering innovation and reducing time-to-market for new products.
Supportive Government Policies and Funding
Government incentives, grants, and regulatory support for sustainable aviation are reducing barriers to entry and encouraging both established players and new entrants to invest in electric aircraft technologies.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Electric Aircraft Market?
What are the key segments within the Electric Aircraft Market?
What are some challenges faced by the Electric Aircraft Market?
Who are the major players in the Electric Aircraft Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Ultralight Aircraft
- 1.2.2 Light Jet
- 1.3 By Component
- 1.3.1 Battery
- 1.3.2 Electric Motor
- 1.3.3 Others
- 1.4 By Technology
- 1.4.1 All-Electric
- 1.4.2 Hybrid-Electric
- 1.5 By Power Range
- 1.5.1 Less than 500 Km
- 1.5.2 More than 500 Km
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 12,320.0 million → 2032: USD 54,403.0 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electric Aircraft Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electric Aircraft Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Electric Aircraft Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Electric Aircraft Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electric Aircraft Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electric Aircraft Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electric Aircraft Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electric Aircraft Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 12,320.0 million → 2032: USD 54,403.0 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electric Aircraft Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Ultralight Aircraft
- 12.3.7.2 Light Jet
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Battery
- 12.4.7.2 Electric Motor
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 All-Electric
- 12.5.7.2 Hybrid-Electric
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Power Range - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Volume Forecast, 2018-2032
- 12.6.5 Base-Year Market Share, 2018
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Less than 500 Km
- 12.6.7.2 More than 500 Km
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electric Aircraft Geographic Market Outlook, 2018-2032
- 13.1 Regional Market Size and Share, 2018
- 13.2 Regional Market Forecast, 2018-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Electric Aircraft Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2018-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Electric Aircraft Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2018
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2018-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Airbus SE
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Boeing
- 17.4 Joby Aviation
- 17.5 Eviation Aircraft
- 17.6 Pipistrel (Textron)
- 17.7 Embraer
- 17.8 Vertical Aerospace
- 17.9 Lilium GmbH
- 17.10 Ampaire Inc.
- 17.11 Beta Technologies
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

