
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
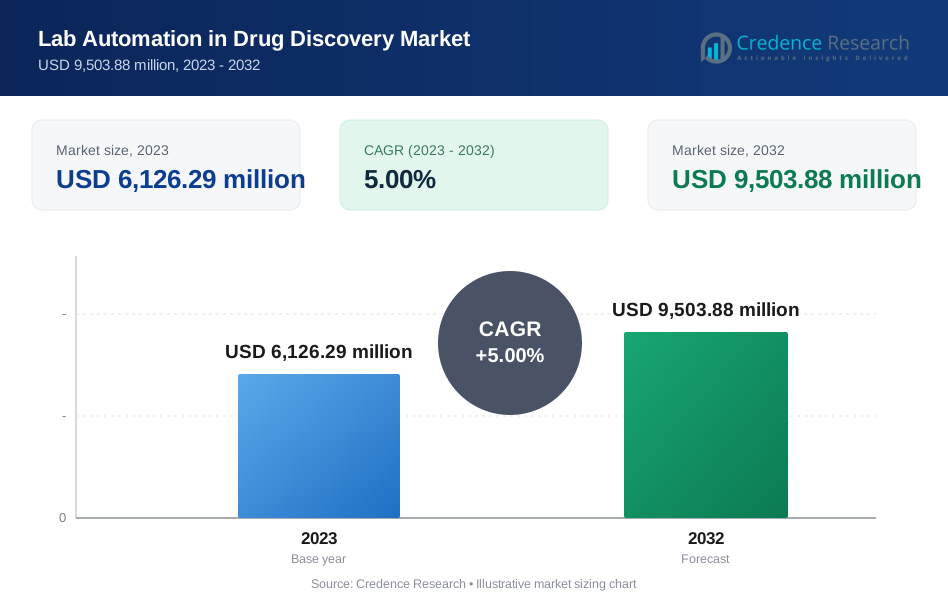
| Lab Automation in Drug Discovery Market Size 2023 | USD 6,126.29 Million |
| Lab Automation in Drug Discovery Market, CAGR | 5.00% |
| Lab Automation in Drug Discovery Market Size 2032 | USD 9,503.88 Million |
Market Overview
The Lab Automation in Drug Discovery Market is projected to grow from USD 6,126.29 million in 2023 to USD 9,503.88 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.00%.
The Lab Automation in Drug Discovery Market is driven by the increasing demand for efficient and high-throughput screening processes, which accelerate drug discovery and development. The need to reduce human error, improve data accuracy, and enhance productivity in laboratories is pushing the adoption of automated systems. Advancements in robotics, artificial intelligence, and machine learning are further transforming lab automation, enabling more precise and faster drug discovery processes. Additionally, the growing focus on personalized medicine and the rising prevalence of chronic diseases are fueling the demand for automated solutions that can handle large volumes of complex data efficiently.
The Lab Automation in Drug Discovery Market is primarily concentrated in regions such as North America, Europe, and Asia-Pacific, with North America holding the largest market share due to its advanced healthcare infrastructure and significant investment in research and development. Europe follows closely, driven by stringent regulatory standards and a strong focus on innovation. The Asia-Pacific region is experiencing rapid growth, supported by expanding pharmaceutical industries and increasing healthcare investments. Key players dominating the market include Thermo Fisher Scientific, Beckman Coulter (Danaher), Agilent Technologies, Siemens Healthineers, and Roche, all known for their comprehensive automation solutions and strong global presence.
Market Drivers
Increased Demand for Efficiency and Productivity
The pharmaceutical industry is under immense pressure to accelerate drug development, driving the need for increased efficiency and productivity in laboratories. For instance, pharmaceutical companies have been striving to improve their productivity since the beginning of the new millennium. They scored early success by bringing down selling, general, and administrative (SG&A) expenses between 2004 and 2011, but more recent cost-reduction efforts have yet to reshape the structure of their P&L. Automation plays a crucial role in streamlining drug discovery processes, significantly reducing turnaround times and increasing throughput. By automating repetitive tasks, laboratories can focus on more complex aspects of research, ultimately bringing new drugs to market faster. Additionally, automation leads to substantial cost savings by minimizing manual labor, reducing the likelihood of human errors, and decreasing material waste. These benefits are compelling more pharmaceutical companies to adopt lab automation as a strategic investment, ensuring they remain competitive in a fast-paced industry.
Rising Regulatory Pressures
Stringent regulatory standards, such as those set by the FDA and EMA, are placing increased pressure on pharmaceutical companies to ensure compliance throughout the drug development process. For instance, regulatory updates have been coming thick and fast in Life Sciences in recent years, in step with the accelerating pace of change in the industry. One of the most notable changes for drug manufacturers in 2023 has been the updated ICH Q9 guidance on quality risk management. Lab automation helps meet these regulatory requirements by improving data integrity and traceability, which are critical for quality control and compliance. Automated systems reduce the risk of errors and provide a clear audit trail, ensuring that all data generated during the drug discovery process is accurate, reliable, and easily accessible for regulatory review. As regulatory bodies continue to emphasize data integrity, the adoption of lab automation solutions is becoming increasingly necessary to maintain compliance and avoid costly penalties.
Technological Advancements
Advancements in technology are a key driver of the lab automation market, particularly in the miniaturization of equipment, which allows laboratories to optimize space and reduce operational costs. The integration of advanced software solutions is further enhancing the efficiency of automated systems by facilitating seamless data management, analysis, and integration with other laboratory systems. Robotics and artificial intelligence (AI) are at the forefront of innovation in lab automation, enabling laboratories to perform complex tasks with greater precision and consistency. These technologies are not only improving the accuracy of experiments but also increasing the speed at which drug discovery processes can be completed, making them indispensable tools in modern laboratories.
Growing Complexity of Drug Discovery and Global Market Expansion
The complexity of drug discovery is growing, particularly with the rise of target-based approaches and the increasing focus on personalized medicine. These developments require high-throughput screening and analysis, which are made possible by advanced automation systems. Automated platforms enable laboratories to conduct precise and reproducible experiments, which are essential for the development of personalized therapies tailored to individual patient profiles. Additionally, the global expansion of the pharmaceutical industry, particularly in emerging markets with rising healthcare expenditures, is driving demand for lab automation solutions. The outsourcing of drug discovery activities to contract research organizations (CROs) is also contributing to market growth, as CROs seek to enhance their capabilities and offer more competitive services through the adoption of cutting-edge automation technologies.
Market Trends
Integration with Artificial Intelligence (AI) and Cloud-Based Solutions
The integration of artificial intelligence (AI) into lab automation systems is revolutionizing the drug discovery process by enabling intelligent decision-making, optimizing workflows, and enhancing data analysis. AI-driven automation allows laboratories to handle complex tasks more efficiently and accurately, thereby reducing the time and costs associated with drug development. Machine learning algorithms are employed to analyze large datasets generated by automated experiments, uncovering patterns and insights that would be difficult for humans to detect. This capability is particularly valuable in identifying potential drug targets and predicting the outcomes of experiments, which accelerates the development of new therapies. Alongside AI, cloud-based solutions are transforming laboratory operations by providing remote access to equipment and data. These platforms enable researchers to collaborate seamlessly from different locations, enhancing flexibility and efficiency. Cloud-based solutions also offer scalability, allowing laboratories to adjust their resources based on changing demands, thereby reducing upfront costs and enabling more efficient management of laboratory operations.
Digital Transformation and Focus on Data Analytics
The digital transformation of laboratories is a key trend shaping the future of lab automation in drug discovery. For instance, the application of Industry 4.0 principles, often referred to as Lab 4.0, has the potential to accelerate innovation by streamlining and automating processes and driving more insightful data analysis. The shift towards paperless laboratories, facilitated by the adoption of digital lab notebooks and electronic records, is streamlining laboratory operations, improving data management, and reducing the likelihood of errors. This digitalization ensures that all data is accurately recorded and easily accessible, supporting compliance with regulatory requirements and enhancing the reproducibility of experiments. The integration of Internet of Things (IoT) devices into lab automation systems further optimizes laboratory workflows by monitoring equipment performance, tracking inventory, and ensuring optimal operating conditions. The focus on data analytics is also driving significant changes in the market, with advanced tools being used to extract valuable insights from the vast amounts of data generated by automated systems. Predictive analytics is becoming increasingly important, helping laboratories identify potential bottlenecks, optimize experimental protocols, and improve the overall efficiency of the drug discovery process. By leveraging data-driven insights, pharmaceutical companies can make informed decisions, reduce development timelines, and enhance the success rates of their drug discovery efforts. These technological advancements are not only improving the quality and speed of research but also positioning the industry to meet the growing demand for innovative and effective therapies.
Market Challenges Analysis
High Initial Investment and Complexity of Integration
The implementation of lab automation systems in drug discovery comes with high initial investment costs, which can be a significant barrier, especially for smaller laboratories or organizations operating with limited budgets. For instance, a basic automation system, which includes a feeder and an automated centrifuge, could cost at least $300,000. Lab automation has typically been a serious capital investment, with prices typically ranging from $25,000 up to $200,000 for a high-performance liquid handling robot. The substantial upfront expenses include not only the cost of purchasing sophisticated equipment but also the infrastructure modifications needed to accommodate these systems. These financial barriers can limit the widespread adoption of automation, particularly in developing regions or smaller-scale operations. In addition to cost concerns, the integration of lab automation systems with existing laboratory infrastructure poses its own set of challenges. Integrating new technologies into established workflows can be complex and time-consuming, often requiring specialized expertise to ensure compatibility and seamless operation. Managing the vast amounts of data generated by automated systems adds another layer of complexity, necessitating robust data management solutions capable of handling and analyzing large datasets efficiently. Without proper data management, the potential benefits of lab automation, such as improved accuracy and throughput, can be undermined.
Standardization, Skill Gap, and Regulatory Compliance
A lack of standardization and interoperability between different lab automation systems can hinder their effectiveness, as the absence of standardized protocols and data formats makes it difficult for various systems to communicate and function cohesively. This issue can limit the flexibility and scalability of lab automation solutions, potentially reducing their efficiency and utility in complex drug discovery processes. Furthermore, the successful operation and maintenance of lab automation systems require specialized skills and training, which can be a challenge to find, particularly in certain regions. This skill gap can lead to operational inefficiencies and increased reliance on external support, raising costs and affecting productivity. Regulatory compliance is another critical challenge, as ensuring that lab automation systems meet the stringent requirements set by regulatory bodies such as the FDA and EMA can be both time-consuming and costly. The process of validation and qualification is essential to demonstrate that automated systems are reliable and produce accurate results, but it adds to the operational burden. Additionally, equipment failures and maintenance issues can lead to downtime, disrupting laboratory operations and negatively impacting productivity. Overcoming resistance to change within organizations is also a common hurdle, as lab personnel may be reluctant to adopt new technologies, preferring traditional methods due to familiarity and comfort. Addressing these challenges is crucial for maximizing the benefits of lab automation and ensuring its successful integration into the drug discovery process.
Market Segmentation Analysis:
By Type:
The Global Lab Automation in Drug Discovery Market is segmented by type, which includes automated liquid handlers, automated plate handlers, robotic arms, automated storage and retrieval systems, and others. Automated liquid handlers represent a significant segment due to their widespread use in handling precise volumes of liquid, which is essential in high-throughput screening and assay preparation. Automated plate handlers are also crucial, particularly in applications involving microplate handling for assays and sample storage. Robotic arms are integral to automating complex tasks that require high precision and repeatability, enhancing efficiency in drug discovery workflows. Automated storage and retrieval systems are increasingly being adopted to manage large volumes of samples, ensuring quick and accurate sample handling, which is vital in large-scale research environments. The "Others" category includes various specialized automation tools that cater to specific needs in drug discovery, contributing to the overall growth and diversity of the market by providing tailored solutions that enhance laboratory productivity and accuracy.
By Application:
Based on application, the Global Lab Automation in Drug Discovery Market is categorized into hospitals and private labs, biotech and pharma, academics and research institutes, and others. The biotech and pharma segment dominates the market, driven by the need for high-throughput screening, compound management, and complex data analysis in drug discovery processes. Automation enables these companies to accelerate drug development timelines, improve data accuracy, and reduce operational costs. Hospitals and private labs are increasingly adopting lab automation to enhance diagnostic capabilities, streamline workflows, and maintain compliance with regulatory standards. Academics and research institutes also represent a significant market segment, utilizing automation to conduct innovative research and facilitate large-scale studies that require precise and reproducible results. The "Others" category includes contract research organizations and other specialized facilities that leverage lab automation to optimize their drug discovery and development processes, ensuring they remain competitive in a rapidly evolving industry landscape.
Segments:
Based on Type:
- Automated Liquid Handlers
- Automated Plate Handlers
- Robotic Arms
- Automated Storage and Retrieval Systems
- Others
Based on Application:
- Hospitals and Private Labs
- Biotech and Pharma
- Academics and Research Institutes
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America dominates the market with an impressive market share of approximately 45%. This region's leadership position stems from its robust pharmaceutical and biotechnology industries, substantial research and development investments, and early adoption of cutting-edge technologies. The United States, in particular, drives much of North America's market growth, hosting numerous global pharmaceutical giants and innovative biotech startups. These companies leverage advanced lab automation solutions to accelerate drug discovery processes, enhance research efficiency, and reduce costs. North American laboratories excel in implementing high-throughput screening systems, automated liquid handling platforms, and sophisticated data management tools. The region's strong focus on personalized medicine and genomics further fuels the demand for automated lab solutions capable of handling complex, data-intensive research protocols.
Europe
Europe holds a significant market share of about 30% in the lab automation for drug discovery sector, showcasing a strong commitment to pharmaceutical innovation and technological advancement. Countries like Germany, Switzerland, and the United Kingdom lead the European market, boasting a dense network of pharmaceutical companies, contract research organizations, and academic institutions. European labs demonstrate particular strength in automated compound management systems and integrated workflow solutions that streamline the entire drug discovery pipeline. The region's stringent regulatory environment has spurred the development of automation systems with enhanced traceability and compliance features. Europe's lab automation market also benefits from collaborative initiatives between academia and industry, fostering the development of novel automation technologies tailored to emerging research areas such as biologics and cell-based therapies.
Key Player Analysis
- Thermo Fisher Scientific
- Beckman Coulter (Danaher)
- Hudson Robotics
- Becton
- Dickinson and Company
- Agilent Technologies
- Siemens Healthineers
- Tecan Group Ltd
- PerkinElmer
- Bio-Rad
- Roche
- Shimadzu Corporation
- Aurora Biomed
Competitive Analysis
The Global Lab Automation in Drug Discovery Market is highly competitive, with key players like Thermo Fisher Scientific, Beckman Coulter (Danaher), and Agilent Technologies leading the market due to their extensive product offerings and strong global distribution networks. These companies provide a wide range of automation solutions, including automated liquid handlers and robotic arms, catering to the diverse needs of pharmaceutical companies and research institutions. By leveraging technological expertise and investing in research and development, they introduce innovative products that enhance efficiency and accuracy in drug discovery processes. The competitive environment drives these companies to pursue strategic partnerships, acquisitions, and collaborations, enabling them to expand their market presence and maintain a competitive edge in the rapidly evolving field of lab automation.
Recent Developments
- In July 2024, Agilent Technologies signed a definitive agreement to acquire BIOVECTRA, a leading specialized contract development and manufacturing organization, for $925 million.
- In 2024, Thermo Fisher Scientific reported its financial results for the second quarter of 2024.
- In December 2023, Hudson Robotics and Art Robbins Instruments acquired Tomtec Inc., a provider of automated liquid handling instruments.
- In March 2023, PerkinElmer completed the divestiture of its Applied, Food and Enterprise Services businesses.
Market Concentration & Characteristics
The Global Lab Automation in Drug Discovery Market exhibits moderate to high market concentration, with a few key players holding significant market share due to their extensive product portfolios and advanced technological capabilities. Companies like Thermo Fisher Scientific, Beckman Coulter (Danaher), and Agilent Technologies dominate the market, leveraging their strong global distribution networks and continuous investment in innovation. The market is characterized by rapid advancements in robotics, artificial intelligence, and data management solutions, which are transforming drug discovery processes by enhancing efficiency, precision, and throughput. Despite the dominance of large players, the market remains dynamic, with emerging companies introducing specialized solutions that cater to niche applications in drug discovery. The competitive landscape is further shaped by strategic collaborations, mergers, and acquisitions, which allow companies to expand their product offerings and strengthen their market positions in this evolving sector.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Global Lab Automation in Drug Discovery Market is expected to see significant growth due to increasing demand for faster and more efficient drug development processes.
- Integration of artificial intelligence and machine learning into lab automation will enhance data analysis and optimize workflows.
- The adoption of cloud-based solutions will increase, offering scalable and flexible laboratory operations.
- Rising regulatory requirements will drive the need for automation to ensure compliance and improve data integrity.
- Advancements in robotics and miniaturization technology will continue to reduce costs and improve the precision of automated systems.
- Growing focus on personalized medicine will boost demand for high-throughput screening and automated testing.
- Emerging markets will see a rise in lab automation adoption, driven by expanding pharmaceutical industries and healthcare infrastructure.
- The need for standardized protocols and data formats will become more critical to ensure interoperability of different automation systems.
- Training and skill development programs will be essential to address the skill gap in operating and maintaining automated lab systems.
- Strategic partnerships and collaborations between technology providers and pharmaceutical companies will drive innovation and market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Lab Automation in Drug Discovery Market?
What factors are driving the growth of the Global Lab Automation in Drug Discovery Market?
What are the key segments within the Global Lab Automation in Drug Discovery Market?
What are some challenges faced by the Global Lab Automation in Drug Discovery Market?
Who are the major players in the Global Lab Automation in Drug Discovery Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Lab Automation in Drug Discovery Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Lab Automation in Drug Discovery Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 6,126.29 million → 2032: USD 9,503.88 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Lab Automation in Drug Discovery Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Lab Automation in Drug Discovery Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Lab Automation in Drug Discovery Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Lab Automation in Drug Discovery Market Drivers
- 3.3 Lab Automation in Drug Discovery Market Restraints & Challenges
- 3.4 Lab Automation in Drug Discovery Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Lab Automation in Drug Discovery Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Lab Automation in Drug Discovery Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Lab Automation in Drug Discovery category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Lab Automation in Drug Discovery Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Lab Automation in Drug Discovery Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Lab Automation in Drug Discovery. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Lab Automation in Drug Discovery Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Lab Automation in Drug Discovery Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Lab Automation in Drug Discovery Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Lab Automation in Drug Discovery (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Lab Automation in Drug Discovery
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Lab Automation in Drug Discovery Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Lab Automation in Drug Discovery Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Lab Automation in Drug Discovery Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Lab Automation in Drug Discovery Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Lab Automation in Drug Discovery Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Lab Automation in Drug Discovery Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Lab Automation in Drug Discovery Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Lab Automation in Drug Discovery Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
