
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Germany Bottled Water Market Size 2024 | USD 19,820.10 million |
| Germany Bottled Water Market, CAGR | 7.06% |
| Germany Bottled Water Market Size 2032 | USD 37,443.72 million |
Market Overview
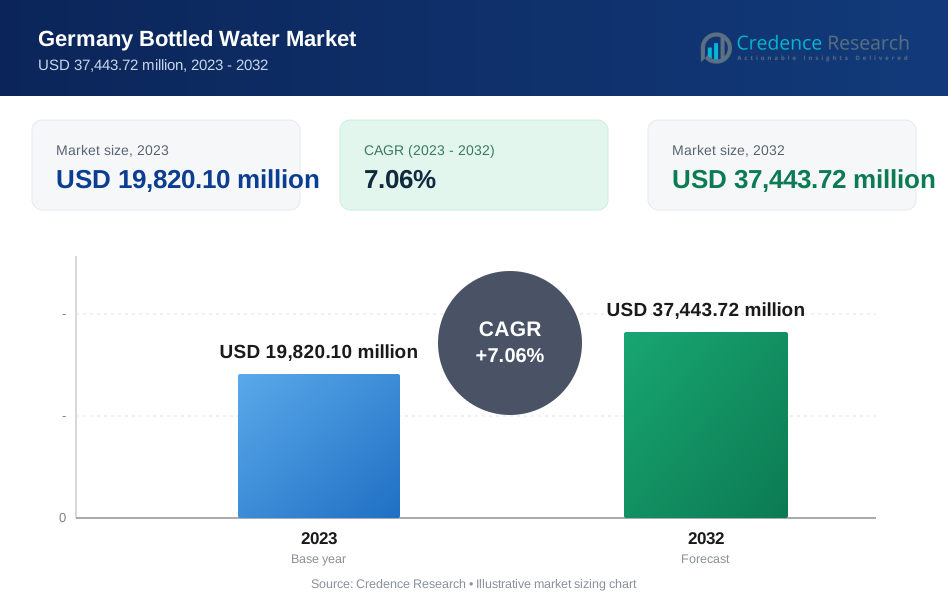
The Germany bottled water market is projected to grow from USD 19,820.10 million in 2023 to USD 37,443.72 million by 2032, registering a compound annual growth rate (CAGR) of 7.06% during the forecast period.
The Germany bottled water market is driven by increasing consumer preference for convenient and safe drinking water, fueled by rising health consciousness and urbanization. Growing awareness about hydration's role in maintaining overall well-being has significantly boosted demand for premium bottled water products, including mineral and sparkling water. The trend of sustainability is also shaping the market, with consumers favoring eco-friendly packaging solutions like recycled PET bottles. Additionally, advancements in water purification and filtration technologies have enhanced product quality, attracting a broader customer base. The market benefits from robust distribution networks, including supermarkets, online platforms, and vending machines, ensuring product accessibility. The rising popularity of flavored and functional water, infused with vitamins and minerals, reflects evolving consumer preferences for taste and health benefits. Together, these factors underscore the dynamic growth and innovation within the Germany bottled water market.
ermany's bottled water market exhibits regional diversity, driven by varying consumer preferences, lifestyle trends, and economic factors. Urban centers like Berlin, Munich, and Hamburg contribute significantly to market growth due to their dense populations, active lifestyles, and demand for premium and sustainable water products. In these cities, sparkling and functional waters are particularly popular, reflecting a broader shift toward health-conscious consumption. The market is supported by a strong distribution network, including retail stores and e-commerce platforms, ensuring wide accessibility. Key players shaping the competitive landscape include Nestlé, Danone SA, and Gerolsteiner Brunnen GmbH & Co. KG, known for their extensive product portfolios and focus on innovation. Companies like Sanpellegrino Group and RheinfelsQuellen H. Hovelmann GmbH & Co. KG leverage strong branding and sustainable practices to meet evolving consumer expectations. With rising demand for eco-friendly and premium products, these players continue to invest in new product development and sustainable packaging solutions.
Market Insights
- The Germany bottled water market is projected to grow from USD 19,820.10 million in 2023 to USD 37,443.72 million by 2032, at a CAGR of 7.06%.
- Increasing health consciousness among consumers is driving the demand for natural and functional bottled water.
- Rising environmental concerns are influencing brands to adopt sustainable packaging solutions like recyclable PET and glass bottles.
- The growing preference for sparkling and alkaline water is shaping product innovation in the market.
- Economic factors such as inflation and raw material costs pose challenges to premium bottled water sales.
- Urban areas like Berlin and Munich drive significant growth due to high consumption of premium and sustainable water products.
- Key players like Nestlé, Danone SA, and Gerolsteiner Brunnen GmbH focus on innovation and eco-friendly solutions to remain competitive.
Market Drivers
Health and Wellness Consciousness
The increasing emphasis on health and wellness is a primary driver of the German bottled water market. Consumers are becoming more aware of the importance of hydration in maintaining overall well-being, leading to a surge in water consumption. For instance, a survey by the German Federal Institute for Risk Assessment found that 70% of Germans consider hydration crucial for health. The market for functional waters, enriched with vitamins, minerals, and other additives, is expanding as consumers seek beverages that align with their health goals. This shift reflects a broader recognition of hydration as a critical component of healthy living, prompting many to opt for bottled water as a convenient and reliable choice.
Convenience and Evolving Lifestyles
Germany's fast-paced lifestyle has significantly increased the demand for convenient, on-the-go bottled water options. With a wide range of bottle sizes and formats, the market caters to diverse consumer needs, from compact bottles for portability to larger ones for home use. This versatility aligns with the preferences of busy individuals who value accessibility without compromising quality. For instance, a study by the German Society for Consumer Research found that 60% of consumers prefer bottled water for its convenience. The integration of bottled water into daily routines underscores its essential role in supporting modern lifestyles.
Environmental Concerns and Sustainability
Rising environmental awareness is reshaping consumer expectations, pushing bottled water brands to adopt sustainable practices. Eco-friendly packaging, such as bottles made from recycled plastic or aluminum, has gained popularity among environmentally conscious consumers. For instance, a report by the German Environmental Agency highlights that 80% of consumers prefer products with eco-friendly packaging. Additionally, local sourcing of water from regional springs resonates with the public's preference for reducing carbon footprints. By addressing these environmental concerns, companies are fostering consumer trust and contributing to long-term market growth.
Economic Prosperity and Market Trends
Germany's economic prosperity and rising disposable incomes have increased consumer willingness to invest in premium bottled water products. Sparkling water maintains its dominance, appealing to those who favor effervescent options over still water. Meanwhile, private-label brands are gaining traction by offering cost-effective alternatives without compromising quality. Innovation and premiumization also characterize the market, with brands introducing flavored waters, functional beverages, and limited-edition products to capture the attention of discerning customers. These trends highlight the dynamic evolution of the German bottled water market.
Market Trends
Health and Wellness Emphasis Coupled with Sustainability
The German bottled water market thrives on growing consumer focus on health and wellness, paired with heightened environmental consciousness. Functional waters enriched with vitamins, minerals, and other health-boosting additives are gaining traction among health-conscious individuals. Additionally, the importance of hydration for overall well-being has been widely recognized, leading to increased consumption of bottled water as a dependable source of pure hydration. Complementing this trend is the shift toward sustainability, with eco-friendly packaging such as aluminum, glass, and recyclable plastics becoming a priority. Consumers increasingly demand products that align with their environmental values, encouraging brands to explore reduced plastic usage through lightweight bottles and refillable solutions. This dual emphasis on health and eco-responsibility underscores the evolving consumer preferences shaping the market.
Innovation, Premiumization, and E-commerce Growth
Innovation and premiumization continue to define the German bottled water market, catering to a discerning consumer base. High-end brands offering unique taste profiles, luxurious packaging, and mineral-enriched sparkling water are becoming increasingly popular among affluent buyers. For instance, the premium bottled water market in Germany is expected to grow significantly due to increasing consumer demand for unique and high-quality products. Moreover, innovative products, such as flavored waters and limited-edition releases, reflect the industry's effort to capture diverse consumer preferences. Private-label offerings also play a significant role, providing cost-effective alternatives that do not compromise quality, thereby appealing to budget-conscious consumers. Simultaneously, e-commerce platforms are transforming bottled water sales by expanding the accessibility of premium and niche products. Online channels enable consumers to explore diverse options with ease, adding a layer of convenience to the purchasing process. These trends, alongside Germany's stringent regulatory framework ensuring product safety and transparency through clear labeling, further reinforce consumer trust and drive market expansion.
Market Challenges Analysis
Environmental Sustainability Challenges
The bottled water industry faces growing challenges related to environmental sustainability, as it remains under scrutiny for its contribution to plastic pollution. The production, transportation, and disposal of plastic bottles leave a substantial carbon footprint, prompting criticism from environmental groups and consumers alike. Rising consumer awareness about sustainability further intensifies this challenge, with increasing demands for eco-friendly packaging solutions like biodegradable, recyclable, or reusable materials. For instance, a report by the German Environmental Agency highlights that 80% of consumers prefer products with eco-friendly packaging. Addressing these concerns requires significant investment in research and development for sustainable alternatives, which can strain resources, particularly for smaller brands. Companies must also navigate the logistical complexities of reducing their environmental impact while maintaining product quality and availability. This environmental imperative is reshaping industry practices and adding pressure to adopt sustainable business models.
Competitive and Economic Pressures
The highly competitive nature of the bottled water market presents another set of challenges, with private-label brands gaining prominence by offering cost-effective alternatives. This rise intensifies competition, compelling established brands to differentiate through innovation and premium offerings. Moreover, economic factors such as inflation and rising raw material costs contribute to production and operational pressures. During economic downturns, consumers often shift toward more affordable options or reduce discretionary spending, affecting the demand for premium bottled water products. Additionally, the industry must contend with evolving regulatory landscapes, which can impose financial and operational burdens. Compliance with stringent quality standards and adapting to changing regulations can increase production costs and require ongoing investments. Compounding these issues, shifting consumer behavior, such as growing preferences for tap water or reusable bottles, adds complexity to maintaining market relevance. To succeed, companies must stay agile, continuously innovate, and align with both regulatory requirements and consumer expectations.
Market Opportunities
Expanding Demand for Premium and Functional Waters
The Germany bottled water market presents significant opportunities in the premium and functional water segments. As health and wellness trends continue to dominate consumer preferences, there is a growing demand for bottled water enriched with added benefits such as vitamins, minerals, and electrolytes. This creates opportunities for brands to differentiate their offerings by catering to specific health needs, such as hydration during physical activities or immune support. Similarly, the increasing popularity of premium bottled water, characterized by unique taste profiles, mineral content, and luxury packaging, provides a lucrative avenue for businesses targeting affluent consumers. By leveraging innovation and marketing strategies that highlight product quality and health benefits, companies can capture a larger share of these high-value market segments.
Sustainability and E-commerce Growth
The growing consumer focus on sustainability offers another promising opportunity. With environmental concerns driving demand for eco-friendly packaging, brands investing in biodegradable materials, recycled plastics, or reusable solutions can gain a competitive edge. Furthermore, local sourcing of water, reducing transportation emissions, and promoting sustainability narratives resonate well with environmentally conscious consumers. Parallelly, the rapid growth of e-commerce platforms has expanded the accessibility of bottled water products. Online sales channels enable brands to reach a broader audience, particularly for premium and niche products. By optimizing their digital presence and ensuring seamless delivery experiences, companies can tap into the convenience-driven preferences of modern consumers, further driving growth in the Germany bottled water market.
Market Segmentation Analysis:
By Water Source:
The Germany bottled water market is segmented by water source into natural mineral water, purified water, spring water, artesian water, sparkling water, and alkaline water. Natural mineral water dominates this segment, driven by its perceived health benefits and rich mineral content. Sparkling water is a strong contender, widely favored in Germany due to its effervescent quality, which appeals to consumers seeking a refreshing alternative to still water. Purified water, known for its high filtration standards, is gaining popularity among urban consumers prioritizing quality and safety. Spring water and artesian water appeal to eco-conscious and health-focused consumers, with their natural origins enhancing their marketability. The growing preference for alkaline water, recognized for its potential pH-balancing benefits, further enriches the segment, highlighting diverse consumer preferences in this dynamic market.
By Packaging Water Source:
By packaging type, the market is categorized into PET bottles, glass bottles, cartons and pouches, and cans. PET bottles lead the segment, valued for their lightweight, affordability, and convenience, making them the preferred choice for on-the-go consumption. Glass bottles, associated with premium and environmentally conscious products, are gaining traction among discerning consumers. Cartons and pouches represent an eco-friendly trend, appealing to those seeking sustainable alternatives to plastic. The use of cans, primarily for sparkling water and innovative beverages, is growing as brands experiment with packaging formats to enhance product differentiation. This diverse range of packaging options underscores the market's ability to cater to varied consumer needs, balancing convenience with sustainability.
Segments:
Based on Water Source:
- Natural Mineral Water
- Purified Water
- Spring Water
- Artesian Water
- Sparkling Water
- Alkaline Water
Based on Packaging Water Source:
- PET (Polyethylene Terephthalate) Bottles
- Glass Bottles
- Cartons and Pouches
- Cans
Based on End-user:
- Households
- Foodservice and Hospitality
- Offices and Corporate
- Healthcare Facilities
- Outdoor and On-the-Go
- Institutional Buyers
Based on Product Varieties:
- Still Water
- Carbonated Water
- Flavored Water
- Functional Water
- Vitamin-Enhanced Water
- Premium Water
Based on Pack Sizes:
- Individual-Serve Bottles
- Multi-Serve Bottles
- Bulk Packaging
Based on Distribution Channel:
- Supermarkets and Hypermarkets
- Convenience Stores
- Online Retail
- Vending Machines
- Wholesalers and Distributors
Based on the Geography:
- Berlin
- Munich
- Hamburg
Regional Analysis
Berlin
Berlin holds a significant share of the Germany bottled water market, accounting for approximately 20% of the total market value. The city’s status as the nation’s capital and a major urban hub drives demand for bottled water, fueled by its dense population, diverse demographics, and bustling lifestyle. Berliners are known for their preference for premium and sustainable products, contributing to the growing popularity of natural mineral water and sparkling water. The city also witnesses high consumption of functional and flavored bottled water, aligning with the health-conscious trends prominent among urban dwellers. Berlin’s well-established retail and e-commerce networks further facilitate the availability of bottled water across the city, ensuring widespread access to diverse product options. Moreover, the city's focus on sustainability has spurred demand for eco-friendly packaging solutions, such as glass bottles and recyclable PET, as brands actively cater to the environmentally aware consumer base.
Munich
Munich captures around 15% of the Germany bottled water market, emerging as a key region for premium bottled water products. Renowned for its affluent population and strong purchasing power, the city showcases a robust demand for high-quality and luxury water brands. Sparkling water is particularly popular in Munich, aligning with regional preferences for effervescent beverages. The city’s vibrant hospitality industry, including upscale restaurants and hotels, further boosts demand for bottled water, particularly premium and glass-packaged variants. Additionally, Munich's residents exhibit a growing interest in functional and alkaline water products, reflecting their focus on health and wellness. Retail outlets, including specialty stores and supermarkets, play a crucial role in driving sales, while online platforms contribute to the accessibility of niche and premium offerings. Sustainability initiatives in Munich also shape consumer preferences, encouraging the adoption of reusable and biodegradable packaging, making it a significant market for innovative and eco-friendly bottled water solutions.
Key Player Analysis
- Nestlé
- Danone SA
- Ferrarelle SpA
- RheinfelsQuellen H. Hovelmann GmbH & Co. KG
- Gerolsteiner Brunnen GmbH & Co. KG
- Fonti di Vinadio SpA
- Sanpellegrino Group
- Highland Spring Limited
Competitive Analysis
The competitive landscape of the Germany bottled water market is defined by the presence of leading players such as Nestlé, Danone SA, Gerolsteiner Brunnen GmbH & Co. KG, RheinfelsQuellen H. Hovelmann GmbH & Co. KG, and Sanpellegrino Group. These companies drive the market through extensive product portfolios, strong branding, and innovative strategies. Leading players focus on catering to diverse consumer preferences by offering natural mineral water, sparkling water, and functional varieties enriched with vitamins and minerals. Sustainability remains a critical area of competition, with major brands investing in eco-friendly packaging solutions like recycled PET, glass bottles, and refillable containers to align with consumer demand for environmentally responsible products. Premiumization and product differentiation are also prominent strategies, with brands introducing luxury bottled water and innovative flavors to target high-income and health-conscious consumers. Distribution networks, encompassing retail chains and e-commerce platforms, enable broad market reach and accessibility. Furthermore, compliance with Germany’s strict quality regulations enhances consumer trust and ensures consistent product standards. As competition intensifies, market leaders continue to invest in research and development to address environmental concerns, improve operational efficiencies, and introduce innovative solutions, strengthening their foothold in the dynamic bottled water industry.
Recent Developments
- In July 2024, Source, a company based in Scottsdale, Arizona, unveiled a groundbreaking method to tackle the water crisis by generating canned water using air and sunlight. This initiative is part of the increasing trend toward sustainable technologies that aim to resolve environmental challenges while ensuring access to vital resources. The product will be branded as Sky Wtr and is designed to offer an off-grid solution for producing drinking water. Source intends to launch this water for public sale across the U.S. in major retail outlets around August or September 2024. The canned drinking water will be packaged in recyclable aluminum cans and bottles.
- In February 2024, Gatorade announced the launch of its first unflavored water product, Gatorade Water in the U.S., marking a significant expansion into the bottled water category. This move is part of Gatorade’s strategy to diversify its offerings beyond traditional sports drinks and tap into the growing market for functional beverages. Gatorade Water is available nationwide across various retail platforms as well as on Amazon, and Gatorade.com.
- In April 2023, Nestlé partnered with Acreto, a company focused on sustainable packaging, to launch a new line of bottled water made from 100% plant-based materials.
- In February 2023, PepsiCo partnered with biotech company LanzaTech to develop a new process for producing bottled water from captured carbon emissions.
- In January 2023, Icelandic Glacial signed an exclusive deal as the official in-flight water partner with Icelandair, Iceland’s national airline
Market Concentration & Characteristics
The Germany bottled water market is characterized by moderate to high market concentration, with a few leading players holding a significant share while numerous regional and niche brands cater to localized consumer demands. Dominant players such as Nestlé, Danone SA, and Gerolsteiner Brunnen GmbH & Co. KG leverage their extensive product portfolios, strong distribution networks, and brand reputation to maintain competitive advantages. The market showcases a blend of premium offerings, such as sparkling and mineral waters, and cost-effective options, including purified and private-label brands.
A distinctive characteristic of the market is its alignment with evolving consumer trends, including health consciousness, sustainability, and premiumization. Brands focus on innovative product development, such as functional and flavored waters, to cater to health-focused and diverse consumer preferences. The market is also shaped by strict regulatory frameworks ensuring quality and safety, fostering consumer trust in bottled water products. Furthermore, sustainability initiatives, such as eco-friendly packaging and local sourcing, play a pivotal role in defining competitive strategies. While urban centers drive premium product demand, rural regions offer opportunities for growth through affordability and accessibility. The dynamic interplay between leading and regional players underscores the market’s adaptability to shifting consumer preferences and environmental priorities.
Report Coverage
The research report offers an in-depth analysis based on Water Source, Packaging Water Source, End-User, Product Varieties, Pack Sizes, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Germany bottled water market is expected to witness steady growth driven by increasing consumer demand for health-oriented beverages.
- Sparkling water will continue to dominate preferences, supported by its popularity as a refreshing alternative to still water.
- Functional and flavored waters are projected to gain traction as health-conscious consumers seek added benefits from their beverages.
- Sustainability will remain a critical focus, with brands emphasizing eco-friendly packaging and reduced plastic usage.
- Technological advancements in production and packaging are likely to improve efficiency and minimize environmental impacts.
- Premiumization trends will persist, with high-end brands offering unique taste profiles and innovative product features.
- E-commerce platforms will expand their role, providing greater access to niche and premium bottled water products.
- Stringent regulations will continue to shape market dynamics, ensuring product safety and fostering consumer trust.
- Private-label brands are expected to grow, offering cost-effective alternatives and increasing competition in the market.
- Urbanization and changing lifestyles will fuel demand for portable and convenient bottled water options across Germany.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Germany Bottled Water Market?
What factors are driving the growth of the Germany Bottled Water Market?
What are the key segments within the Germany Bottled Water Market?
What are some challenges faced by the Germany Bottled Water Market?
Who are the major players in the Germany Bottled Water Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Germany Bottled Water Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Germany Bottled Water Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 19,820.10 million → 2032: USD 37,443.72 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Germany Bottled Water Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Germany Bottled Water Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Germany Bottled Water Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Germany Bottled Water Market Drivers
- 3.3 Germany Bottled Water Market Restraints & Challenges
- 3.4 Germany Bottled Water Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Germany Bottled Water Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Germany Bottled Water Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Germany Bottled Water category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Germany Bottled Water Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Germany Bottled Water Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Germany Bottled Water market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Germany Bottled Water Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Germany Bottled Water Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Germany Bottled Water Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Germany Bottled Water (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Germany Bottled Water Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Germany Bottled Water Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Germany Bottled Water Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Germany Bottled Water Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Germany Bottled Water Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Germany Bottled Water Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Germany Bottled Water Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Germany Bottled Water Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Germany Bottled Water Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
