
Market Overview
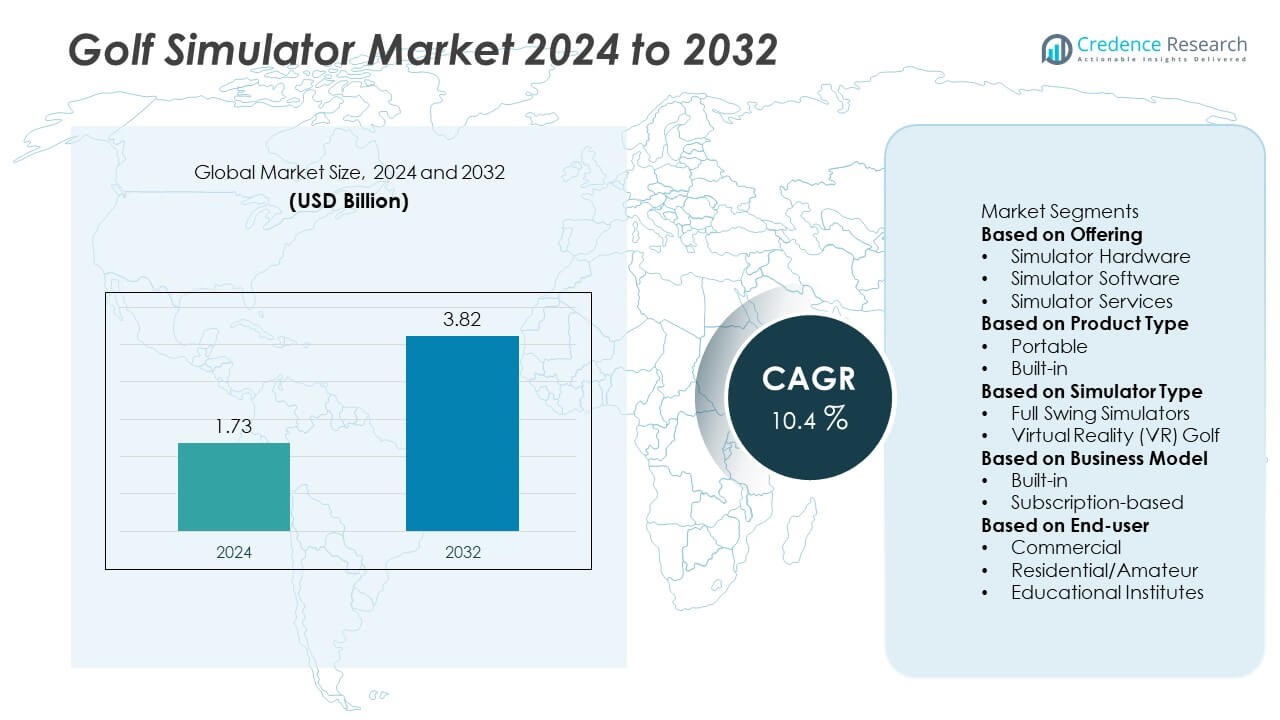
The Golf Simulator market was valued at USD 1.73 billion in 2024 and is projected to reach USD 3.82 billion by 2032, growing at a CAGR of 10.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Golf Simulator market Size 2024 | USD 1.73 Billion |
| Golf Simulator market, CAGR | 10.4% |
| Golf Simulator market Size 2032 | USD 3.82 Billion |
The Golf Simulator market is led by major players such as Full Swing Golf, TruGolf, Inc., GOLFZON Co., Ltd., TrackMan A/S, aboutGOLF Limited, Foresight Sports, SkyTrak LLC, HD Golf, Uneekor Inc., and OptiShot Golf. These companies focus on delivering advanced, data-driven, and immersive golfing experiences through AI-powered analytics, motion tracking, and 3D visualization technologies. North America led the global market with a 41% share in 2024, supported by a strong golfing culture, advanced infrastructure, and high consumer spending on sports technology. Europe followed with 28%, driven by indoor golfing growth, while Asia Pacific held 22%, fueled by rapid urbanization and increasing golf participation.
Market Insights
- The Golf Simulator market was valued at USD 1.73 billion in 2024 and is projected to reach USD 3.82 billion by 2032, growing at a CAGR of 10.4%.
- Rising demand for indoor sports and virtual golf experiences is driving adoption across commercial, residential, and recreational sectors.
- The hardware segment dominated with a 63% share in 2024, supported by advancements in sensors, radar tracking, and 3D graphics technologies.
- Leading players such as GOLFZON, Full Swing Golf, TrackMan, and Foresight Sports are investing in AI-based analytics and cloud-integrated simulation systems to enhance realism and data accuracy.
- North America led with 41% share, followed by Europe at 28% and Asia Pacific at 22%, driven by a strong golfing culture, advanced technology infrastructure, and expanding indoor entertainment facilities.
Market Segmentation Analysis:
By Offering
The simulator hardware segment dominated the Golf Simulator market in 2024 with a 63% share. Hardware components such as launch monitors, sensors, and projectors are essential for delivering realistic ball flight accuracy and immersive experiences. Increasing demand for high-precision systems among commercial facilities and professional golfers is driving hardware sales. The integration of high-speed cameras and radar-based tracking technologies has further enhanced performance analytics. Meanwhile, simulator software is growing steadily as advancements in 3D graphics, AI-enabled gameplay, and online multiplayer features improve user engagement and training capabilities.
- For instance, TrackMan introduced its TrackMan 4 dual-radar system, capable of capturing over 40 ball and club data parameters at a sampling rate of 40,000 times per second.
By Product Type
The built-in segment held a leading 58% share of the Golf Simulator market in 2024. Built-in simulators are favored in commercial settings such as golf academies, entertainment centers, and sports clubs due to their advanced configuration, durability, and superior performance. They provide an immersive experience with high-quality graphics and customized course simulations. Portable simulators, however, are gaining popularity among individual golfers and home users for their affordability, compact design, and ease of installation. The increasing adoption of portable setups by amateur players continues to broaden market reach across residential applications.
- For instance, GOLFZON's Vision Premium T1 simulator features two high-speed ceiling-mounted cameras, an automatic tee-up system, and over 275 virtual golf courses. The unit also includes a dynamic moving swing plate and a multi-surface hitting mat that simulate real-course slope and lie conditions, providing a professional-grade indoor playing experience.
By Simulator Type
Full swing simulators accounted for the dominant 67% share of the Golf Simulator market in 2024. These systems provide comprehensive swing analysis, ball tracking, and course visualization, making them the preferred choice for professional training and commercial use. The demand is driven by the ability to replicate real-world playing conditions and improve performance through detailed data feedback. Virtual reality (VR) golf simulators are emerging rapidly, attracting younger consumers and gaming enthusiasts seeking interactive and immersive experiences. Continuous technological improvements in VR hardware and realistic graphics are expected to accelerate their adoption in the coming years.
Key Growth Drivers
Rising Popularity of Indoor Golfing and Virtual Experiences
The growing popularity of indoor sports and virtual gaming is driving demand for golf simulators globally. Urban consumers are increasingly adopting home-based entertainment and training systems, allowing year-round play regardless of weather conditions. Commercial facilities such as sports clubs, hotels, and entertainment centers are also investing in advanced simulators to attract golfers and leisure users. The increasing accessibility of affordable simulator setups and enhanced realism in gameplay is further encouraging adoption among amateurs and professionals seeking convenient practice solutions.
- For instance, Foresight Sports offers advanced golf simulators featuring quadrascopic camera technology that captures thousands of frames per second, such as the GCQuad. The system measures ball speed, launch angle, and spin axis with high accuracy. Through an optional add-on, it can also measure clubhead movement.
Technological Advancements in Simulation and Tracking Systems
Continuous innovation in launch monitors, sensors, and tracking software has significantly improved simulator accuracy and performance. High-speed cameras, radar-based motion sensors, and AI-powered analytics provide detailed insights into swing dynamics and ball flight. These advancements replicate real-course conditions, enhancing the training value for golfers. Integration of cloud connectivity and mobile apps enables data storage and performance monitoring. Such technology-driven upgrades are expanding simulator adoption across golf academies, sports retailers, and professional training environments.
- For instance, Uneekor developed the EYE XO2 simulator featuring three high-speed infrared cameras that capture club and ball data at over 3,000 frames per second. The system measures 24 key swing metrics and integrates with the View software platform, offering optional add-ons like AI-driven swing analysis via the AI Trainer module and cloud-synced progress tracking for professional coaching setups.
Increasing Adoption Across Commercial and Residential Segments
The Golf Simulator market is witnessing growing adoption in both commercial and residential settings. In commercial spaces, simulators are used for professional training, corporate entertainment, and golf lounges. Residential demand is rising among golf enthusiasts seeking home-based practice solutions. Compact, portable simulators with realistic 3D courses appeal to amateur players. This dual-market expansion, supported by product versatility and growing consumer spending on sports technology, is fueling overall market growth while broadening the customer base across regions.
Key Trends and Opportunities
Integration of AI, AR, and Data Analytics
The integration of artificial intelligence and augmented reality is transforming the Golf Simulator market. AI-driven analytics provide detailed feedback on swing patterns, ball speed, and trajectory, helping players refine performance. Augmented reality enhances visualization and immersion, offering realistic course simulations. Data analytics platforms enable personalized training programs and virtual competitions. This trend supports user engagement while opening opportunities for software developers to deliver more interactive and intelligent simulator systems for both personal and professional use.
- For instance, Full Swing Golf launched its AI-based performance software integrated with the KIT launch monitor. The system uses AI to process 16 points of data per swing, tracking metrics such as club path, face angle, and smash factor.
Expansion of Subscription-Based and Cloud-Connected Models
Subscription-based simulator models are gaining popularity as they offer flexible access to courses, software updates, and multiplayer modes. Cloud-connected simulators enable players to compete globally and track performance across sessions. Manufacturers are leveraging this model to build recurring revenue streams while providing continuous feature upgrades. This shift toward software-as-a-service (SaaS) in the sports technology domain supports wider adoption, particularly among residential users seeking affordable yet advanced virtual golfing experiences.
- For instance, SkyTrak introduced its SkyTrak+ Membership Platform, which offers access to a large library of courses, the ability to sync performance data across devices, online tournaments via PinSeeker, software updates, and multiplayer features through annual subscription plans.
Key Challenges
High Initial Cost and Space Requirements
High installation and maintenance costs remain major barriers to widespread adoption of golf simulators. Built-in systems, especially those with advanced tracking and display technologies, require significant investment and dedicated space. These factors limit accessibility for individual consumers and small facilities. Manufacturers are addressing this challenge by introducing compact, portable systems and modular designs that reduce cost without compromising performance. However, price sensitivity continues to affect market penetration, especially in emerging regions.
Limited Realism Compared to On-Course Experience
Despite technological advancements, golf simulators still face challenges in replicating the exact feel of outdoor gameplay. Factors such as environmental variation, natural turf interaction, and real-weather dynamics are difficult to reproduce digitally. This limits their appeal among professional players who prefer real-course practice. Developers are working to bridge this gap through enhanced graphics, motion feedback systems, and multisensory experiences. Continued improvements in simulation fidelity will be essential to strengthen user satisfaction and boost long-term market adoption.
Regional Analysis
North America North America dominated the Golf Simulator market in 2024 with a 41% share. The region’s strong golfing culture, high disposable income, and widespread adoption of indoor sports technologies drive growth. The United States leads the market, supported by the presence of advanced simulator manufacturers and a large base of golf enthusiasts. Commercial facilities, golf academies, and home users increasingly prefer high-performance simulators for entertainment and professional training. Canada also contributes to regional growth through rising installation in sports clubs and recreational centers, supported by year-round indoor golfing demand due to cold weather conditions.
Europe
Europe accounted for a 28% share of the Golf Simulator market in 2024. The region’s growth is driven by increasing participation in golf and growing investment in indoor sports infrastructure. The United Kingdom, Germany, and France lead adoption due to high interest in golf training technologies and rising demand for entertainment-based simulator lounges. European players favor simulator systems that combine realistic visuals with precision analytics. Technological collaborations between software developers and hardware providers continue to enhance product innovation, while expanding hospitality-based installations further strengthens the regional market outlook.
Asia Pacific
Asia Pacific held a 22% market share in 2024 and is emerging as the fastest-growing region in the Golf Simulator market. Countries such as Japan, South Korea, and China are driving adoption through expanding indoor golf entertainment and training facilities. The growing popularity of golf among urban professionals and rising disposable incomes are key drivers. Technological advancements, coupled with the entry of global brands, are making simulators more accessible to residential and commercial users. Government initiatives promoting sports and recreation are also supporting industry growth, particularly in developing economies such as India and Southeast Asia.
Latin America
Latin America captured a 5% share of the Golf Simulator market in 2024. The region is witnessing steady adoption driven by the growing popularity of golf in Brazil, Mexico, and Argentina. The expansion of sports entertainment venues and the increasing number of golf academies are supporting market growth. Rising tourism and hospitality investments are encouraging the installation of simulators in resorts and recreational centers. However, limited awareness and high costs continue to restrain adoption. As consumer interest in premium sports experiences grows, manufacturers are targeting the region with cost-effective and portable simulator models.
Middle East and Africa
The Middle East and Africa accounted for a 4% share of the Golf Simulator market in 2024. Rising disposable income and expanding luxury entertainment infrastructure are driving simulator installations across countries such as the UAE, Saudi Arabia, and South Africa. The region’s climate, which restricts outdoor sports for much of the year, further supports demand for indoor golfing systems. Commercial establishments, including hotels and sports clubs, are increasingly integrating simulators to attract premium customers. Continuous investment in leisure and sports technology is expected to strengthen market growth over the coming years.
Market Segmentations:
By Offering
- Simulator Hardware
- Simulator Software
- Simulator Services
By Product Type
- Portable
- Built-in
By Simulator Type
- Full Swing Simulators
- Virtual Reality (VR) Golf
By Business Model
- Built-in
- Subscription-based
By End-user
- Commercial
- Residential/Amateur
- Educational Institutes
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Golf Simulator market includes key players such as Full Swing Golf, TruGolf, Inc., GOLFZON Co., Ltd., TrackMan A/S, aboutGOLF Limited, Foresight Sports, SkyTrak LLC, HD Golf, Uneekor Inc., and OptiShot Golf. These companies compete through innovation in simulation technology, advanced tracking systems, and immersive virtual experiences. Leading players like GOLFZON, TrackMan, and Full Swing Golf focus on high-end simulators that combine precision data analytics with realistic graphics for professional and commercial use. TruGolf and OptiShot target home and amateur users with affordable, portable systems. Continuous advancements in sensors, cameras, and AI-based swing analysis are reshaping user experience. Market players are also expanding their global presence through partnerships with golf academies, sports facilities, and entertainment centers. Strategic emphasis on subscription-based models, software integration, and cloud connectivity is further strengthening competitiveness in the evolving golf simulator industry.
Key Player Analysis
- Full Swing Golf
- TruGolf, Inc.
- GOLFZON Co., Ltd.
- TrackMan A/S
- aboutGOLF Limited
- Foresight Sports
- SkyTrak LLC
- HD Golf
- Uneekor Inc.
- OptiShot Golf
Recent Developments
- In August 2025, TrackMan became the Official Launch Monitor and Ball Tracing Technology partner of the DP World Tour, integrating its tracing visuals into live broadcasts.
- In May 2025, IdeasLab launched XView AI, a markerless app that provides real-time, offline analysis of the full golf swing by tracking body, shaft, and club movement.
- In February 2025, Full Swing integrated Canopy remote-device management to update firmware and troubleshoot simulator systems at scale.
- In October 2023, TruGolf announced a partnership with GOLFZON for the Wave simulator, which tracks 34 ball and club data points and supports E6 CONNECT compatibility.
Report Coverage
The research report offers an in-depth analysis based on Offering, Product Type, Simulator Type, Business Model, End-user and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The golf simulator market will expand with rising interest in indoor sports and virtual training.
- Advancements in AI and 3D imaging will enhance simulation accuracy and user experience.
- Portable and home-use simulators will gain popularity among amateur golfers.
- Commercial adoption will grow in entertainment venues, clubs, and golf academies.
- Cloud connectivity and subscription-based models will boost recurring revenues.
- Integration with VR and AR will make simulations more immersive and interactive.
- Asia Pacific will emerge as the fastest-growing market due to rising golf participation.
- Manufacturers will focus on compact, affordable, and easy-to-install systems.
- Collaborations between tech companies and sports brands will strengthen product innovation.
- Data analytics and performance tracking features will drive the next phase of market growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth of Indoor Golfing and Virtual Experiences
Urbanization and changing lifestyles are increasing the appeal of indoor sports, with golf simulators enabling year-round play regardless of weather. This trend is driving adoption in both commercial venues and residential settings, expanding the market's reach.
Technological Advancements in Simulation and Tracking
Continuous improvements in high-speed cameras, radar sensors, and AI-powered analytics are enhancing the realism and accuracy of golf simulators. These innovations provide detailed swing and ball flight data, making simulators more valuable for both training and entertainment.
Expansion of Commercial and Residential Applications
Golf simulators are being adopted in a wider range of settings, from professional golf academies and entertainment centers to private homes. The versatility and availability of both high-end built-in and affordable portable systems are fueling market growth across diverse user segments.
Integration of AI, AR, and Cloud Connectivity
The adoption of artificial intelligence, augmented reality, and cloud-based platforms is transforming user experience by enabling personalized training, immersive course simulations, and global multiplayer competitions. These features are increasing user engagement and supporting recurring revenue models.
Rising Popularity of Subscription-Based Models
Subscription and cloud-connected models are making advanced simulator features more accessible and affordable, especially for home users. This shift is driving recurring revenues for manufacturers and encouraging broader adoption among amateur golfers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Golf Simulator market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Golf Simulator market projected to grow between 2025 and 2032?
Which Golf Simulator market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Golf Simulator market?
Who are the leading companies in the Golf Simulator market?
Which region commanded the largest share of the Golf Simulator market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-user
- 1.2.1 Commercial
- 1.2.2 Residential/Amateur
- 1.2.3 Educational Institutes
- 1.3 By Offering
- 1.3.1 Simulator Hardware
- 1.3.2 Simulator Software
- 1.3.3 Simulator Services
- 1.4 By Product Type
- 1.4.1 Portable
- 1.4.2 Built-in
- 1.5 By Simulator Type
- 1.5.1 Full Swing Simulators
- 1.5.2 Virtual Reality (VR) Golf
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1.73 billion → 2032: USD 3.82 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Golf Simulators Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Golf Simulators Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Golf Simulators Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Golf Simulators Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Golf Simulators Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Golf Simulators Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Golf Simulators Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Golf Simulators Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1.73 billion → 2032: USD 3.82 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Golf Simulators Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-user - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Commercial
- 12.3.7.2 Residential/Amateur
- 12.3.7.3 Educational Institutes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Offering - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Simulator Hardware
- 12.4.7.2 Simulator Software
- 12.4.7.3 Simulator Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Portable
- 12.5.7.2 Built-in
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Simulator Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Full Swing Simulators
- 12.6.7.2 Virtual Reality (VR) Golf
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Golf Simulators End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Golf Simulators Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Golf Simulators Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Golf Simulators Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Full Swing Golf
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 TruGolf, Inc.
- 18.4 GOLFZON Co., Ltd.
- 18.5 TrackMan A/S
- 18.6 aboutGOLF Limited
- 18.7 Foresight Sports
- 18.8 SkyTrak LLC
- 18.9 HD Golf
- 18.10 Uneekor Inc.
- 18.11 OptiShot Golf
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

