
Market Overview
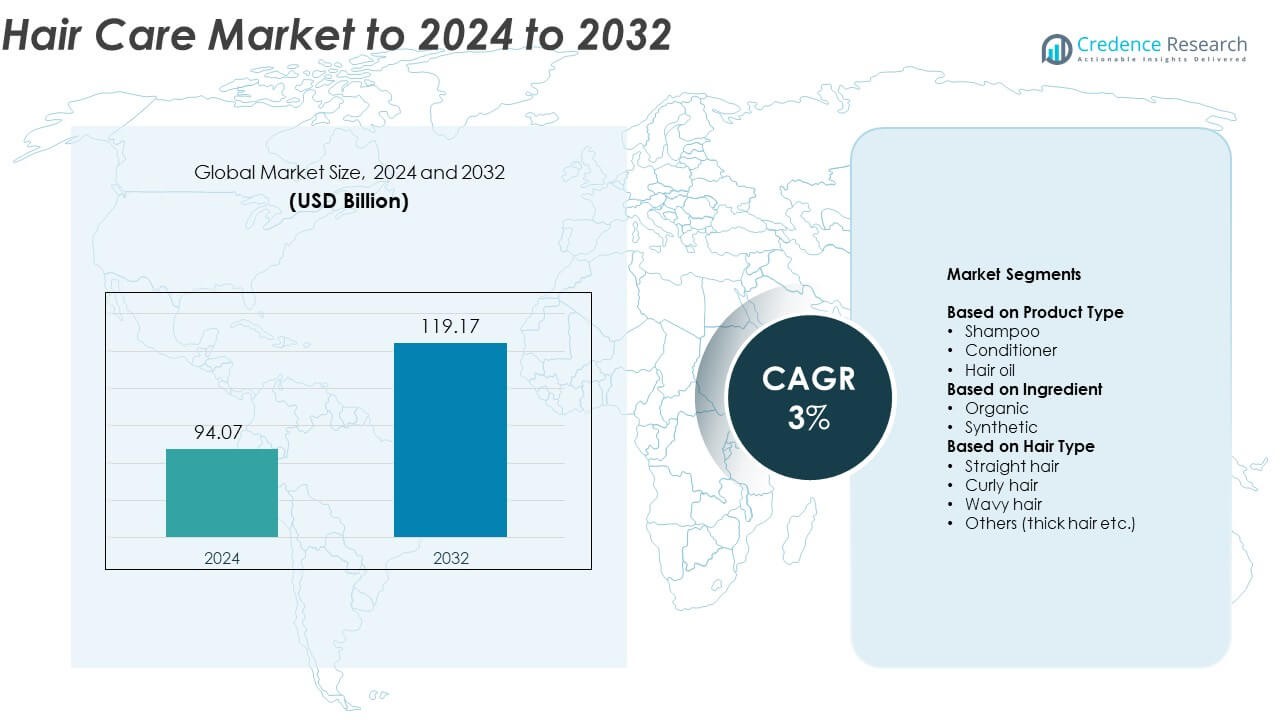
The hair care market size was valued at USD 94.07 Billion in 2024 and is anticipated to reach USD 119.17 Billion by 2032, at a CAGR of 3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hair Care Market Size 2024 | USD 94.07 Billion |
| Hair Care Market, CAGR | 3% |
| Hair Care Market Size 2032 | USD 119.17 Billion |
Leading players such as L’Oréal, Unilever, Procter & Gamble, Estée Lauder, and Shiseido dominate the global hair care market through innovation and brand diversity. These companies maintain strong distribution networks and invest heavily in R&D to address rising consumer demand for personalized, sustainable, and scalp-focused products. North America leads the global market with about 34% share, supported by high spending on premium and organic formulations. Europe follows with nearly 28% share, driven by sustainability-focused consumers, while Asia Pacific, holding around 24%, emerges as the fastest-growing region due to urbanization and expanding middle-class income levels.
Market Insights
- The hair care market was valued at USD 94.07 Billion in 2024 and is projected to reach USD 119.17 Billion by 2032, growing at a CAGR of 3%.
- Rising awareness of scalp health, increasing demand for personalized solutions, and expansion of premium and organic product lines are driving market growth.
- Sustainable and clean-beauty trends continue to shape innovation, with brands focusing on biodegradable ingredients and eco-friendly packaging to attract conscious consumers.
- The market remains highly competitive with global leaders investing in R&D, digital marketing, and sustainable sourcing to strengthen brand positioning amid growing local competition.
- North America leads with 34% share, followed by Europe with 28%, while Asia Pacific, holding 24%, records the fastest growth. Among product types, the shampoo segment dominates with 41% share, supported by high frequency of use and product innovation across both mass and premium categories.
Market Segmentation Analysis:
By Product Type
The shampoo segment dominates the hair care market with nearly 41% share in 2024. Its leadership is driven by high product penetration, frequent usage, and a wide variety of formulations catering to scalp health, dandruff control, and hair strengthening. Consumers increasingly prefer sulfate-free, anti-hair fall, and moisturizing shampoos, reflecting a shift toward wellness-focused routines. Expanding product portfolios from major brands and the rise of personalized cleansing solutions further boost this segment’s growth across both mass-market and premium categories.
- For instance, Head & Shoulders launched BARE, a 9-ingredient anti-dandruff shampoo in May 2023.
By Ingredient
The synthetic ingredient segment leads the market, accounting for about 56% share in 2024. Synthetic formulations remain popular due to their cost-effectiveness, stability, and performance consistency in shampoos, conditioners, and hair oils. However, the demand for organic alternatives is growing rapidly as consumers become more ingredient-conscious and seek chemical-free, sustainable options. Increasing awareness about scalp sensitivity and eco-friendly packaging is encouraging manufacturers to blend natural actives with synthetic bases, enhancing product safety and appeal across global markets.
- For instance, Croda supplies more than 200 innovative cosmetic active ingredients for the cosmetics and personal care industry, which addresses various concerns for both skin and hair.
By Hair Type
The straight hair segment holds the largest share at approximately 38% in 2024. This dominance is attributed to a high global prevalence of straight hair and the availability of specialized products addressing smoothness, shine, and frizz control. Manufacturers focus on lightweight formulations and UV protection to meet the styling needs of straight hair users. Meanwhile, products designed for curly and wavy hair types are gaining traction as inclusivity and texture-specific care trends rise, driving broader product diversification within the market.
Key Growth Drivers
Rising Demand for Premium and Personalized Products Consumers are shifting toward premium hair care solutions tailored to their individual needs. Brands are offering customized formulations based on scalp type, hair texture, and lifestyle. The growing adoption of advanced diagnostic tools and AI-driven product recommendations enhances personalization. Premium ranges with targeted benefits such as anti-hair fall, color protection, and scalp nourishment are driving strong sales, especially across urban markets. This trend reflects a broader move toward luxury and wellness-driven grooming habits.
- For instance, Function of Beauty’s algorithm supports up to 12 billion custom shampoo/conditioner combinations.
Growing Awareness of Hair and Scalp Health
Increasing consumer awareness about scalp care as part of overall wellness is boosting market growth. The focus has expanded beyond styling toward maintaining healthy hair through balanced pH levels and hydration. Rising incidences of hair thinning, dandruff, and pollution-related damage are encouraging frequent use of restorative products. Brands are investing in dermatologically tested and clinically backed formulations, aligning with the rising preference for scientifically proven efficacy.
- For instance, Selsun Blue shampoos list 1% selenium sulfide as the active anti-dandruff ingredient on FDA DailyMed.
Expansion of E-commerce and Digital Engagement
Online platforms are transforming the distribution landscape by providing convenience, wider choices, and instant access to global brands. E-commerce penetration in personal care categories has accelerated post-pandemic. Digital marketing and influencer campaigns enhance visibility and brand trust, particularly among younger consumers. Subscription models, personalized quizzes, and virtual consultations further strengthen customer engagement, making online channels a critical growth driver for the hair care industry.
Key Trends and Opportunities
Shift Toward Sustainable and Clean Beauty Formulations
Sustainability is reshaping product innovation, with brands adopting biodegradable ingredients and eco-friendly packaging. Consumers increasingly favor clean-label products free from sulfates, parabens, and silicones. The demand for cruelty-free and vegan hair care lines is also accelerating. Companies are investing in circular economy practices and transparency in ingredient sourcing, which positions sustainability as both a competitive advantage and a long-term growth opportunity.
- For instance, Unilever targets a 30% virgin-plastic reduction by 2026 and 40% by 2028, against a 2019 baseline. The company reached 21% recycled plastic use across its portfolio as of its latest 2024 reporting period (covering the year 2023). Unilever's separate target is to achieve 25% recycled plastic use by 2025.
Integration of Technology in Product Development
AI and biotechnology are transforming hair care innovation, enabling the creation of precise, data-driven formulations. Advanced diagnostic tools analyze scalp conditions, offering tailored product recommendations. Smart hair devices and apps now support real-time care tracking and progress monitoring. These innovations elevate user experience and brand differentiation, presenting strong opportunities for tech-enabled personalization in premium product categories.
- For instance, Perfect Corp’s YouCam apps have surpassed 1 billion downloads, and its AI Hair Type Analysis identifies texture and curl patterns in seconds.
Key Challenges
Rising Raw Material Costs and Supply Chain Volatility
Fluctuating prices of essential oils, plant extracts, and chemical ingredients continue to challenge manufacturers. Disruptions in global logistics and dependency on imported raw materials increase production costs. Maintaining product quality and price stability has become complex for both mass and premium brands. Companies are now diversifying suppliers and adopting localized sourcing to mitigate these pressures and maintain profitability.
Counterfeit Products and Market Saturation
The growing presence of counterfeit and low-quality imitations in online and offline retail channels undermines consumer trust. Saturation in key product categories like shampoos and conditioners limits differentiation opportunities. Established brands face rising competition from emerging local and D2C players offering niche formulations. Strengthening brand authenticity, regulatory compliance, and consumer education are critical to overcoming these challenges.
Regional Analysis
North America North America holds the largest share of about 34% in the global hair care market in 2024. Strong consumer spending on premium and natural products drives regional growth. The demand for clean-label, sulfate-free, and dermatologist-approved formulations remains high. Major brands are expanding through online retail and salon-exclusive lines to attract health-conscious consumers. The U.S. dominates due to high product innovation, while Canada’s market benefits from sustainable and vegan trends. Evolving male grooming habits and increased awareness of scalp wellness further support continued growth across this mature market.
Europe
Europe accounts for nearly 28% share of the hair care market in 2024. The region’s focus on sustainability, organic certification, and ingredient transparency fuels steady expansion. Consumers increasingly prefer eco-friendly packaging and cruelty-free products. Strong performance in countries like Germany, France, and the UK is supported by premium brand adoption and salon-grade treatments. Regulatory standards promoting safe and natural ingredients have shaped innovation. E-commerce and influencer-led campaigns also enhance brand reach, helping European manufacturers strengthen their position in global markets.
Asia Pacific Asia Pacific represents approximately 24% share of the global hair care market in 2024. Rapid urbanization, rising disposable incomes, and increasing awareness of scalp care drive strong demand. Countries such as China, Japan, and India lead consumption, supported by evolving grooming routines and local brand innovation. Consumers prefer herbal and plant-based products tailored for regional hair types. Expanding retail channels and aggressive digital marketing strategies enhance accessibility. The region’s growing young population and preference for personalized care solutions continue to make it the fastest-growing market globally.
Latin America
Latin America holds around 8% share of the global hair care market in 2024. Growth is led by Brazil and Mexico, driven by high consumption of shampoos, conditioners, and oils. Cultural emphasis on hair appearance and increasing salon services contribute to product demand. Local brands are gaining traction through affordable, region-specific formulations using natural ingredients. Rising awareness about scalp health and digital retail growth also support expansion. Economic fluctuations remain a restraint, but innovation in mid-range and herbal-based categories sustains steady progress across the region.
Middle East & Africa
The Middle East and Africa region captures about 6% share of the hair care market in 2024. Growing focus on personal grooming, especially among younger consumers, is driving market penetration. The demand for anti-hair fall and moisturizing products remains high due to dry climatic conditions. Countries like the UAE and South Africa lead regional consumption, supported by rising retail modernization and beauty salon growth. Increasing availability of international brands and local manufacturing investments strengthen the competitive landscape. Natural oil-based and halal-certified products are gaining popularity among consumers seeking ethical and functional solutions.
Market Segmentations:
By Product Type
- Shampoo
- Conditioner
- Hair oil
By Ingredient
- Organic
- Synthetic
By Hair Type
- Straight hair
- Curly hair
- Wavy hair
- Others (thick hair etc.)
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The hair care market features strong competition among global leaders such as L’Oréal, Unilever, Procter & Gamble, Estée Lauder, Shiseido, Henkel, KAO Group, LVMH, Johnson & Johnson, Coty, Revlon, Avon, Aveda, Paul Mitchell, and Redken. The industry is characterized by continuous innovation, brand diversification, and expanding product portfolios catering to varied hair types and consumer preferences. Companies focus on clean formulations, premium product launches, and sustainable packaging to strengthen brand equity. Digital marketing, influencer partnerships, and direct-to-consumer strategies are key tools for maintaining market relevance. Mergers, acquisitions, and collaborations with biotech and cosmetic research firms enhance product innovation and regional reach. Increasing investment in R&D supports the development of scalp-focused treatments, eco-friendly formulations, and personalized solutions. The competition is further intensified by emerging niche brands that target specialized segments such as vegan, organic, or gender-neutral hair care, compelling established players to adapt and modernize their strategies globally.
Key Player Analysis
- L’Oréal
- Unilever
- Procter & Gamble
- Estée Lauder
- Shiseido
- Henkel
- KAO Group
- LVMH
- Johnson & Johnson
- Coty
- Revlon
- Avon
- Aveda
- Paul Mitchell
- Redken
Recent Developments
- In 2025, Aveda has been focusing on sustainability and personalized wellness in hair care. They emphasize naturally derived ingredients, eco-friendly packaging, and personalized scalp therapies and aromatherapy treatments as part of their holistic self-care approach.
- In 2025, Henkel Launched Schwarzkopf Gliss hair-care range across GCC markets.
- In 2025, L'Oréal signed an agreement to acquire the premium hair brand Color Wow in June 2025 (specifically, on June 30, 2025), and the acquisition was completed in September 2025.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Ingredient, Hair Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for clean, natural, and chemical-free hair care products will continue to rise.
- Personalization and AI-based diagnostics will shape future product development and marketing.
- E-commerce and digital engagement will further dominate hair care sales channels.
- Brands will focus on scalp health and preventive care rather than just cosmetic results.
- Sustainable packaging and eco-friendly manufacturing will become industry standards.
- Male grooming and gender-neutral product lines will expand the consumer base.
- Biotechnology will drive innovation in active ingredients and performance formulations.
- Premium and salon-grade products will see stronger growth across urban markets.
- Emerging economies will offer high potential through local brand innovation and accessibility.
- Strategic partnerships and R&D investments will enhance competitiveness and market diversification.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Hair Care Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Hair Care Market projected to grow between 2025 and 2032?
Which Hair Care Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Hair Care Market?
Who are the leading companies in the Hair Care Market?
Which region commanded the largest share of the Hair Care Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 94.07 Billion → 2032: USD 119.17 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hair Care Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hair Care Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hair Care Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hair Care Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hair Care Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hair Care Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hair Care Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hair Care Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 94.07 Billion → 2032: USD 119.17 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hair Care Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hair Care Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Hair Care Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Hair Care Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

