
Market Overview
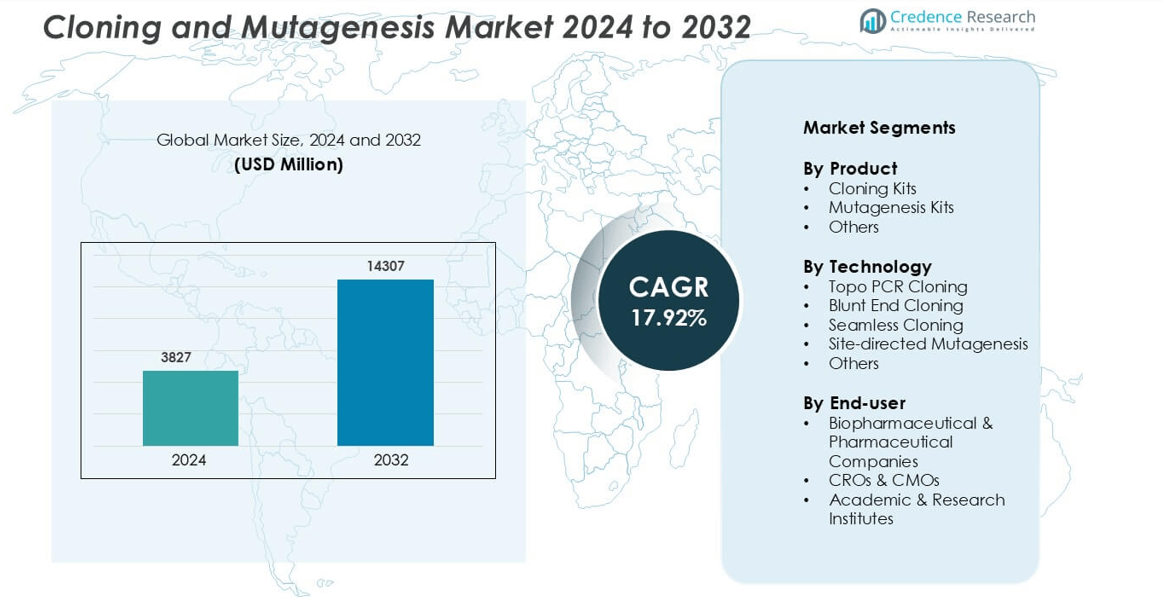
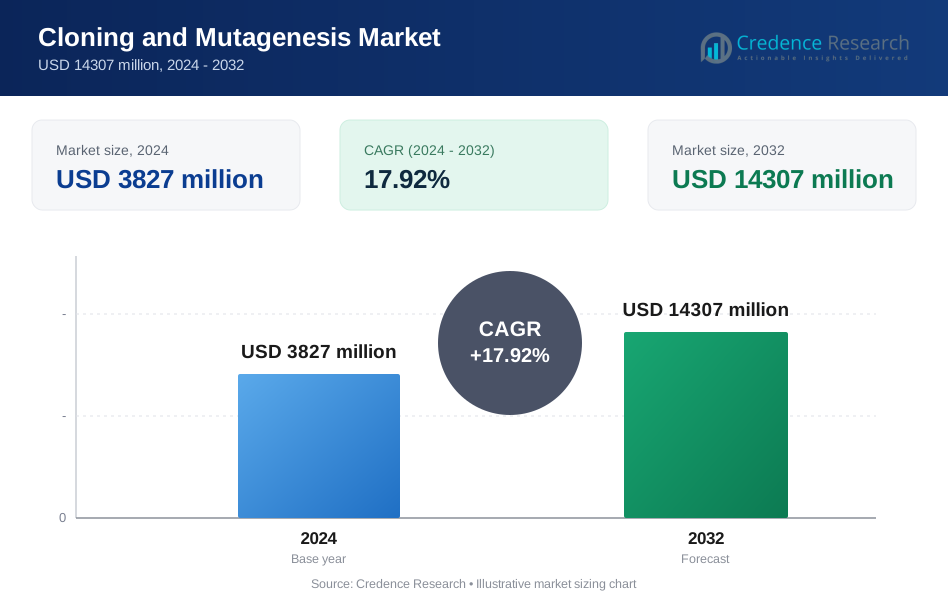
Cloning and Mutagenesis Market was valued at USD 3827 million in 2024 and is anticipated to reach USD 14307 million by 2032, growing at a CAGR of 17.92 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cloning and Mutagenesis Market Size 2024 | USD 3827 million |
| Cloning and Mutagenesis Market, CAGR | 17.92% |
| Cloning and Mutagenesis Market Size 2032 | USD 14307 million |
The Cloning and Mutagenesis Market is driven by key players including Thermo Fisher Scientific, Merck KGaA, Agilent Technologies, New England Biolabs, Promega Corporation, Takara Bio Inc., Bio-Rad Laboratories, Danaher, Jena Bioscience, and Assay Genie. These companies compete through high-fidelity enzymes, seamless cloning kits, automated platforms, and advanced site-directed mutagenesis solutions used across pharmaceutical research, synthetic biology, and academic labs. North America leads the global market with 38% share, supported by strong biotechnology infrastructure, high R&D spending, and widespread use of automated cloning workflows in gene expression studies, drug discovery, and protein engineering programs.
Market Insights
- The Cloning and Mutagenesis Market stands at USD 3827 million in 2024 and is set to reach USD 14307 million by 2032, growing at a CAGR of 17.92% during the forecast period.
- Rising demand for gene expression studies, recombinant protein production, and synthetic biology research drives widespread adoption of cloning and site-directed mutagenesis kits in biopharmaceutical and academic labs.
- Seamless cloning, enzyme-free workflows, and automation are key market trends, as labs prefer faster assembly, higher accuracy, reduced contamination risk, and scalable high-throughput capabilities.
- Strong competition exists among Thermo Fisher Scientific, Merck KGaA, Agilent Technologies, New England Biolabs, Promega, Takara Bio, Bio-Rad Laboratories, Danaher, Jena Bioscience, and Assay Genie, each expanding product portfolios with high-fidelity enzymes and ready-to-use kits.
- North America leads with 38% regional share, supported by high R&D spending and advanced lab infrastructure, while cloning kits hold the largest segment share due to rapid use in gene insertion, vector construction, and protein engineering.
Market Segmentation Analysis:
By Product
Cloning kits hold the dominant share in the product segment due to widespread adoption in gene insertion, library construction, and protein expression studies. Their high share comes from ready-to-use reagents, improved efficiency, and faster turnaround times compared to conventional cloning methods. Demand rises as labs focus on scalable workflows for recombinant DNA production and functional genomics research. Mutagenesis kits also show steady growth as researchers modify gene sequences to study protein structure or develop improved expression systems. The “others” category includes specialized buffers, enzymes, and consumables that support advanced molecular biology workflows in labs worldwide.
- For instance, Thermo Fisher's TOPO® PCR Cloning Kit enables ligation-independent cloning with a reported insertion success rate of up to 95%, and the cloning reaction is complete within 5 minutes of setup, followed by an overnight incubation period for colonies to form.
By Technology
Site-directed mutagenesis leads the technology segment with the highest market share, driven by its precision in altering specific DNA sequences without affecting the rest of the genome. Its dominance comes from applications in protein engineering, drug discovery, and foundational genetic studies. Topo PCR cloning and seamless cloning gain traction as labs move to faster, enzyme-based systems that reduce hands-on work and error rates. Blunt end cloning remains relevant for simple insertions with minimal sequence changes. The “others” category includes emerging hybrid and automated approaches that support synthetic biology, CRISPR research, and advanced vector engineering.
- For instance, Agilent QuikChange Lightning Kit perform site-directed mutagenesis in as little as 3 hpurs and supports fragment lengths up to 14 kb with high-fidelity amplification.
By End-user
Biopharmaceutical and pharmaceutical companies hold the dominant share in the end-user segment due to high investment in recombinant proteins, vaccine development, and targeted therapeutics. Their lead is supported by large-scale R&D budgets, automated cloning workflows, and partnerships with genomics solution providers. CROs and CMOs adopt cloning and mutagenesis tools to deliver contract-based services involving gene expression studies and protein manufacturing. Academic and research institutes remain vital users, especially in basic biology, synthetic biology, and medical research. Rising funding for gene therapy, precision medicine, and advanced molecular diagnostics continues to expand usage across all segments.
Key Growth Drivers
Rising Demand for Gene Expression and Protein Engineering
Growth in gene expression studies and protein engineering strengthens market demand, as scientists seek advanced tools to modify DNA sequences with high accuracy and shorter turnaround times. Pharmaceutical and biopharmaceutical companies use cloning and mutagenesis to create recombinant proteins, optimize biologic drugs, and develop next-generation vaccines. Expanding genomic research, synthetic biology programs, and biosimilar manufacturing further accelerate kit usage in commercial and academic labs. Automated PCR-based cloning, enzyme-free seamless workflows, and error-reduction technologies support faster project completion and scalable research output. Increasing funding for gene therapy, oncology research, and precision medicine makes cloning and mutagenesis essential for target validation and lead molecule development.
- For instance, the ÄKTA pure system comes in different models. The ÄKTA pure 25 model has a maximum normal flow rate of up to 25 mL/min. However, the ÄKTA pure 150 model supports a flow rate of up to 150 mL/min.
Growing Investment in Synthetic Biology and Gene Editing
The market benefits from large-scale investment in synthetic biology, genome engineering, and CRISPR-based research. Scientists need precise mutagenesis and cloning to design artificial DNA constructs, control gene circuits, and develop engineered cell systems. Start-ups, research institutes, and pharmaceutical firms invest in new cloning systems that handle complex DNA fragments, high-throughput screening, and programmable vector assembly. Site-directed mutagenesis supports optimization of enzyme activity, stability, and binding efficiency, enabling new industrial and therapeutic applications. Expanding applications in agriculture, microbiome editing, biofuel production, and molecular diagnostics widen the market base. Government funding and private capital continue to boost growth in advanced molecular engineering platforms.
- For instance, Integrated DNA Technologies (IDT) offers various gRNA formats, including sgRNAs that are typically around 100 nucleotides long. They have optimized manufacturing protocols for long RNA oligonucleotides, so 120 nucleotides is a reasonable length they could offer.
Expansion of Contract Research and Outsourcing Models
Contract research organizations (CROs) and contract manufacturing organizations (CMOs) increasingly adopt cloning and mutagenesis platforms to support outsourced drug development, genetic analysis, and protein production. Outsourcing improves cost efficiency for pharmaceutical companies while enabling faster project turnaround. CROs provide specialized gene construction, mutagenesis libraries, and expression system optimization for academic and commercial clients. High demand for recombinant antibodies, cell-based assays, and engineered plasmids drives continuous adoption of advanced kits and automation tools. Growth in global biotech start-ups and personalized medicine projects encourages outsourcing of cloning and mutagenesis operations rather than developing in-house facilities.
Key Trends & Opportunities
Shift Toward High-Throughput and Automated Workflows
Automation and high-throughput cloning platforms create major opportunities, as researchers move away from traditional manual workflows. Advanced systems reduce contamination risks, lower experimental error rates, and support seamless DNA assembly. Automated mutagenesis enables large variant library creation for enzyme engineering, antibody development, and protein optimization. Cloud-based data analysis, robotics, and AI-assisted primer design also enhance efficiency in labs handling large sample volumes. Emerging digital inventory, LIMS integration, and real-time monitoring create new service opportunities for vendors. As drug discovery, vaccine development, and synthetic biology projects scale, automated cloning becomes an essential part of modern lab infrastructure.
- For instance, The MCA 384 head can accurately and precisely pipette volumes as low as 0.5 µl with a CV <4% (using 15 µl tips), and volumes of 2.0 µl with a CV <3% (using 125 µl tips).
Growing Adoption of Seamless and Enzyme-Free Cloning
Seamless cloning, enzyme-free recombination, and ligation-independent technologies gain momentum due to their speed, simplicity, and ability to assemble multiple DNA fragments without unwanted sequence scars. These approaches eliminate the need for restriction digestion and ligase reactions, reducing workflow steps and improving efficiency. Researchers in gene therapy, metabolic engineering, and CRISPR vector development use seamless tools to build complex constructs quickly. Adoption also rises among start-ups and teaching labs due to simplified protocols and minimal specialized equipment requirements. Vendors offering multi-fragment kits, high-efficiency primers, and error-correction enzymes have strong growth opportunities as labs transition from traditional cloning methods.
- For instance, Gibson Assembly, commercialized by New England Biolabs, supports the assembly of up to 15 DNA fragments in a single reaction and constructs up to 100 kb in size with verified sequence accuracy.
Key Challenges
High Cost of Advanced Kits and Reagents
Despite strong adoption, the high cost of mutagenesis kits, cloning enzymes, reagents, and consumables remains a barrier for small labs and academic institutions. Complex enzyme mixes, multi-fragment assembly tools, and premium error-free kits increase operational budgets. Emerging markets struggle with pricing differences, import duties, and limited supplier availability. Some researchers continue using traditional restriction-based cloning to reduce expenditure, slowing the transition to seamless and automated systems. Vendors must balance innovation with affordability to serve price-sensitive users and maintain long-term adoption.
Technical Limitations and Workflow Complexity
Commercial kits reduce manual effort, but cloning and mutagenesis still demand skilled execution, precision primer design, and optimization of PCR conditions. Failed assemblies, mutation errors, off-target effects, and low cloning efficiency impact project timelines. Complex constructs with long DNA fragments or multiple inserts pose additional challenges. Limited automation in small facilities and lack of standardized workflows create variability in experimental success. These technical hurdles highlight the need for improved high-fidelity enzymes, AI-supported design tools, and integrated validation systems to ensure reproducible results across diverse research environments.
Regional Analysis
North America
North America leads the Cloning and Mutagenesis Market with 38% share, driven by strong biotechnology infrastructure and high adoption of advanced molecular cloning systems. The United States contributes the majority of revenue due to well-funded pharmaceutical research, gene therapy trials, and widespread automation in lab workflows. CROs and CMOs support demand with outsourced gene construction and recombinant protein services. Strong university networks, federal research grants, and early access to innovative kits reinforce market dominance. Canada adds steady contribution through growing investments in biopharmaceutical development and academic molecular biology programs.
Europe
Europe holds 29% market share, supported by active academic research, strong pharmaceutical manufacturing, and government-backed genomics initiatives. Germany, the United Kingdom, and France account for the highest regional usage of site-directed mutagenesis, seamless cloning, and CRISPR-based vector assembly. EU funding supports synthetic biology start-ups and cross-border research collaborations involving recombinant proteins and vaccine development. Regional CROs provide gene modification services to international clients, strengthening market expansion. Strong regulatory focus on biologics and precision medicine ensures sustained adoption across research institutes and commercial labs.
Asia Pacific
Asia Pacific accounts for 24% market share and records the fastest growth rate, supported by rising biotechnology investment and expanding pharmaceutical manufacturing capacity. China, Japan, India, and South Korea lead in adoption of PCR-based cloning, synthetic biology workflows, and mutagenesis platforms for protein engineering. Government grants, start-up funding, and academic research partnerships drive large-scale genomics and vaccine research. Competitive pricing and strong CRO presence attract outsourcing from Western biopharma companies. Rapid expansion of molecular diagnostics strengthens long-term demand.
Latin America
Latin America represents 6% market share, with gradual growth led by Brazil, Mexico, and Argentina. Regional universities and public health institutes adopt cloning and mutagenesis for infectious disease research, agricultural biotechnology, and recombinant vaccine studies. Increasing partnerships with multinational biotech suppliers support technology transfer and training. Budget constraints limit high-end automation adoption, but low-cost mutagenesis and PCR cloning kits see rising demand. Growing biotech incubators and academic collaboration with North American and European institutions contribute to steady market development.
Middle East & Africa
The Middle East & Africa region holds 3% market share, with demand concentrated in Saudi Arabia, the UAE, and South Africa. Investments in healthcare modernization, academic genomics centers, and diagnostic research drive interest in molecular cloning tools. International joint research programs and medical university expansion expand market access. Adoption remains limited by infrastructure gaps and high cost of advanced kits, but procurement through centralized research organizations supports gradual penetration. Continued investment in biopharma and precision medicine is expected to improve long-term growth.
Market Segmentations:
By Product
- Cloning Kits
- Mutagenesis Kits
- Others
By Technology
- Topo PCR Cloning
- Blunt End Cloning
- Seamless Cloning
- Site-directed Mutagenesis
- Others
By End-user
- Biopharmaceutical & Pharmaceutical Companies
- CROs & CMOs
- Academic & Research Institutes
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Cloning and Mutagenesis Market includes global biotechnology suppliers, specialized reagent manufacturers, and companies offering integrated molecular biology platforms. Leading participants such as Thermo Fisher Scientific, Merck KGaA, Agilent Technologies, New England Biolabs, Promega Corporation, Takara Bio Inc., Bio-Rad Laboratories, Danaher, Jena Bioscience, and Assay Genie compete through product innovation, high-fidelity enzymes, seamless cloning kits, and advanced mutagenesis systems. Many companies focus on ready-to-use kits that reduce manual workload, speed up DNA assembly, and improve accuracy to meet the needs of biopharma, CROs, and research institutes. Strategic partnerships with genomic research labs and academic institutions support new product validation and accelerate technology adoption. The market also sees increased demand for automation, high-throughput cloning, and enzyme-free systems, encouraging vendors to expand product lines. Companies invest in R&D activities, supply chain strengthening, and customer training to retain competitive advantage in a rapidly advancing molecular biology environment.
Key Player Analysis
- Takara Bio Inc.
- Merck KGaA
- Agilent Technologies, Inc.
- Assay Genie
- Bio-Rad Laboratories, Inc.
- New England Biolabs
- Jena Bioscience GmbH
- Danaher
- Thermo Fisher Scientific, Inc.
- Promega Corporation
Recent Developments
- In Oct 2025, Agilent Technologies updated Quik Change guidance for complex primer designs. The note covers multi-insert primers and links to its web-based design tool. This supports faster, cleaner site-directed mutagenesis workflows.
- In Aug 2025, Merck KGaA reported Life Science growth and Process Solutions strength. Capacity and portfolio expansion support recombinant DNA, cloning, and editing applications.
- In September 2024, Takara Bio USA launched the Smart Chip ND real-time PCR system. High-throughput validation supports mutagenesis and cloning verification steps.
Report Coverage
The research report offers an in-depth analysis based on Product, Technology, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will grow as biopharmaceutical companies expand recombinant protein and vaccine development.
- High-throughput and automated cloning platforms will replace manual procedures in many labs.
- Seamless and enzyme-free cloning methods will gain wider adoption for multi-fragment assembly.
- Site-directed mutagenesis will remain essential for protein engineering and therapeutic antibody optimization.
- More CROs and CMOs will offer outsourced gene construction and mutagenesis services.
- Academic institutes will increase usage due to rising investment in genomics and synthetic biology.
- AI-supported primer design and error-correction tools will improve cloning accuracy and workflow speed.
- CRISPR research will boost demand for precision vector design and mutagenesis kits.
- Emerging markets in Asia Pacific will experience rapid growth as lab infrastructure expands.
- Companies will invest in lower-cost kits to support smaller labs and teaching institutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Cloning and Mutagenesis Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Cloning and Mutagenesis Market projected to grow between 2025 and 2032?
Which Cloning and Mutagenesis Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Cloning and Mutagenesis Market?
Who are the leading companies in the Cloning and Mutagenesis Market?
Which region commanded the largest share of the Cloning and Mutagenesis Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3827 million → 2032: USD 14307 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cloning and Mutagenesis Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cloning and Mutagenesis Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cloning and Mutagenesis Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cloning and Mutagenesis Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cloning and Mutagenesis Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cloning and Mutagenesis Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cloning and Mutagenesis Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cloning and Mutagenesis Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3827 million → 2032: USD 14307 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cloning and Mutagenesis Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cloning and Mutagenesis Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cloning and Mutagenesis Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cloning and Mutagenesis Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

