
Market Overview
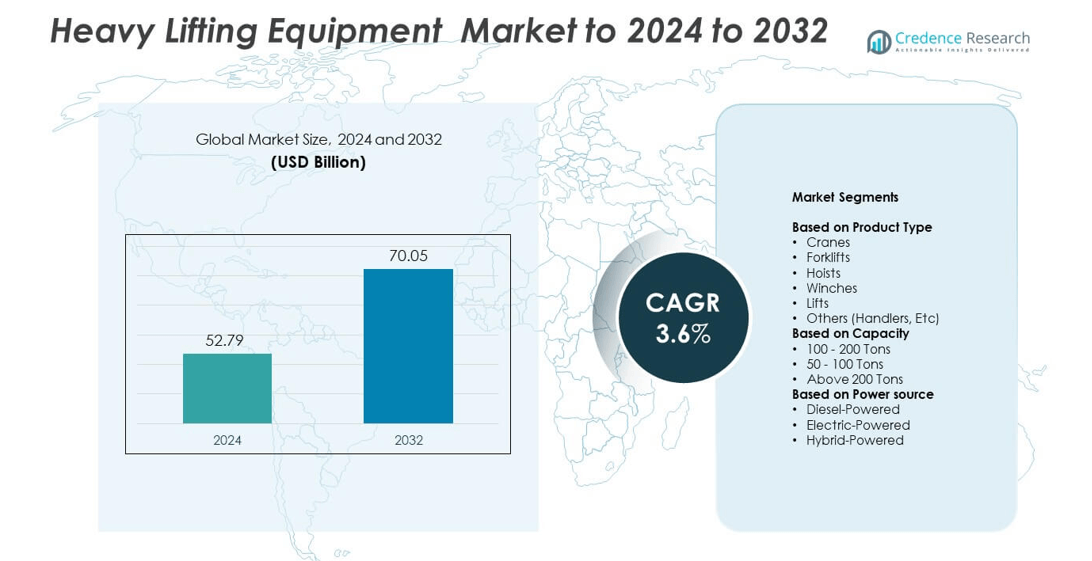
The Heavy Lifting Equipment Market size was valued at USD 52.79 billion in 2024 and is anticipated to reach USD 70.05 billion by 2032, at a CAGR of 3.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Heavy Lifting Equipment Market Size 2024 | USD 52.79 billion |
| Heavy Lifting Equipment Market, CAGR | 3.6% |
| Heavy Lifting Equipment Market Size 2032 | USD 70.05 billion |
The heavy lifting equipment market is dominated by leading players such as Liebherr, Komatsu, Tadano, Palfinger, Konecranes, Demag Cranes & Components, Manitowoc Company, SANY, and Cargotec, among others. These companies compete through innovation, extensive distribution networks, and expansion into emerging economies. They focus on developing energy-efficient, automated, and hybrid-powered equipment to meet global sustainability standards. Strategic mergers and partnerships enhance their product portfolios and strengthen aftersales support. North America leads the global market with a 34% share, followed by Europe at 28% and Asia-Pacific at 26%, reflecting strong industrial demand and infrastructure investment across key regions.
Market Insights
- The Heavy Lifting Equipment Market was valued at USD 52.79 billion in 2024 and is projected to reach USD 70.05 billion by 2032, growing at a CAGR of 3.6%.
- Rising infrastructure and industrial development, along with the adoption of automation, are driving strong demand for advanced lifting machinery across sectors.
- Key trends include the growing use of electric and hybrid-powered cranes, integration of IoT-based monitoring systems, and emphasis on sustainability in equipment design.
- The market is highly competitive, with major players focusing on innovation, mergers, and digital solutions to strengthen their global footprint.
- North America led the market with a 34% share in 2024, followed by Europe at 28% and Asia-Pacific at 26%, while cranes remained the dominant product segment, holding 42% of the overall share.
Market Segmentation Analysis:
By Product Type
Cranes dominated the heavy lifting equipment market with a 42% share in 2024. Their versatility in construction, mining, and offshore applications drives widespread adoption. Mobile cranes, in particular, support large infrastructure projects requiring flexible load-handling capabilities. Forklifts and hoists also show steady growth due to increased use in logistics and manufacturing. Advancements in automation, telematics, and load monitoring systems are enhancing efficiency and safety standards, further strengthening crane demand across both developed and emerging economies.
- For instance, Liebherr’s LR 11000 crane lists 1,000 t capacity, 220 m hoist height, and 184 m radius.
By Capacity
The 100–200 tons segment held the largest share of 46% in 2024. This range offers the ideal balance of lifting strength and operational flexibility, making it suitable for construction, shipbuilding, and heavy manufacturing. Equipment in this range is widely preferred for infrastructure development and industrial plant expansion. The growing number of renewable energy projects, such as wind farms and power stations, continues to fuel demand for mid-range lifting equipment with improved reach and stability.
- For instance, Tadano’s AC 5.160-1 all-terrain crane provides 160 t capacity and a 68 m main boom, with 14.51 m overall length.
By Power Source
Diesel-powered equipment led the market with a 61% share in 2024. Diesel models remain dominant due to their high torque output and suitability for outdoor and heavy-duty operations. They are essential in large construction sites, ports, and mining projects where continuous operation is required. However, electric and hybrid-powered variants are gaining traction driven by emission regulations and sustainability goals. Technological upgrades in battery performance and charging systems are further encouraging the shift toward cleaner lifting solutions worldwide.
Key Growth Drivers
Rising Infrastructure and Industrial Development
Global investments in infrastructure and industrial expansion are fueling heavy lifting equipment demand. Large-scale projects in transportation, energy, and construction sectors require advanced lifting solutions for efficiency and safety. The growing emphasis on urban infrastructure, ports, and renewable installations supports consistent demand for cranes, forklifts, and hoists. Emerging economies, particularly in Asia-Pacific, are witnessing significant construction activities, increasing equipment procurement across public and private sectors. This surge in development projects directly drives the steady expansion of the heavy lifting equipment market worldwide.
- For instance, Mammoet notes modern wind-turbine components reaching 136 t, increasing heavy-lift demand at energy sites.
Technological Advancements and Automation
Automation and digital integration are transforming heavy lifting operations. Modern equipment now features telematics, remote monitoring, and predictive maintenance systems, improving uptime and operational precision. Manufacturers are integrating sensors, AI-based load control, and IoT connectivity to enhance safety and efficiency. These innovations minimize manual errors and support compliance with safety regulations. The transition toward automated lifting systems is especially beneficial in logistics and offshore sectors, where precision and safety are critical. This technological evolution continues to boost equipment adoption globally.
- For instance, Linde Material Handling capped charging at 180 kW for 17 K-trucks using connect:charger, supporting continuous, telematics-driven operations.
Growing Emphasis on Safety and Efficiency
Stringent safety regulations and the need to optimize material handling efficiency are major market drivers. Companies are investing in equipment with advanced control systems, overload protection, and operator assistance features. The focus on reducing workplace accidents and improving operational performance is encouraging the replacement of outdated machines with new, compliant models. Industries such as construction, mining, and shipping prioritize high-performance lifting solutions that enhance safety while reducing operational costs, thereby driving steady market expansion across multiple sectors.
Key Trends & Opportunities
Adoption of Electric and Hybrid Equipment
The transition toward electric and hybrid-powered lifting equipment is gaining strong momentum. Rising fuel costs and environmental regulations are encouraging businesses to adopt energy-efficient alternatives. Electric-powered cranes and forklifts offer lower maintenance costs and reduced emissions, aligning with global sustainability goals. Battery technology advancements are extending operating hours and reducing downtime, improving productivity across industries. This shift presents a strong opportunity for manufacturers focusing on eco-friendly and high-performance lifting equipment solutions in both developed and emerging markets.
- For instance, Plug Power reports over 72,000 fuel-cell systems deployed and 275 hydrogen fueling stations, underpinning electric fleet adoption.
Integration of Smart and Connected Technologies
Smart lifting systems equipped with IoT sensors, GPS, and analytics platforms are reshaping the industry. These systems enable real-time tracking, performance diagnostics, and predictive maintenance, ensuring greater reliability and safety. Data-driven insights help operators optimize load capacity and prevent equipment failures. The use of cloud-based monitoring tools and AI-driven automation is transforming operations in construction, logistics, and manufacturing. As industries prioritize digital transformation, connected lifting solutions are emerging as a key opportunity for sustained market growth.
- For instance, Manitowoc’s parts network manages more than 70,000 unique part numbers through global distribution centers, reflecting high upkeep complexity.
Key Challenges
High Initial Costs and Maintenance Expenses
Heavy lifting equipment involves significant capital investment and maintenance costs. Small and medium-sized enterprises often face financial constraints in acquiring modern, automated machinery. Frequent component servicing, compliance upgrades, and spare part replacements further increase operational expenses. High entry costs restrict adoption in developing economies, where leasing and rental alternatives are preferred. Despite long-term efficiency benefits, these cost challenges continue to slow the widespread transition to advanced heavy lifting solutions among cost-sensitive end users.
Skilled Labor Shortage and Safety Compliance
The shortage of skilled operators remains a pressing issue in the heavy lifting equipment market. Operating complex machinery requires technical expertise and training to ensure safe and efficient handling. Inadequate skill levels increase the risk of accidents and equipment misuse, leading to downtime and productivity loss. Moreover, strict safety compliance standards across industries demand continuous workforce training. Companies are investing in simulation-based operator training and certification programs to address this challenge and enhance operational reliability.
Regional Analysis
North America
North America held the largest share of 34% in the heavy lifting equipment market in 2024. The region’s growth is driven by extensive construction, oil and gas, and port infrastructure projects across the United States and Canada. High adoption of advanced cranes, forklifts, and hoists supports industrial efficiency and safety compliance. Manufacturers focus on automation and hybrid-powered equipment to meet stringent emission standards. Expanding logistics and manufacturing sectors also contribute to equipment modernization. Continuous investments in renewable energy and industrial facilities further strengthen North America’s leading market position.
Europe
Europe accounted for a 28% share in the heavy lifting equipment market in 2024. The region benefits from robust demand in automotive, construction, and offshore wind energy sectors. Countries such as Germany, the Netherlands, and the United Kingdom are leading adopters of smart lifting technologies. Increasing focus on workplace safety and energy efficiency drives the replacement of older machinery with modern, digitalized systems. Strong presence of key manufacturers and government-backed infrastructure programs also support market growth. Rising investments in green construction and electric equipment adoption further sustain Europe’s steady expansion.
Asia-Pacific
Asia-Pacific captured a 26% market share in 2024, supported by rapid urbanization, industrialization, and infrastructure development. China, India, Japan, and South Korea are major contributors, driven by growing construction and manufacturing activities. Government initiatives in smart cities and transportation modernization are fueling equipment demand. Local manufacturers are expanding production capacities to meet domestic needs while exporting to other regions. The growing preference for cost-effective and energy-efficient models is shaping market competition. Asia-Pacific’s strong economic growth and large-scale industrial projects position it as a key emerging market for heavy lifting solutions.
Latin America
Latin America held an 8% share of the global heavy lifting equipment market in 2024. The region’s demand is rising due to ongoing infrastructure projects in Brazil, Mexico, and Chile. Expansion in mining, oil exploration, and logistics sectors is driving adoption of cranes and hoists. Economic reforms and foreign investments are encouraging modernization of heavy machinery fleets. However, high equipment costs and limited local manufacturing capacity restrain faster growth. Increasing government efforts to improve port and transportation infrastructure are expected to create new opportunities for market expansion in the region.
Middle East & Africa
The Middle East & Africa accounted for a 7% market share in 2024, primarily driven by construction, oil and gas, and industrial projects. Countries such as Saudi Arabia, the UAE, and South Africa are investing heavily in infrastructure modernization and energy diversification. Demand for high-capacity cranes and heavy-duty lifting systems is increasing in large-scale industrial and petrochemical complexes. Despite challenges related to import dependency, regional governments are supporting domestic manufacturing initiatives. Continued urban development and diversification of non-oil industries will further strengthen the market outlook across the region.
Market Segmentations:
By Product Type
- Cranes
- Forklifts
- Hoists
- Winches
- Lifts
- Others (Handlers, Etc)
By Capacity
- 100 - 200 Tons
- 50 - 100 Tons
- Above 200 Tons
By Power source
- Diesel-Powered
- Electric-Powered
- Hybrid-Powered
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The heavy lifting equipment market is highly competitive, with major players such as Liebherr, Komatsu, Tadano, Palfinger, Konecranes, Demag Cranes & Components, Manitowoc Company, SANY, Sarens, Cargotec, Shanghai Zhenhua Heavy Industries (ZPMC), Mammoet, Sennebogen, JASO Industrial Cranes, Terex, Agilent Technologies, Waters Corporation, Bruker, and Becton Dickinson shaping the industry landscape. Companies are focusing on product innovation, automation, and energy-efficient lifting systems to strengthen market presence. Strategic collaborations, mergers, and investments in digital technologies are enhancing operational performance and safety standards. Manufacturers are expanding production capacities and service networks to meet global infrastructure and industrial demand. Emphasis on sustainable designs, electric and hybrid-powered machinery, and remote monitoring solutions is driving long-term competitiveness. Continuous research and development in telematics and smart load management systems are enabling companies to cater to evolving construction, logistics, and manufacturing requirements while maintaining reliability and efficiency across diverse applications.
Key Player Analysis
- Liebherr
- Komatsu
- Tadano
- Palfinger
- Konecranes
- Demag Cranes & Components
- Manitowoc Company
- SANY
- Sarens
- Cargotec
- Shanghai Zhenhua Heavy Industries (ZPMC)
- Mammoet
- Sennebogen
- JASO Industrial Cranes
- Terex
- Agilent Technologies
- Waters Corporation
- Bruker
- Becton Dickinson
Recent Developments
- In 2025, Liebherr introduced the LR 1300.2 SX unplugged, an all-electric 300-tonne crawler crane designed for emission-free and quiet operation
- In 2024, Konecranes launched the flagship X-series industrial crane, which features advanced capabilities like wireless software upgrades, remote monitoring, and several "Smart Features," including automatic load sensing functions.
- In 2023, Komatsu Ltd. Launched a 20-ton PC210LCE electric excavator with a large battery capacity for extended operating time.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Capacity, Power Source and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increasing automation and digital control systems will enhance equipment precision and safety.
- Demand for electric and hybrid-powered lifting equipment will grow due to emission regulations.
- Integration of IoT and AI technologies will enable predictive maintenance and real-time monitoring.
- Expansion of renewable energy projects will drive the need for high-capacity lifting systems.
- Urbanization and infrastructure modernization will continue to support market growth globally.
- Equipment rental and leasing services will expand as cost-effective alternatives for small firms.
- Manufacturers will focus on lightweight materials to improve fuel efficiency and load capacity.
- Safety compliance standards will push the adoption of smart load management systems.
- Developing regions will witness rapid adoption through government-led industrialization programs.
- Ongoing R&D investments will lead to advanced, sustainable, and connected heavy lifting solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Heavy Lifting Equipment Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Heavy Lifting Equipment Market projected to grow between 2025 and 2032
Which Heavy Lifting Equipment Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Heavy Lifting Equipment Market?
Who are the leading companies in the Heavy Lifting Equipment Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 52.79 billion → 2032: USD 70.05 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Heavy Lifting Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Heavy Lifting Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Heavy Lifting Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Heavy Lifting Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Heavy Lifting Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Heavy Lifting Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Heavy Lifting Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Heavy Lifting Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 52.79 billion → 2032: USD 70.05 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Heavy Lifting Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Heavy Lifting Equipment Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Heavy Lifting Equipment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Heavy Lifting Equipment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

