
Market Overview
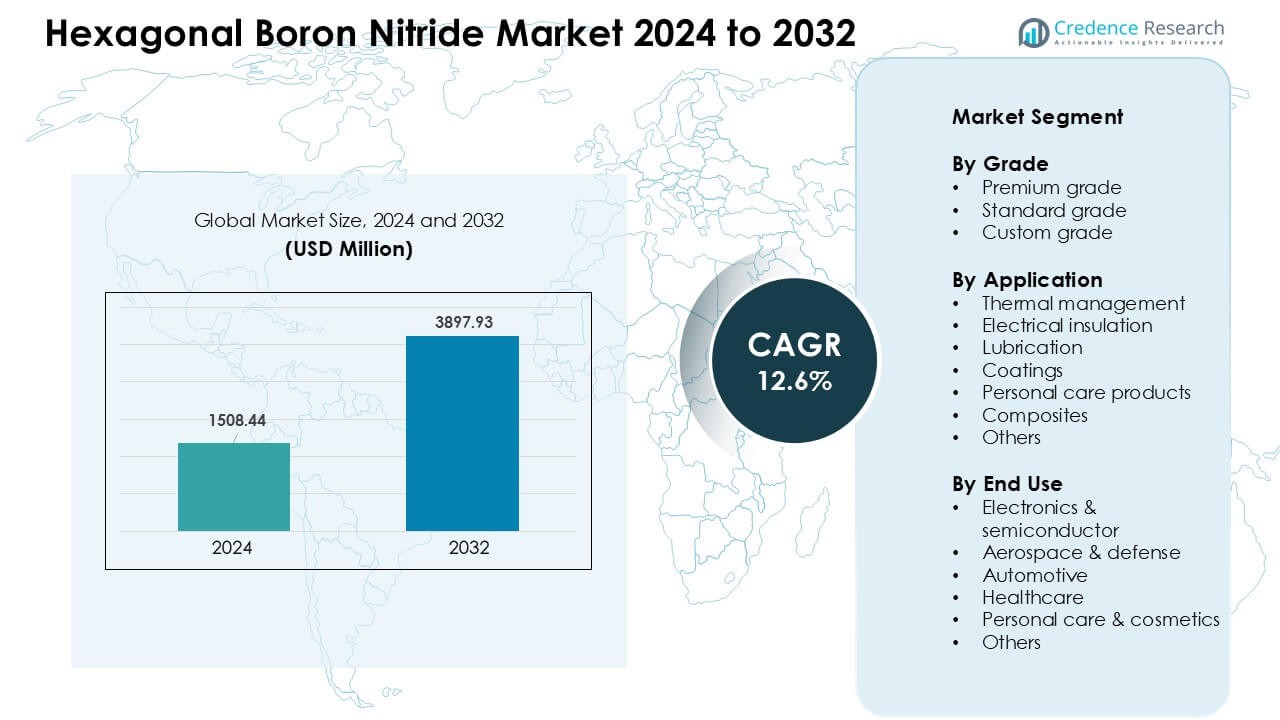
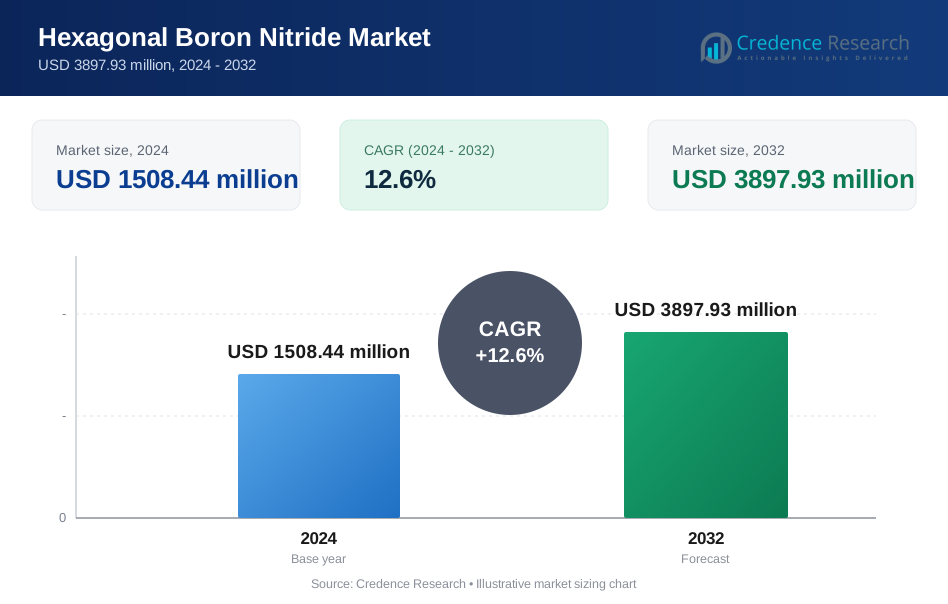
Hexagonal Boron Nitride Market was valued at USD 1508.44 million in 2024 and is anticipated to reach USD 3897.93 million by 2032, growing at a CAGR of 12.6 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hexagonal Boron Nitride Market Size 2024 | USD 1508.44 Million |
| Hexagonal Boron Nitride Market, CAGR | 12.6 % |
| Hexagonal Boron Nitride Market Size 2032 | USD 3897.93 Million |
The Hexagonal Boron Nitride Market is shaped by key players such as Precision Ceramics, Panadyne, Saint-Gobain, 3M, Momentive Technologies, Henze Boron Nitride Products, Grolltex, American Elements, Denka Company, and Resonac Holdings Corporation. These companies compete through high-purity BN grades, advanced thermal materials, and coatings tailored for electronics, aerospace, and automotive applications. Their focus on improved dispersion, consistent particle morphology, and expanded production capacity supports wider industrial adoption. Asia-Pacific led the global market in 2024 with about 41% share, driven by strong semiconductor manufacturing, rapid EV expansion, and large-scale materials production across China, Japan, and South Korea.
Market Insights:
- The Hexagonal Boron Nitride Market was valued at USD 44 million in 2024 and is projected to reach USD 3897.93 million by 2032, growing at a CAGR of 12.6 %.
- Demand rises due to strong thermal management needs in electronics, where premium-grade BN holds the largest segment share thanks to high conductivity and strong dielectric strength.
- Market trends highlight growing BN use in EV batteries, semiconductor packaging, and BN-enhanced composites as industries push for better heat resistance and lightweight materials.
- Competition intensifies as players such as Precision Ceramics, Saint-Gobain, 3M, Momentive Technologies, and Resonac expand high-purity BN output and upgrade dispersion technologies.
- Asia-Pacific leads the market with about 41% share, followed by North America at 36%, as electronics & semiconductor remains the dominant end-use segment globally.
Market Segmentation Analysis:
By Grade
Premium grade led the Hexagonal Boron Nitride Market in 2024 with the highest share due to its superior purity and strong thermal stability. Manufacturers preferred this grade for advanced electronics, aerospace parts, and high-performance lubricants. Demand rose as industries shifted toward materials that support tight tolerance, low contamination, and high conductivity needs. Standard grade maintained steady uptake in general industrial uses, while custom grade gained interest from buyers seeking tailored particle sizes and improved dispersion for niche applications across composites and coatings.
- For instance, Custom‑grade h‑BN powders are also offered by certain specialty suppliers who tailor the BET surface area and particle size distribution per customer specification to optimize dispersion in coatings or composite formulations.
By Application
Thermal management dominated the Hexagonal Boron Nitride Market in 2024 with the largest share, supported by rising use in heat-spreading films, insulating pads, and high-power electronic modules. The segment grew as device makers pushed for higher power density and safer operating temperatures in consumer and industrial electronics. Electrical insulation and lubrication applications expanded with wider adoption of BN powders in transformers, bearings, and metalworking fluids. Coatings, composites, and personal care products also grew due to better dispersion quality, smooth texture, and strong chemical resistance.
- For instance, in polymer composite films for electronic packaging, embedding just 7 wt% of h‑BN nanosheets lifted the in‑plane thermal conductivity to ~2.95 W·m⁻¹·K⁻¹ from much lower baseline values demonstrating that even modest filler loading significantly aids thermal management in compact electronics.
By End Use
Electronics and semiconductor remained the dominant end-use segment in 2024, holding the leading share as chipmakers sought materials with high thermal conductivity and strong dielectric strength. Growth accelerated with rising production of power electronics, EV components, and compact consumer devices. Aerospace and defense followed due to demand for lightweight, heat-resistant parts, while automotive expanded through increased use in EV thermal control systems. Healthcare, personal care, and other industries adopted BN for biocompatible coatings, smooth emulsions, and specialty composite reinforcement.
Key Growth Drivers:
Growing Demand for Advanced Thermal Management Materials
The Hexagonal Boron Nitride Market benefits from rising demand for materials that support high-performance thermal management in electronics, EVs, and industrial devices. Manufacturers seek reliable heat-spreading and heat-dissipation solutions as power density increases in next-generation chips, power modules, and battery systems. BN’s strong thermal conductivity and dielectric strength make it a preferred option for thermal interface materials, insulating pads, and composite parts. Growth in EV battery packs, 5G devices, and compact consumer electronics strengthens adoption. Investments in advanced semiconductor packaging and wide-bandgap devices further push BN’s relevance across thermal control applications.
- For instance, in battery pack thermal management for electric vehicles, h‑BN is used as a thermally conductive filler in polymer composites or as thermal interface materials (TIMs), enabling composites that maintain electrical insulation and enhance heat dissipation a key advantage over traditional fillers in EV battery and power‑electronics modules.
Rising Use of BN in High-Performance Coatings and Lubricants
Hexagonal boron nitride supports strong growth in coatings and lubrication due to its chemical inertness, high-temperature stability, and low friction properties. Industries rely on BN-based coatings to protect tools, furnace parts, molds, and aerospace components exposed to extreme operating conditions. Lubrication demand rises in sectors such as metalworking, mining, and automotive manufacturing as firms pursue materials that deliver cleaner operation and reduced wear. Growth in high-precision machining and energy equipment further drives interest. BN’s compatibility with both dry and wet lubrication systems encourages broader use across industrial processing and harsh-environment applications.
- For instance, h‑BN (often called white graphite ) exhibits a coefficient of friction in the range of 0.15–0.70 under sliding or contact conditions a trait leveraged when applied as a solid lubricant or coating on metal surfaces exposed to friction or wear.
Expansion of BN Use in Personal Care, Healthcare, and Composites
Demand for hexagonal boron nitride grows in personal care, healthcare, and composite applications due to its smooth texture, biocompatibility, and strong reinforcement ability. Cosmetic brands use BN to improve product feel, oil absorption, and light diffusion in foundations and skincare formulations. Healthcare segments apply BN for biocompatible coatings and controlled-environment tools. Composite makers leverage BN’s strength, heat resistance, and dispersion quality to enhance polymers used in electronics housings, aerospace panels, and automotive structures. Growth in lightweight materials, medical devices, and premium beauty products continues to create new opportunities for BN adoption.
Key Trends & Opportunities:
Rising Penetration in EV and Power Electronics Applications
The Hexagonal Boron Nitride Market sees strong opportunity from the rapid expansion of EVs and power electronics, where thermal stability and electrical insulation are essential. BN improves safety and lifespan in battery packs, power control units, and charging modules. The shift toward silicon carbide and gallium nitride devices increases the need for advanced thermal interface materials. BN-filled polymers and composites also support lightweighting goals in EV platforms. As global EV production scales, suppliers accelerate R&D on high-purity BN powders and better dispersion techniques to meet stricter performance needs in automotive electronics.
- For instance, h‑BN has a wide band gap (~5.97 eV) and dielectric properties that make it an excellent electrical insulator even when used as a thermally conductive filler — enabling safe use around high‑voltage battery cells and power modules without risk of short‑circuiting.
Advancements in BN-Enhanced Composites and Coating Technologies
A major opportunity emerges from advancements in BN-enhanced composites and coatings that offer improved durability, heat resistance, and chemical stability. Industries adopt BN composites for structural parts, electrical housings, and heat-resistant panels, driven by demand for lightweight and long-life materials. Coating technologies use BN to protect tools and machinery from oxidation, erosion, and thermal shock. Additive manufacturing also benefits as BN powders enable stronger, temperature-resilient printed components. These innovations create wider applications across aerospace, industrial manufacturing, and electronics, strengthening long-term demand for high-grade BN materials.
- For instance, a recent study fabricated composites by embedding 60 wt% hexagonal boron nitride (h‑BN) into a polyurethane (PU) matrix; the resulting BN60/PU composite exhibited a thermal conductivity of 0.653 W·m⁻ which is 218.7% higher than that of pure PU while retaining high flexibility (strain at break ~707%) and good mechanical integrity even after 1,000 bending cycles.
Key Challenges:
High Production Costs and Limited High-Purity Supply
The Hexagonal Boron Nitride Market faces challenges due to high production costs and limited availability of ultra-pure BN grades required for electronics, aerospace, and medical applications. Achieving consistent purity and small particle sizes increases manufacturing complexity and raises pricing for end users. Limited global suppliers for high-performance BN powders create additional supply pressure. These factors restrict adoption in cost-sensitive sectors and slow scale-up for emerging applications. Investments in process optimization, larger production capacities, and regional supply diversification are needed to overcome these constraints.
Performance Variability and Dispersion Difficulties in Composites
BN materials can show performance variability due to differences in particle morphology, purity, and surface characteristics, which complicate composite formulation. Achieving uniform dispersion in polymers and resins remains difficult, limiting mechanical strength and thermal performance in some applications. This challenge affects sectors such as automotive, aerospace, and electronics, where consistent reliability is critical. Manufacturers must invest in advanced surface treatments, coupling agents, and controlled synthesis methods to improve compatibility. Without these improvements, some high-value composite and coating applications may face slower adoption and higher development costs.
Regional Analysis
North America
North America held the largest share of the Hexagonal Boron Nitride Market in 2024 with about 36% due to strong adoption in electronics, aerospace, and advanced automotive applications. The region benefited from a mature semiconductor base, steady investments in thermal interface materials, and wider use of BN-based coatings for high-temperature components. EV manufacturing growth supported new demand for thermal management solutions. Research programs across the United States and Canada also pushed for improved BN purity and dispersion technologies. Expanding defense manufacturing and high-performance lubricants further strengthened the regional position.
Europe
Europe accounted for nearly 29% of the Hexagonal Boron Nitride Market in 2024, driven by strong demand from aerospace, automotive, and industrial equipment makers. The region emphasized high-performance materials that enable lower emissions, improved heat resistance, and stronger electrical insulation. Germany, France, and the U.K. led adoption with advanced manufacturing clusters and strict performance standards. Wider use of BN in composites and coatings supported market expansion, while the shift toward electric mobility boosted thermal management applications. Growing interest in BN for personal care products also added incremental demand across EU markets.
Asia-Pacific
Asia-Pacific held about 41% of the Hexagonal Boron Nitride Market in 2024, making it the fastest-growing and highest-consuming region. Strong electronics and semiconductor production in China, Japan, South Korea, and Taiwan drove heavy BN usage in thermal interface materials and insulating components. Expanding EV and battery supply chains increased demand for advanced heat-spreading products. Local manufacturers scaled BN output to meet rising needs in coatings, lubricants, and composites. Supportive industrial policies, strong supply chains, and growing R&D investments helped reinforce the region’s leadership in both volume and application diversity.
Latin America
Latin America captured roughly 8% of the Hexagonal Boron Nitride Market in 2024, supported by moderate growth in automotive, industrial equipment, and mining applications. Brazil and Mexico led market activity with rising use of BN-based lubricants and high-temperature coatings for heavy machinery. Demand increased as regional manufacturers upgraded thermal management systems to boost efficiency and reduce maintenance cycles. Adoption in electronics remained limited but improved with gradual expansion of local assembly operations. Interest in BN-filled composites and specialty coatings also increased as industries sought materials with better wear resistance.
Middle East & Africa
The Middle East & Africa region held about 6% of the Hexagonal Boron Nitride Market in 2024, driven by niche demand in aerospace maintenance, energy equipment, and industrial processing. Countries such as the UAE and Saudi Arabia increased adoption of BN-based thermal and insulating materials in advanced manufacturing projects. Growth in heavy machinery, mining, and oilfield operations supported wider use of high-temperature lubricants and protective coatings. Although the electronics sector remained small, investment in technology manufacturing hubs gradually improved uptake. Rising interest in BN composites for harsh-environment applications supported long-term potential.
Market Segmentations:
By Grade
- Premium grade
- Standard grade
- Custom grade
By Application
- Thermal management
- Electrical insulation
- Lubrication
- Coatings
- Personal care products
- Composites
- Others
By End Use
- Electronics & semiconductor
- Aerospace & defense
- Automotive
- Healthcare
- Personal care & cosmetics
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Hexagonal Boron Nitride Market includes leading companies such as Precision Ceramics, Panadyne, Saint-Gobain, 3M, Momentive Technologies, Henze Boron Nitride Products, Grolltex, American Elements, Denka Company, and Resonac Holdings Corporation. These firms compete through advancements in BN purity, particle-size control, and surface treatment technologies that support high-performance thermal, electrical, and lubrication applications. Producers invest in expanding capacity for premium-grade BN to meet growing demand from electronics, aerospace, automotive, and composite manufacturers. Many companies strengthen portfolios with BN powders, coatings, and custom-engineered components. Strategic partnerships with semiconductor, EV, and aerospace suppliers help secure long-term contracts. R&D efforts focus on improved dispersion, higher thermal conductivity, and lightweight composite integration to support next-generation device and material development.
Key Player Analysis
- Precision Ceramics
- Panadyne
- Saint-Gobain
- 3M
- Momentive Technologies
- Henze Boron Nitride Products
- Grolltex
- American Elements
- Denka Company
- Resonac Holdings Corporation
Recent Developments
- In August 2025, Precision Ceramics announced a strategic partnership with MillenniTEK to expand access to advanced boron-carbide and related ceramic materials across Europe, strengthening their technical ceramics offering (including h-BN machining/product support) and regional capacity.
- In January 2025, Panadyne published technical and application content highlighting hexagonal boron nitride (hBN) ceramics for plasma chambers and refreshed technical pages for their hBN powder offerings positioning their HBN powders for high-temperature, lubrication and mold-release uses in advanced manufacturing.
- In November 2023, Saint-Gobain launched CeraGlide Azure, a new pigmented line of boron-nitride coatings showcased at Aluminum USA (positioned for easier visual inspection and refractory protection in aluminum casting).
Report Coverage
The research report offers an in-depth analysis based on Grade, Application, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption will rise in thermal interface materials for high-power electronics and EV systems.
- BN demand will grow as semiconductor packaging moves toward higher power density designs.
- Use in BN-enhanced composites will expand across aerospace, automotive, and industrial equipment.
- Personal care applications will increase due to BN’s smooth texture and strong oil-absorption behavior.
- High-purity BN production will scale as suppliers invest in advanced synthesis technologies.
- BN coatings will gain traction for protecting tools and components exposed to extreme heat.
- Battery manufacturers will integrate BN materials to improve safety and thermal stability.
- Additive manufacturing will adopt BN powders for heat-resistant printed parts.
- Regional supply chains will diversify as more producers enter Asia-Pacific and North America.
- Performance improvements in dispersion and particle engineering will unlock new high-value applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Hexagonal Boron Nitride Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is Hexagonal Boron Nitride Market projected to grow between 2024 and 2032?
Which Hexagonal Boron Nitride Market segment held the largest share in 2024?
What are the primary factors fueling the growth of Hexagonal Boron Nitride Market?
Who are the leading companies in Hexagonal Boron Nitride Market?
Which region commanded the largest share of Hexagonal Boron Nitride Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Hexagonal Boron Nitride Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Hexagonal Boron Nitride Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1508.44 million → 2032: USD 3897.93 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Hexagonal Boron Nitride Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Hexagonal Boron Nitride Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Hexagonal Boron Nitride Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Hexagonal Boron Nitride Market Drivers
- 3.3 Hexagonal Boron Nitride Market Restraints & Challenges
- 3.4 Hexagonal Boron Nitride Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Hexagonal Boron Nitride Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Hexagonal Boron Nitride Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Hexagonal Boron Nitride category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Hexagonal Boron Nitride Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Hexagonal Boron Nitride Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Hexagonal Boron Nitride market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Hexagonal Boron Nitride Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Hexagonal Boron Nitride Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Hexagonal Boron Nitride Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Hexagonal Boron Nitride (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Hexagonal Boron Nitride Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Hexagonal Boron Nitride Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Hexagonal Boron Nitride Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Hexagonal Boron Nitride Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Hexagonal Boron Nitride Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Hexagonal Boron Nitride Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Hexagonal Boron Nitride Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Hexagonal Boron Nitride Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Hexagonal Boron Nitride Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
