
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hybrid Aircraft Market Size 2024 | USD 1836.54 million |
| Hybrid Aircraft Market , CAGR | 47.25% |
| Hybrid Aircraft Market Size 2032 | USD 40585.83 million |
Market Overview:
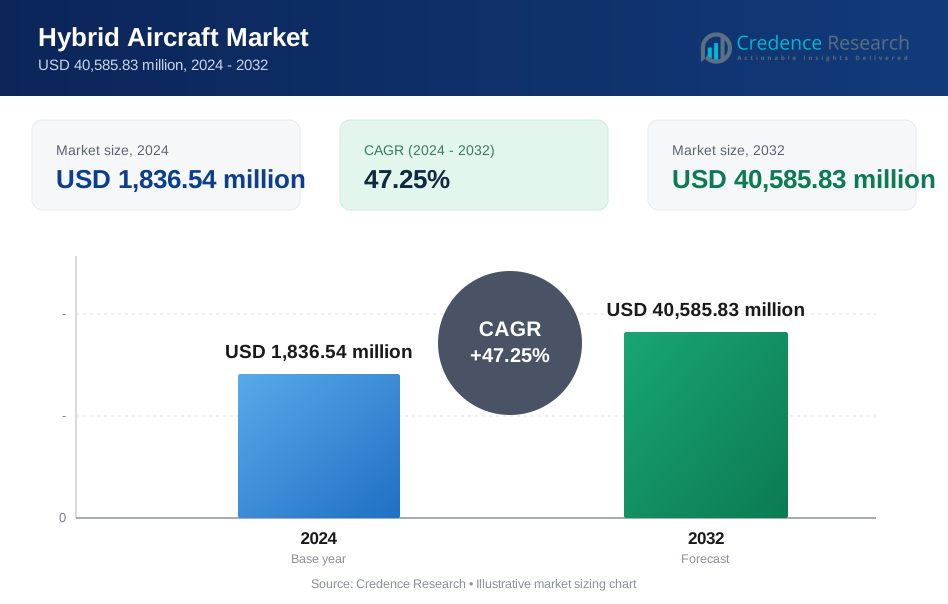
The Hybrid aircraft market is projected to grow from USD 1836.54 million in 2024 to an estimated USD 40585.83 million by 2032, with a compound annual growth rate (CAGR) of 47.25% from 2024 to 2032.
Several key factors are propelling the hybrid aircraft market forward. Foremost is the escalating demand for short-haul connectivity, particularly in regional and urban settings where hybrid-electric aircraft offer cost-effective and environmentally friendly solutions. Technological advancements in battery energy density, electric motors, and power management systems have made hybrid configurations more viable, enabling improved performance and range. Additionally, stringent global emissions regulations and the aviation sector's commitment to achieving net-zero carbon emissions by 2050 are compelling manufacturers and operators to invest in cleaner propulsion technologies. The integration of hybrid systems also offers operational benefits, such as reduced noise levels and lower maintenance costs, further incentivizing adoption.
Regionally, Europe is poised to lead the hybrid aircraft market, projected to register the highest CAGR during the forecast period. This growth is attributed to substantial investments in sustainable aviation initiatives, supportive regulatory frameworks, and the presence of key industry players focusing on hybrid-electric propulsion technologies. North America holds the largest market share, driven by significant research and development activities, government support, and early adoption of hybrid aircraft for both commercial and military applications. In the Asia-Pacific region, rapid urbanization and increasing air traffic are fueling demand for innovative air mobility solutions, positioning countries like China, Japan, and India as emerging markets for hybrid aircraft. These regions are investing in infrastructure and regulatory frameworks to accommodate the integration of hybrid-electric aircraft into their airspace.
Market Insights:
- The hybrid aircraft market is projected to grow from USD 1,836.54 million in 2024 to USD 40,585.83 million by 2032, at a CAGR of 47.25%.
- Demand for short-haul, low-emission air travel in regional and urban areas is driving hybrid aircraft adoption.
- Technological advancements in battery density, electric propulsion, and lightweight materials are enhancing aircraft performance and feasibility.
- Government policies, green aviation subsidies, and private investments are accelerating hybrid aircraft development and commercialization.
- Challenges such as limited battery range, high development costs, and lack of standardized infrastructure continue to slow adoption.
- North America holds the largest market share, while Europe is projected to register the highest CAGR due to strong sustainability initiatives.
- Asia-Pacific is emerging as a high-growth region, with countries like China, Japan, and India investing in hybrid aviation infrastructure and innovation.
Market Drivers:
Rising Demand for Sustainable Aviation is Accelerating Technological Shifts
The aviation industry is under increasing pressure to reduce its environmental footprint, prompting stakeholders to explore alternatives to traditional propulsion systems. The hybrid aircraft market benefits from this shift, offering lower emissions and improved fuel efficiency. Governments and regulatory bodies are introducing strict carbon emission standards, encouraging the adoption of cleaner technologies. Airlines and manufacturers are responding by investing in hybrid propulsion to comply with these mandates. It also addresses public concerns about the environmental impact of flying, which influences travel behavior and industry practices. Sustainable aviation goals are now integrated into long-term strategies, placing hybrid aircraft at the center of future air mobility plans.
- For example, the International Civil Aviation Organization (ICAO) has set a target for net-zero emissions by 2050, prompting airlines and manufacturers to accelerate investments in hybrid and electric propulsion systems.
Advancements in Battery and Electric Propulsion Technologies are Enabling Feasibility
Technical innovations in battery density, electric motors, and power management systems are making hybrid propulsion more viable for commercial applications. The hybrid aircraft market gains from the steady improvements in energy storage and power-to-weight ratios. High-capacity batteries and lightweight materials support the development of aircraft capable of carrying passengers over regional distances without compromising safety or performance. Research institutions and private companies are working to optimize energy systems for efficient propulsion and minimal downtime. It supports longer operational ranges and faster turnaround times, critical for commercial viability. These advancements are setting the stage for scalable hybrid solutions across different aircraft sizes and mission profiles.
- RTX, for instance, installed a Collins Aerospace component into a 1-megawatt (MW) hybrid-electric demonstrator engine in June 2023, designed to reduce carbon dioxide emissions by 30% compared to current regional turboprop aircraft.
Growing Focus on Regional and Urban Air Mobility is Driving Adoption
The demand for cost-effective and low-emission air travel within cities and regional areas is increasing. The hybrid aircraft market aligns with this trend, offering the flexibility and efficiency needed for short-haul operations. Hybrid-electric models can utilize smaller airports and new vertiport infrastructure, reducing congestion at major hubs. It enables quieter takeoffs and landings, a crucial factor in urban environments where noise regulations are stringent. Operators are exploring new business models such as on-demand air taxi services, which rely on aircraft with lower operating costs and sustainable propulsion. Hybrid configurations provide a bridge toward fully electric aviation while addressing current technological constraints.
Supportive Policy Frameworks and Public-Private Investments are Fostering Market Growth
Governments around the world are supporting green aviation through subsidies, tax incentives, and innovation grants. The hybrid aircraft market is attracting significant funding from both public institutions and private investors eager to capitalize on the shift to sustainable aviation. Regulatory clarity around hybrid-electric certification and airworthiness is evolving, offering a clear pathway for manufacturers to commercialize their platforms. Infrastructure planning is also progressing, with emphasis on power grid integration, maintenance ecosystems, and pilot training for hybrid systems. It helps de-risk investments and accelerates deployment timelines. Collaboration among aerospace firms, technology providers, and mobility platforms further strengthens the development and adoption of hybrid aircraft.
Market Trends:
Emergence of Hybrid-Electric Propulsion as a Transition Technology
Hybrid-electric propulsion is gaining traction as a practical bridge between conventional jet engines and fully electric systems. The hybrid aircraft market reflects this trend, with manufacturers integrating dual power sources to improve efficiency while maintaining operational range. This approach allows aircraft to switch between electric and combustion engines depending on flight phase, optimizing fuel usage. It also reduces emissions during takeoff and landing, supporting compliance with environmental regulations. Developers are focused on scalable hybrid architectures that can be adapted for both fixed-wing aircraft and vertical take-off and landing (VTOL) vehicles. This transitional model enables quicker adoption without waiting for breakthroughs in battery technology.
- For example, Ampaire Inc. has successfully demonstrated its hybrid-electric propulsion technology in flight trials using a modified Cessna 337, achieving significant reductions in fuel consumption and emissions compared to traditional propulsion.
Development of Regional Hybrid Aircraft for Short-Haul Connectivity
Manufacturers are targeting regional air mobility with aircraft designed for short-to-medium range travel. The hybrid aircraft market is expanding through prototypes tailored for routes under 1,000 kilometers, where hybrid propulsion offers cost and environmental advantages. These aircraft are ideal for linking remote regions, secondary cities, and island networks that lack efficient transport alternatives. It provides operators with a viable solution to meet growing regional demand while keeping operational expenses in check. Companies are designing models with 9 to 50 seats, creating a new category of commuter aircraft that can replace older turboprops. This shift is opening new business opportunities for regional carriers and charter services.
Increasing Involvement of Major Aerospace Players and Startups
Leading aerospace companies are entering the hybrid aircraft market alongside agile startups. Large firms bring experience in certification, manufacturing, and integration, while startups contribute innovation and speed to market. This dual-force is accelerating the pace of development and producing varied concepts across size and use cases. It strengthens the supply chain, encourages collaborative research, and helps de-risk commercialization. Strategic partnerships are forming between airframe manufacturers, battery developers, and software providers to deliver integrated solutions. The competitive landscape is evolving rapidly, with test flights, funding rounds, and concept unveilings becoming more frequent.
- Airbus, for example, has conducted test flights of its E-Fan X hybrid demonstrator, which integrates a 2 MW electric motor alongside traditional gas turbines. These collaborations accelerate the pace of development and produce varied concepts across size and use cases.
Focus on Noise Reduction and Airport Compatibility for Urban Use
Designers are prioritizing noise reduction to meet the requirements of urban air mobility and community acceptance. The hybrid aircraft market is aligning with this need by offering propulsion systems that generate less acoustic disturbance than traditional engines. Quiet operations enable aircraft to access suburban and metropolitan areas with stringent noise controls. It also enhances the passenger experience and broadens use cases for intra-city travel. Airports and vertiport developers are adapting ground infrastructure to accommodate quieter, hybrid models with different fueling and charging needs. These considerations are shaping future certification standards and influencing aircraft configurations.
Market Challenges Analysis:
Technical Limitations and Infrastructure Readiness Are Slowing Adoption
The hybrid aircraft market faces delays due to unresolved technical constraints, particularly in energy storage, weight optimization, and thermal management. Battery energy density remains insufficient for long-range operations, limiting aircraft performance and payload capacity. Power systems must balance safety, redundancy, and efficiency while integrating with traditional engines. It requires extensive testing and certification, prolonging development timelines and raising costs. Ground infrastructure also lacks standardization for hybrid propulsion, with many airports unprepared to support charging, maintenance, or operational needs. These gaps hinder scalability and complicate early-stage deployment for commercial operators.
- For instance, Ampaire’s Electric EEL demonstrator has highlighted that current battery energy densities (typically around 250 Wh/kg for commercial lithium-ion cells) are insufficient for long-range operations, limiting aircraft performance and payload capacity.
Regulatory Complexity and High Development Costs Pose Financial Risks
The absence of comprehensive regulatory frameworks for hybrid propulsion adds uncertainty to certification and commercialization. The hybrid aircraft market must navigate evolving airworthiness standards, which differ by region and are still under development. Manufacturers must invest heavily in research, prototyping, and compliance, often without clear timelines for return on investment. It increases financial pressure, especially on smaller firms and startups competing with established players. Insurance, pilot training, and safety protocols for hybrid systems also lack uniform guidelines, further complicating market entry. Investors remain cautious, slowing the pace of funding and delaying full-scale production.
Market Opportunities:
The rise of regional air mobility offers strong commercial opportunities for hybrid aircraft, especially in underserved areas with limited ground connectivity. The hybrid aircraft market can address transportation gaps in remote regions, island chains, and secondary cities by providing low-emission, short-haul options. Operators can deploy these aircraft to establish new routes that are not economically viable for traditional jets. It enables flexible scheduling, faster turnaround times, and lower operational costs. Governments and local authorities are exploring air mobility initiatives, creating favorable conditions for early adoption. This shift supports fleet diversification and market expansion.
Partnerships between aerospace companies, battery manufacturers, and infrastructure providers are opening new pathways for innovation and market entry. The hybrid aircraft market benefits from public-private initiatives that support sustainable aviation through grants, research incentives, and demonstration programs. It reduces the financial burden on developers while validating new technologies through pilot projects. Governments are prioritizing green transport, aligning regulatory and funding support with hybrid propulsion goals. These collaborations enhance technical capabilities and market readiness. Early alignment with policy frameworks creates momentum for commercialization.
Market Segmentation Analysis:
The hybrid aircraft market is evolving across several technical and operational segments, reflecting diverse deployment scenarios.
By fuel type, fuel hybrids dominate current deployments due to existing infrastructure compatibility, while hydrogen hybrids are gaining traction as cleaner alternatives backed by decarbonization targets.
By lift technology, vertical take-off and landing (VTOL) platforms are drawing significant interest for urban air mobility, while CTOL and STOL aircraft remain essential for regional transport and remote access.
By aircraft type, regional transport aircraft hold a significant share due to increasing demand for low-emission connectivity between cities. Business jets and light aircraft are leveraging hybrid systems for range extension and cost reduction, while advanced air mobility platforms are emerging with hybrid propulsion for short-distance urban transit. The hybrid aircraft market spans both manned and unmanned modes of operation, with unmanned aircraft contributing to defense and logistics missions.
By range, the 101–500 km segment accounts for the largest share, aligning with regional and commuter routes. Aircraft with under 100 km range target intra-city mobility, while those exceeding 501 km aim to serve intercity and cross-border routes.
By application, the commercial segment leads in adoption, driven by airline interest in fuel savings and emission control. Military and civil applications follow, where hybrid systems enhance operational flexibility and sustainability.
Segmentation:
By Fuel Type
- Fuel hybrid
- Hydrogen hybrid
By Lift Technology
- Conventional Take-Off and Landing (CTOL)
- Short Take-Off and Landing (STOL)
- Vertical Take-Off and Landing (VTOL)
By Aircraft Type
- Regional Transport Aircraft
- Business Jets and Light Aircraft
- Advanced Air Mobility
By Mode of Operation
- Manned Aircraft
- Unmanned Aircraft
By Range
- 100 km
- 101 km to 500 km
- > 501 km
By Application
- Commercial
- Military
- Civil
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America dominates the hybrid aircraft market with a share of 42% in 2024. Strong R&D capabilities, early-stage investments, and government-backed sustainability goals drive regional growth. The United States leads with multiple test programs and prototype launches from both established aerospace firms and startups. It benefits from a robust aviation infrastructure, defense sector involvement, and active support from agencies such as NASA and the FAA. Canada also contributes through cross-border collaborations and clean aviation initiatives. The presence of large-scale technology providers accelerates the development of power systems and integration platforms.
Europe holds the second-largest share in the hybrid aircraft market, accounting for 33% in 2024. The region is positioning itself as a global leader in sustainable aviation, supported by the European Union’s Green Deal and funding from programs like Clean Aviation and Horizon Europe. Leading aerospace manufacturers in Germany, France, and the UK are actively developing hybrid-electric platforms for both commercial and defense applications. It reflects strong policy alignment, R&D investment, and environmental compliance standards. Regional air mobility projects across Scandinavia and Southern Europe are also fostering early-stage adoption. Public awareness of carbon emissions and climate targets continues to drive interest in hybrid propulsion technologies.
Asia-Pacific represents 18% of the global market share in 2024 and is expected to witness the fastest growth through 2032. Rising urbanization, increasing demand for air connectivity, and government initiatives to modernize aviation infrastructure contribute to the region’s momentum. China and Japan are investing in hybrid aircraft as part of broader national strategies for low-emission transport and smart city development. It creates significant opportunities for local manufacturers, component suppliers, and technology partners. India and South Korea are also exploring hybrid aviation to improve regional transport accessibility. The market shows strong potential as infrastructure and regulatory frameworks evolve to support hybrid aviation across diverse terrains.
Key Player Analysis:
- Airbus SE
- Ampaire Inc.
- Embraer S.A.
- Faradair Aerospace
- General Electric Company
- Heart Aerospace
- Pipistrel
- Rolls-Royce Holdings plc.
- RTX Corporation
- Safran S.A.
- Textron Inc.
Competitive Analysis:
The hybrid aircraft market features a mix of established aerospace companies and emerging startups competing to lead the shift toward sustainable aviation. Major players such as Airbus, Boeing, and Rolls-Royce are advancing hybrid-electric propulsion through large-scale R&D and strategic collaborations. It reflects their long-term commitment to reducing emissions while maintaining performance. Startups like Ampaire, Eviation, and Zunum Aero are focusing on small and mid-sized aircraft, introducing disruptive technologies with faster innovation cycles. The competitive landscape is evolving rapidly, with companies racing to achieve flight certifications, secure funding, and establish partnerships. Technological differentiation, regulatory readiness, and time-to-market are key success factors. The market remains dynamic, with alliances across battery technology, avionics, and electric power systems shaping future development. Competitive intensity is expected to increase as governments align policy support with clean aviation goals, attracting further investment and accelerating commercialization.
Recent Developments:
- In Oct 2022, ZeroAvia completed the acquisition of HyPoint, a leading provider of hydrogen fuel cell technology for aviation.This acquisition is set to accelerate ZeroAvia’s efforts to bring hybrid-hydrogen propulsion systems to market, with a focus on regional and commuter aircraft. The integration of HyPoint’s technology is expected to enhance the range and efficiency of ZeroAvia’s hybrid aircraft offerings.
- Manta Aircraft displayed its ANN 6 hybrid-electric aircraft at the China Airshow in Zhuhai in December 2024. The aircraft is a 6-seat HeV/STOL (Hybrid-electric Vertical/Short Takeoff and Landing) designed for both urban air mobility and regional travel. The ANN 6 uses a hybrid-electric propulsion system with electric motors and a fuel-based generator, offering ranges of over 1,000 km in STOL mode and up to 300 km in VTOL operations. The presentation at the Airshow received positive attention from international audiences and industry experts
- In November 2023, Electra successfully completed its first flights of the EL-2 Goldfinch, a hybrid-electric aircraft designed for ultra-short takeoff and landing (eSTOL). The company conducted both fully electric and hybrid-electric test flights at Manassas Regional Airport in Virginia. On November 19th, the hybrid-electric flight reached an altitude of 3,200 feet, traveled about 30 miles, and lasted 23 minutes. Electra plans to continue developing the aircraft's capabilities.
Market Concentration & Characteristics:
The hybrid aircraft market remains moderately concentrated, with a few major players holding significant technological and financial advantages. It is characterized by high entry barriers due to strict regulatory requirements, capital-intensive R&D, and complex certification processes. Leading aerospace firms dominate large-scale development, while smaller innovators target niche segments with agile, low-capacity solutions. The market emphasizes long development cycles, strong intellectual property protections, and cross-industry collaboration. Rapid advancements in battery technology, electric propulsion, and lightweight materials are influencing product differentiation. Strategic partnerships between traditional aviation companies and tech startups continue to shape the competitive dynamics and innovation pace.
Report Coverage:
The research report offers an in-depth analysis based on Fuel Type, Lift Technology, Aircraft Type, Mode of Operation, Range and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Hybrid aircraft will play a central role in achieving global aviation decarbonization targets.
- Advancements in battery energy density and thermal management will extend aircraft range and efficiency.
- Regional and urban air mobility sectors will increasingly adopt hybrid propulsion for short-haul routes.
- Government-backed funding and regulatory frameworks will accelerate prototype development and certification.
- Market adoption will expand from light aircraft to larger commercial and cargo platforms.
- Strategic collaborations between aerospace, energy, and tech firms will drive integrated system innovation.
- Infrastructure upgrades at regional airports and vertiports will support hybrid aircraft operations.
- Consumer demand for low-emission travel options will influence airline fleet strategies.
- Hybrid-electric retrofits of existing aircraft models will create new aftermarket opportunities.
- Asia-Pacific will emerge as a high-growth region, supported by urbanization and public investment.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Escalating Demand for Short-Haul, Low-Emission Air Travel
Urbanization and the need for efficient regional connectivity are driving airlines and operators to adopt hybrid aircraft, which offer cost-effective and environmentally friendly solutions for short-haul routes.
Technological Advancements in Battery and Electric Propulsion
Improvements in battery energy density, electric motors, and power management systems are making hybrid aircraft more viable, enabling longer ranges, better performance, and reduced operational costs.
Stringent Global Emissions Regulations
International and regional policies targeting net-zero carbon emissions by 2050 are compelling manufacturers and airlines to invest in hybrid propulsion technologies to comply with stricter environmental standards.
Government Support and Public-Private Investments
Subsidies, grants, and innovation incentives from governments, along with significant private investment, are accelerating research, development, and commercialization of hybrid aircraft platforms.
Emergence of Regional and Urban Air Mobility
The rise of new air mobility concepts, such as air taxis and regional commuter services, is creating demand for hybrid aircraft that can operate efficiently from smaller airports and vertiports, especially in congested or underserved areas.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Hybrid Aircraft Market?
What factors are driving the growth of the Hybrid Aircraft Market?
What are some challenges faced by the Hybrid Aircraft Market?
Who are the major players in the Hybrid Aircraft Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Fuel Type
- 1.2.1 Fuel Hybrid
- 1.2.2 Hydrogen Hybrid
- 1.3 By Application
- 1.3.1 Commercial
- 1.3.2 Military
- 1.3.3 Civil
- 1.4 By Aircraft Type
- 1.4.1 Regional Transport Aircraft
- 1.4.2 Business Jets and Light Aircraft
- 1.4.3 Advanced Air Mobility
- 1.5 By Lift Technology
- 1.5.1 Conventional Take-Off and Landing (CTOL)
- 1.5.2 Short Take-Off and Landing (STOL)
- 1.5.3 Vertical Take-Off and Landing (VTOL)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,836.54 million → 2032: USD 40,585.83 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hybrid Aircraft Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hybrid Aircraft Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hybrid Aircraft Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hybrid Aircraft Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hybrid Aircraft Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hybrid Aircraft Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hybrid Aircraft Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hybrid Aircraft Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,836.54 million → 2032: USD 40,585.83 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hybrid Aircraft Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Fuel Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fuel Hybrid
- 12.3.7.2 Hydrogen Hybrid
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Commercial
- 12.4.7.2 Military
- 12.4.7.3 Civil
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Aircraft Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Regional Transport Aircraft
- 12.5.7.2 Business Jets and Light Aircraft
- 12.5.7.3 Advanced Air Mobility
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Lift Technology - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Conventional Take-Off and Landing (CTOL)
- 12.6.7.2 Short Take-Off and Landing (STOL)
- 12.6.7.3 Vertical Take-Off and Landing (VTOL)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hybrid Aircraft End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Hybrid Aircraft Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Hybrid Aircraft Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Hybrid Aircraft Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Airbus SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ampaire Inc.
- 18.4 Embraer S.A.
- 18.5 Faradair Aerospace
- 18.6 General Electric Company
- 18.7 Heart Aerospace
- 18.8 Pipistrel
- 18.9 Rolls-Royce Holdings plc
- 18.10 RTX Corporation
- 18.11 Safran S.A.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

