
Market Overview
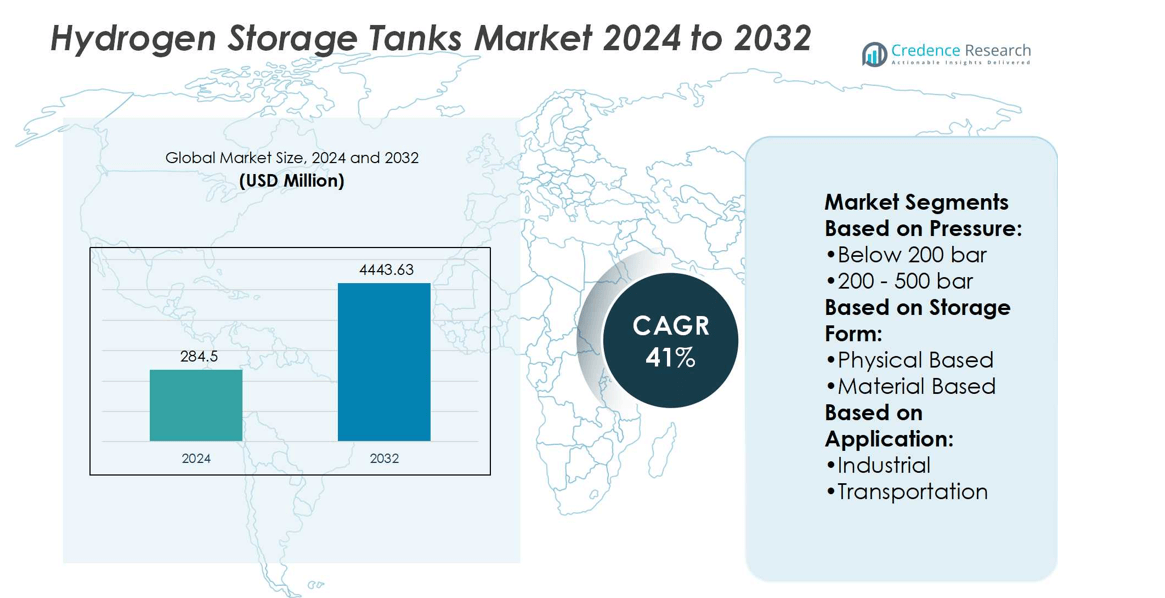
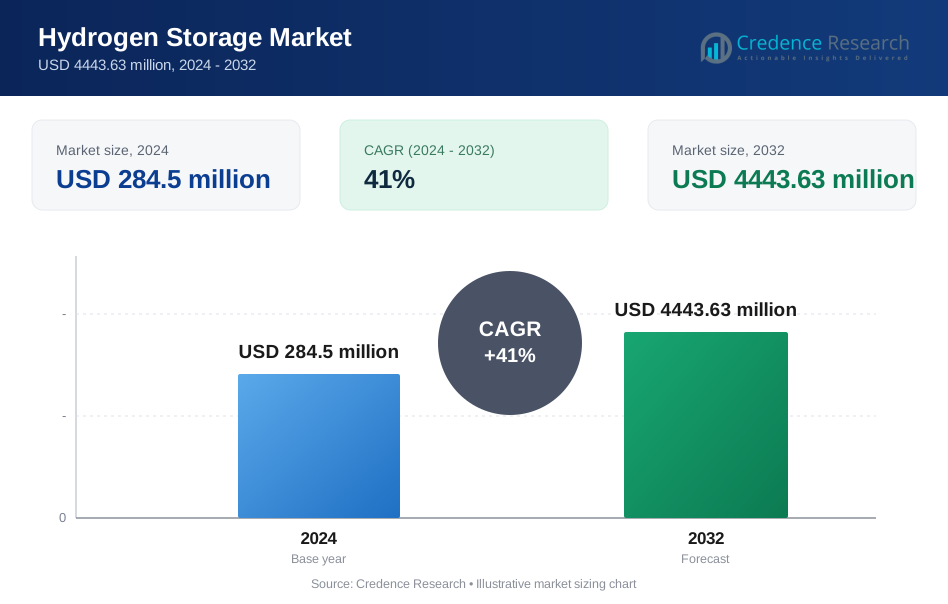
Hydrogen Storage Tanks Market size was valued at USD 284.5 million in 2024 and is anticipated to reach USD 4443.63 million by 2032, at a CAGR of 41% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hydrogen Storage Tanks Market Size 2024 | USD 284.5 million |
| Hydrogen Storage Tanks Market, CAGR | 41% |
| Hydrogen Storage Tanks Market Size 2032 | USD 4443.63 million |
The Hydrogen Storage Tanks Market grows through strong government support, rising investments in clean energy, and expanding adoption across industrial and transportation sectors. Demand increases as high-pressure systems above 500 bar enable longer ranges and faster refueling for fuel cell vehicles, railways, and marine applications. Lightweight composite materials and advanced polymers drive innovation, reducing weight while improving durability and safety. Digital monitoring, IoT-enabled systems, and predictive analytics enhance reliability and compliance with strict regulations. Expanding hydrogen corridors, renewable integration, and cross-border trade projects further strengthen market momentum, positioning storage tanks as a vital element in global decarbonization strategies.
The Hydrogen Storage Tanks Market shows strong geographical presence with Asia Pacific holding the largest share, driven by large-scale hydrogen adoption in mobility and industry. Europe follows with strict emission regulations and cross-border projects, while North America advances through hydrogen hubs and mobility pilots. Latin America and the Middle East & Africa record emerging opportunities supported by renewable projects and industrial demand. Key players include BayoTech, NPROXX, Hexagon Purus, Luxfer Gas Cylinders, Plastic Omnium, Mahytec, Doosan Mobility Innovation, ECS, Hensoldt, and Pragma Industries.
Market Insights
- Hydrogen Storage Tanks Market size was USD 284.5 million in 2024 and will reach USD 4443.63 million by 2032, at a CAGR of 41%.
- Strong government support and rising clean energy investments drive adoption across industrial and mobility sectors.
- High-pressure tanks above 500 bar gain demand for longer ranges and faster refueling in transport.
- Lightweight composites and advanced polymers reduce weight while improving durability and safety.
- Key players focus on innovation, partnerships, and advanced designs to strengthen competitiveness.
- High production costs and infrastructure gaps act as restraints for wider adoption.
- Asia Pacific leads the market, followed by Europe and North America, with Latin America and Middle East & Africa emerging.
Market Drivers
Rising Investments in Clean Energy Infrastructure and Decarbonization Efforts
The Hydrogen Storage Tanks Market benefits from major investments in clean energy projects and national hydrogen strategies. Governments promote hydrogen hubs, corridors, and large-scale industrial projects to accelerate decarbonization goals. These initiatives create consistent demand for storage systems that ensure safe, efficient, and scalable solutions. It supports renewable integration and strengthens hydrogen’s role as an energy carrier across industries. Fuel cell vehicles and industrial users drive procurement of advanced storage tanks. This alignment with global sustainability policies secures long-term growth opportunities.
- For instance, companies like Hexagon Purus and NPROXX produce Type IV hydrogen tanks certified for up to 700 bar pressure, enabling deployment in fuel cell buses across Europe. These tanks, which weigh significantly less than steel alternatives, are integrated into vehicles to ensure safe onboard hydrogen storage.
Advancements in High-Pressure and Lightweight Composite Technologies
Technological progress remains a strong driver for the Hydrogen Storage Tanks Market. Manufacturers develop high-pressure systems above 500 bar that extend driving range and cut refueling times. Lightweight composite tanks reduce overall vehicle weight, enhancing fuel efficiency and operational safety. It enables automakers and transport operators to deploy hydrogen solutions at scale. Research into durable polymers and carbon fiber reinforcements further increases lifespan and reliability. These innovations strengthen adoption in mobility and industrial applications.
- For instance, Plastic Omnium has developed Type IV hydrogen storage tanks capable of 700 bar pressure, with carbon fiber windings that reduce weight by 30%, and its facility in Brussels now produces more than 80,000 high-pressure tanks annually for mobility applications.
Expanding Adoption Across Transportation, Industry, and Power Generation
The Hydrogen Storage Tanks Market records strong demand from automotive, railway, marine, and stationary power sectors. Fuel cell vehicles require reliable high-pressure tanks to meet performance expectations. Industries such as steel, chemicals, and refineries utilize hydrogen storage for process efficiency and emission reduction. It also plays a role in backup power generation, supporting energy resilience for critical infrastructure. Marine and rail transport adopt hydrogen solutions to comply with emission regulations. This multi-sector integration enhances market stability.
Growing Emphasis on Safety Standards and Smart Monitoring Systems
Strict regulatory frameworks push the Hydrogen Storage Tanks Market toward safer and smarter solutions. Governments enforce certification standards for pressure ratings, leak-proof designs, and durability testing. It drives companies to integrate digital sensors, predictive analytics, and IoT-based monitoring systems. Real-time diagnostics reduce risks while improving operational performance. Industry partnerships focus on developing globally harmonized standards for storage and transport. These measures improve trust and accelerate broader market adoption.
Market Trends
Increasing Integration of Hydrogen Storage with Mobility and Transportation Networks
The Hydrogen Storage Tanks Market shows strong momentum in mobility adoption across vehicles, railways, and marine fleets. Fuel cell cars and buses demand advanced high-pressure storage systems that support long ranges and fast refueling. Railway operators integrate hydrogen-powered locomotives on regional routes to reduce emissions and meet policy targets. It creates steady demand for tanks capable of withstanding frequent operational cycles. Marine industries explore hydrogen storage solutions for ferries and cargo vessels under strict emission rules. This transport integration strengthens hydrogen’s role in the global energy transition.
- For instance, BayoTech hydrogen generation system (H2-1000) produces up to 1,000 kilograms of hydrogen per day, their transport modules (like the GSM30-250) hold significantly smaller amounts, enabling efficient hydrogen delivery to end-users.
Advancements in Digital Monitoring and Smart Safety Features
Technology integration marks a vital trend in the Hydrogen Storage Tanks Market. Companies deploy IoT-enabled sensors that track pressure, temperature, and leakage in real time. Predictive analytics tools provide early warnings, minimizing downtime and enhancing reliability. It supports compliance with evolving safety standards and boosts operational trust among users. Digital monitoring also enables remote management for large-scale industrial projects. These innovations redefine performance expectations and drive long-term market confidence.
- For instance, Pragma Mobility developed the Alpha Neo fuel cell e-bike, which uses a removable hydrogen pack with 67 grams of hydrogen at 300 bar. This provides an energy capacity of 1,200 Wh (1.2 kWh), enabling a range of up to 150 kilometers.
Rising Use of Lightweight Materials and Composite Innovations
Material innovation continues to influence the Hydrogen Storage Tanks Market. Carbon fiber composites replace traditional steel, reducing tank weight while maintaining high-pressure resistance. This shift improves fuel efficiency in vehicles and lowers handling costs for industrial users. It also extends product lifespan, reducing replacement frequency and overall operating costs. Manufacturers focus on advanced resin systems and polymer blends for added durability. These material improvements make storage solutions more adaptable across applications.
Expansion of Hydrogen Infrastructure and Cross-Border Trade Projects
Infrastructure growth stands as a defining trend for the Hydrogen Storage Tanks Market. Governments and private players invest in hydrogen refueling stations, pipelines, and cross-border corridors. It ensures reliable supply for both mobility and industrial sectors. Large-scale trade agreements support storage solutions that enable secure transport across regions. Energy hubs in Asia, Europe, and North America prioritize tank deployment for long-haul logistics. This infrastructure expansion strengthens global supply chains and accelerates adoption.
Market Challenges Analysis
High Production Costs and Limited Economies of Scale Restrict Wider Deployment
The Hydrogen Storage Tanks Market faces significant challenges due to high manufacturing costs and complex material requirements. Advanced composite tanks demand carbon fiber and specialized polymers, which raise production expenses. Limited economies of scale prevent cost reductions, making hydrogen systems less competitive against conventional energy solutions. It creates barriers for adoption in cost-sensitive industries such as public transport and small-scale manufacturing. Procurement budgets in emerging economies often struggle to support large-scale deployment. This cost challenge continues to restrict faster commercialization and wider market penetration.
Infrastructure Gaps, Safety Concerns, and Regulatory Barriers Slow Adoption
Infrastructure limitations remain a critical hurdle for the Hydrogen Storage Tanks Market. Refueling stations and transport corridors are still underdeveloped in many regions, creating bottlenecks in distribution. It slows adoption in mobility sectors that require reliable access to hydrogen supply networks. Safety concerns around high-pressure storage, risk of leakage, and accident prevention demand strict compliance with standards. Regulatory fragmentation across countries complicates certification, testing, and cross-border trade. These factors raise operational risks and slow the global scaling of hydrogen storage solutions.
Market Opportunities
Expansion into Emerging Economies and Growing Renewable Integration
The Hydrogen Storage Tanks Market presents strong opportunities in emerging economies investing in clean energy transitions. Countries in Asia, Latin America, and the Middle East expand hydrogen corridors to support industrial and mobility applications. It enables storage solutions to become integral to renewable integration, ensuring stable supply from solar and wind projects. Governments provide funding and policy support for infrastructure that favors tank adoption. Local manufacturing and technology transfer create further opportunities for cost reduction. This expansion into new markets increases demand for scalable and reliable storage systems.
Advancements in Mobility Applications and Long-Distance Transport Solutions
Rapid innovation in mobility and logistics creates opportunities for the Hydrogen Storage Tanks Market. Automakers invest in fuel cell vehicles that require durable high-pressure tanks to meet performance standards. It supports extended ranges for buses, trucks, and trains, boosting adoption across transportation fleets. Marine and aviation sectors explore hydrogen storage for long-distance routes, creating demand for advanced tank designs. Industrial logistics and cross-border trade benefit from high-capacity storage solutions that enable safe bulk transport. These advancements broaden hydrogen’s role in global decarbonization strategies and open new commercial prospects.
Market Segmentation Analysis:
By Pressure
The Hydrogen Storage Tanks Market divides into below 200 bar, 200–500 bar, and above 500 bar categories. Tanks below 200 bar serve stationary and low-pressure applications, including backup systems and small-scale industrial operations. The 200–500 bar range dominates mid-level adoption, balancing safety, energy density, and affordability. It remains widely used in industrial sectors where performance reliability and operational efficiency are priorities. Above 500 bar tanks gain momentum in advanced transportation, supporting longer ranges and reduced refueling time for fuel cell vehicles, railways, and marine uses. This high-pressure category attracts strong investment from mobility stakeholders seeking scalable solutions.
- For instance, Luxfer Gas Cylinders manufactures Type III and Type IV hydrogen tanks certified for up to 700 bar, with individual cylinders holding smaller amounts of hydrogen and bundles of cylinders storing up to 84 kilograms.
By Storage Form
The Hydrogen Storage Tanks Market segments into physical-based and material-based storage forms. Physical storage, including compressed and cryogenic methods, is the most established and widely deployed option. It supports applications in both industrial and transportation sectors with proven reliability. Material-based storage, such as metal hydrides and chemical carriers, is under development for enhanced safety and compactness. It offers potential advantages in weight reduction and energy density, addressing future mobility requirements. Research partnerships and pilot projects drive innovation in this segment, aiming for commercial readiness.
- For instance, Doosan Mobility Innovation's hydrogen fuel cell drones use 350 bar composite storage tanks with capacities of either 7 liters or 10.8 liters, enabling flight times of up to 120 minutes.
By Application
The Hydrogen Storage Tanks Market addresses two primary application categories: industrial and transportation. Industrial users adopt storage systems for chemical production, steelmaking, refineries, and power generation. It ensures hydrogen supply stability for processes where decarbonization remains a priority. Transportation applications drive rapid adoption through fuel cell vehicles, buses, trucks, and trains requiring advanced tanks for performance consistency. Marine and aviation sectors explore new storage technologies to meet global emission targets. This application diversity enhances market resilience and strengthens growth potential.
Segments:
Based on Pressure:
- Below 200 bar
- 200 - 500 bar
Based on Storage Form:
- Physical Based
- Material Based
Based on Application:
- Industrial
- Transportation
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America accounts for 18% of the Hydrogen Storage Tanks Market, with the United States and Canada at the forefront. Federal and state initiatives promote hydrogen hubs, mobility pilots, and industrial decarbonization. The U.S. supports hydrogen in heavy-duty trucking, aviation, and stationary power, creating strong demand for advanced tanks. Canada invests in hydrogen corridors linking major provinces, emphasizing cross-border integration with the U.S. It creates opportunities for high-pressure and cryogenic storage across transportation and industrial sectors. Companies in the region pioneer innovations in carbon fiber composites and safety monitoring systems. This focus on technology development and infrastructure expansion secures steady market growth.
Europe
Europe represents 28% of the Hydrogen Storage Tanks Market, supported by strict emission regulations and cross-border hydrogen trade initiatives. The European Union prioritizes green hydrogen adoption across industries and mobility to meet climate neutrality goals. Germany, France, and the Netherlands lead investment in hydrogen refueling infrastructure and storage innovation. It benefits from advanced R&D in lightweight composite tanks and digital monitoring systems. Regional projects focus on integrating storage with renewable energy hubs, ensuring consistent supply. The growth of hydrogen corridors across borders promotes large-scale adoption of high-capacity storage systems. Europe’s regulatory environment and collaborative projects sustain its strong position.
Asia Pacific
Asia Pacific holds the largest share of the Hydrogen Storage Tanks Market at 40%. The region leads adoption through large-scale hydrogen infrastructure projects in Japan, China, South Korea, and Australia. Governments actively fund hydrogen corridors, fuel cell vehicle deployment, and industrial decarbonization programs. It supports widespread use of high-pressure storage tanks in mobility, energy, and chemical sectors. Japan invests heavily in 700-bar storage for fuel cell cars, while China expands refueling stations across major urban clusters. South Korea develops hydrogen-powered rail and marine systems, further strengthening demand. With strong policy backing and industrial partnerships, Asia Pacific maintains leadership and sets global benchmarks for hydrogen deployment.
Latin America
Latin America holds 8% of the Hydrogen Storage Tanks Market, with growth led by Brazil, Chile, and Argentina. Governments emphasize hydrogen for renewable integration and industrial decarbonization. Chile develops one of the world’s largest green hydrogen initiatives, creating demand for high-capacity storage tanks. Brazil explores hydrogen adoption in transportation and heavy industries, while Argentina pursues pilot projects for clean fuel export. It creates opportunities for both physical-based and material-based storage systems. Infrastructure development remains in early stages, but international partnerships accelerate progress. Latin America’s market share is expected to grow steadily with global energy transition.
Middle East & Africa
The Middle East & Africa region captures 6% of the Hydrogen Storage Tanks Market. Countries such as Saudi Arabia, the UAE, and South Africa invest in large-scale green hydrogen projects. It supports demand for storage tanks in both industrial applications and export-oriented projects. Saudi Arabia develops NEOM, one of the largest hydrogen hubs, requiring advanced tank deployment for global trade. The UAE focuses on hydrogen in power generation and mobility, with South Africa targeting industrial and mining applications. Limited infrastructure poses challenges, yet strong investment momentum drives growth. International collaborations enhance the region’s role in future hydrogen supply chains.
Key Player Analysis
- ECS
- Plastic Omnium
- BayoTech
- Hensoldt
- Pragma Industries
- Luxfer Gas Cylinders
- Doosan Mobility Innovation
- Hexagon Purus
- Mahytec
- NPROXX
Competitive Analysis
The Hydrogen Storage Tanks Market players including BayoTech, Doosan Mobility Innovation, ECS, Hensoldt, Hexagon Purus, Luxfer Gas Cylinders, Mahytec, NPROXX, Plastic Omnium, and Pragma Industries. The Hydrogen Storage Tanks Market demonstrates a highly competitive landscape driven by innovation, regulatory compliance, and global energy transition goals. Companies emphasize advancements in high-pressure systems, lightweight composite materials, and digital monitoring solutions to strengthen performance and safety. Strategic partnerships with automakers, energy providers, and infrastructure developers support large-scale deployment across transportation, industrial, and power sectors. It benefits from rising investment in hydrogen corridors, mobility projects, and renewable integration, which increase demand for reliable storage systems. Continuous research into material efficiency and durability ensures long-term market growth. Competition focuses on delivering scalable, cost-effective, and technologically advanced solutions that align with evolving sustainability targets.
Recent Developments
- In November 2024, Hexagon Purus was once again selected by New Flyer to provide hydrogen cylinders for North America's zero-emission transit buses. Hexagon Purus will deliver its Type 4 hydrogen storage cylinders for use in the transit buses, which can travel up to 600 kilometers on a single refueling.
- In October 2024, Celly and UMOE Advanced Composites AS introduced an advanced hydrogen transportation trailer to the U.S. market. Designed to safely and efficiently transport large volumes of hydrogen, this trailer builds on UMOE's successful six-year track record in Europe.
- In October 2024, Tenaris reaffirmed its role in advancing hydrogen transportation research by participating in the Hydrogenius Symposium and the HyLINE II JIP. Following the symposium, Tenaris joined the HyLINE II JIP, a five-year initiative focusing on the material integrity of welded joints in offshore hydrogen pipelines, collaborating with key industrial partners.
- In April 2024, NPROXX displayed its hydrogen storage solutions at Hannover Messe, demonstrating advanced technologies like lightweight composite tanks. The company highlighted its role in promoting hydrogen adoption across various sectors, engaging with industry leaders to foster collaboration.
Report Coverage
The research report offers an in-depth analysis based on Pressure, Storage Form, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for high-pressure tanks above 500 bar will rise with fuel cell vehicle expansion.
- Lightweight composite materials will gain preference to improve efficiency and durability.
- Hydrogen corridors and refueling infrastructure will drive adoption across global regions.
- Digital monitoring and IoT-based systems will become standard for safety and reliability.
- Industrial users in steel, chemicals, and refineries will expand hydrogen storage investments.
- Marine and rail transport sectors will adopt advanced storage systems to meet emission targets.
- Material-based storage solutions will progress toward commercial readiness in niche applications.
- Strategic partnerships will increase between technology providers, automakers, and energy companies.
- Government policies and subsidies will continue to accelerate large-scale storage deployment.
- Global trade networks will expand, requiring advanced storage systems for cross-border hydrogen transport.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Strong Government Support and Clean Energy Investments
National hydrogen strategies and government funding for hydrogen hubs, corridors, and decarbonization projects are driving consistent demand for advanced storage tanks, ensuring safe and scalable hydrogen supply for industrial and mobility sectors.
Advancements in High-Pressure and Lightweight Composite Technologies
Innovations in high-pressure storage (above 500 bar) and lightweight composite materials are enabling longer ranges, faster refueling, and improved safety for fuel cell vehicles, railways, and marine applications, accelerating adoption across transportation and industry.
Expansion of Hydrogen Infrastructure and Cross-Border Trade
The development of hydrogen refueling stations, pipelines, and cross-border corridors is strengthening supply chains and enabling large-scale deployment of storage tanks, supporting both domestic use and international hydrogen trade.
Rising Adoption Across Transportation and Industrial Sectors
Fuel cell vehicles, buses, trains, and marine vessels, as well as industrial users in steel, chemicals, and refineries, are increasingly adopting hydrogen storage tanks to meet emission targets and improve operational efficiency.
Emphasis on Safety Standards and Digital Monitoring
Strict regulatory frameworks and the integration of IoT-enabled monitoring systems are enhancing the safety, reliability, and compliance of hydrogen storage tanks, building trust and supporting broader market adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Hydrogen Storage Tanks Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Hydrogen Storage Tanks Market projected to grow between 2025 and 2032?
Which Hydrogen Storage Tanks Market segment held the largest share in 2024?
Which regions are leading in the Hydrogen Storage Market?
What innovations are influencing the market?
How is government support impacting the Hydrogen Storage Market?
Who are the leading companies in the Hydrogen Storage Tanks Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Pressure
- 1.2.1 Below 200 bar
- 1.2.2 200 - 500 bar
- 1.2.3 Above 500 bar
- 1.3 By Application
- 1.3.1 Industrial
- 1.3.2 Transportation
- 1.4 By Storage Form
- 1.4.1 Physical Based
- 1.4.2 Material Based
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 284.5 million → 2032: USD 4443.63 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hydrogen Storage Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hydrogen Storage Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hydrogen Storage Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hydrogen Storage Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hydrogen Storage Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hydrogen Storage Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hydrogen Storage Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hydrogen Storage Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 284.5 million → 2032: USD 4443.63 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hydrogen Storage Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Pressure - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Below 200 bar
- 12.3.7.2 200 - 500 bar
- 12.3.7.3 Above 500 bar
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Industrial
- 12.4.7.2 Transportation
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Storage Form - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Physical Based
- 12.5.7.2 Material Based
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hydrogen Storage End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Hydrogen Storage Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Hydrogen Storage Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Hydrogen Storage Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Hexagon Purus
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 NPROXX
- 18.4 Luxfer Gas Cylinders
- 18.5 Plastic Omnium
- 18.6 Mahytec
- 18.7 Doosan Mobility Innovation
- 18.8 BayoTech
- 18.9 ECS
- 18.10 Hensoldt
- 18.11 Pragma Industries
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

