
Market Overview:
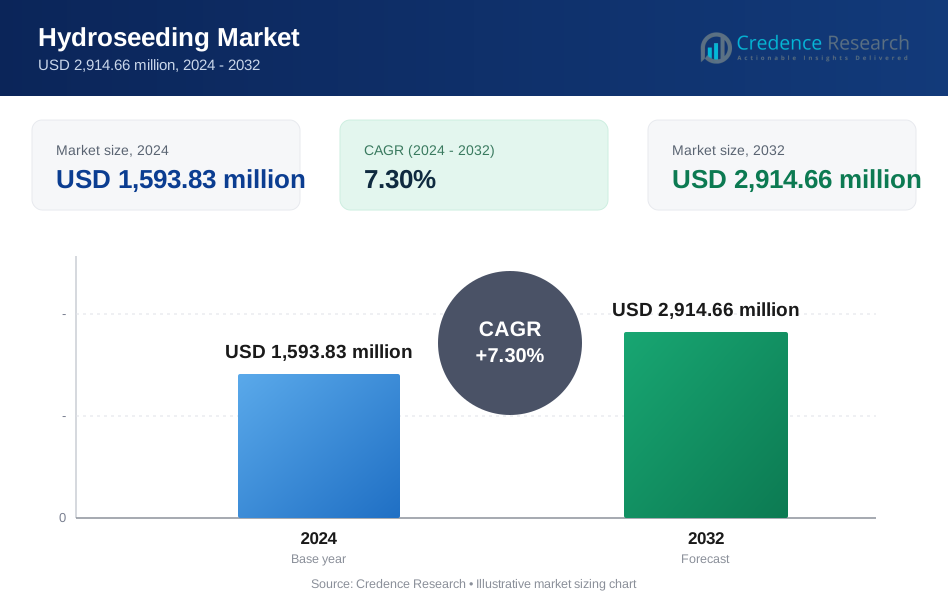
Hydroseeding Market size was valued at USD 1,593.83 million in 2024 and is anticipated to reach USD 2,914.66 million by 2032, at a CAGR of 7.30% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hydroseeding Market Size 2024 | USD 1,593.83 Million |
| Hydroseeding Market, CAGR | 7.30% |
| Hydroseeding Market Size 2032 | USD 2,914.66 Million |
Several key factors are driving the hydroseeding market. The growing need for land reclamation and erosion control in both urban and rural environments is propelling the use of hydroseeding. This technique is increasingly being used for post-construction soil stabilization and landscaping applications. As environmental concerns rise, governments and private sectors are investing in sustainable land rehabilitation projects. In addition, hydroseeding plays a crucial role in reducing water runoff and minimizing soil erosion, which is critical for maintaining soil health. Additionally, the construction industry’s rapid growth, particularly in the development of infrastructure such as highways and residential complexes, is fueling the demand for hydroseeding services for landscaping and green space establishment. Moreover, the benefits of hydroseeding, including faster germination, uniform coverage, and water conservation, make it an attractive alternative to traditional seeding methods. Its cost-effectiveness also contributes to its growing appeal among construction companies.
Geographically, North America dominates the hydroseeding market, accounting for the largest share, owing to a high level of construction activities and land rehabilitation projects. The United States, in particular, is a key market driver due to its ongoing investment in infrastructure development and erosion control measures. The presence of leading hydroseeding service providers further strengthens market growth in this region. Europe is expected to witness substantial growth, driven by increasing environmental regulations and green building initiatives. Several countries in Europe are promoting sustainable urban development and prioritizing green spaces, boosting the demand for hydroseeding services. The Asia Pacific region is also poised for significant growth, attributed to the booming construction industry and expanding agricultural practices. Rapid urbanization and growing infrastructure needs in countries like China and India are expected to drive the adoption of hydroseeding technologies.
Market Insights:
- The hydroseeding market was valued at USD 1,593.83 million in 2024 and is projected to reach USD 2,914.66 million by 2032, growing at a CAGR of 7.30% during the forecast period.
- The growing need for land reclamation and erosion control in both urban and rural environments is a significant driver for the hydroseeding market, with increasing investments in sustainable land rehabilitation.
- Rapid urbanization and the expansion of infrastructure projects are contributing to the demand for hydroseeding, particularly for landscaping and soil stabilization in newly developed residential and commercial properties.
- Hydroseeding offers advantages over traditional seeding methods, such as faster germination, uniform coverage, better water retention, and reduced irrigation needs, driving its adoption in large-scale projects.
- Government regulations and environmental initiatives are encouraging the adoption of hydroseeding as a sustainable solution for land rehabilitation and erosion control, particularly in the construction and agriculture sectors.
- High initial investment costs for specialized equipment and ongoing maintenance pose challenges to small and medium enterprises seeking to enter the hydroseeding market.
- North America holds a dominant 35% share of the market, followed by Europe with a 25% share, and the Asia Pacific region, which accounts for 20%, driven by rapid urbanization and growing construction needs.
Market Drivers:
Increasing Demand for Sustainable Land Rehabilitation and Erosion Control
The growing need for land reclamation and erosion control is driving the hydroseeding market. Governments and industries are investing in sustainable solutions to restore soil health and prevent further environmental degradation. Hydroseeding offers an efficient method for stabilizing soil in areas prone to erosion, such as construction sites, slopes, and roadways. It is gaining popularity in both urban and rural landscapes due to its ability to enhance soil retention and encourage plant growth. This technique is recognized for its contribution to environmental conservation by reducing water runoff and soil erosion in critical areas. It allows for better management of soil in fragile terrains, helping maintain the ecological balance.
Rapid Growth of the Construction and Infrastructure Sectors
The expanding construction and infrastructure sectors significantly contribute to the hydroseeding market. With urbanization increasing globally, there is a greater demand for landscaping and green space development, especially around newly constructed residential and commercial properties. Hydroseeding provides an effective solution for quickly establishing green areas and enhancing aesthetic appeal in urban environments. The growing number of infrastructure projects, including roads, bridges, and highways, requires effective methods for soil stabilization. Hydroseeding offers a practical and cost-efficient alternative to traditional seeding techniques, which is why it is increasingly used in these projects.
- For instance, Sherbrooke Turf hydroseeded over 500 acres along 120 miles of railroad tracks in North Dakota and Montana for a major railroad construction project, stabilizing soil and establishing vegetation in rights-of-way and borrow areas.
Benefits of Hydroseeding Over Traditional Seeding Methods
Hydroseeding presents several advantages over traditional seeding methods, which are driving its market adoption. It allows for faster germination and uniform coverage, ensuring the even establishment of grass or vegetation. Hydroseeding also promotes better water retention and reduces the need for frequent irrigation, making it ideal for drought-prone areas. The cost-effectiveness of this method further enhances its appeal to industries seeking efficient ways to manage large-scale projects. As an environmentally friendly solution, it is gaining traction in sectors where sustainability is a priority. The combination of speed, effectiveness, and cost savings makes it an attractive option for many industries.
- For instance, Erosion Control Services used two T330 Finn HydroSeeders to cover 70 acres on the Dominion Boulevard roadway expansion in Chesapeake, Virginia, applying 13,084 pounds of seed blend to medians, shoulders, and wetland mitigation areas while managing active traffic.
Government Regulations and Environmental Initiatives
Government regulations and environmental initiatives play a significant role in promoting the use of hydroseeding in various industries. Many governments are enacting policies that mandate land rehabilitation and erosion control measures, particularly in construction and mining sectors. These regulations support the adoption of environmentally sustainable practices, including hydroseeding, as a means to comply with growing environmental standards. Hydroseeding contributes to the achievement of green building certifications and other eco-friendly standards, further boosting its demand in markets where sustainability is a priority. This growing regulatory push for environmentally conscious methods strengthens the market's position across multiple regions.
Market Trends:
Rising Adoption of Eco-Friendly and Sustainable Practices
There is an increasing trend toward the adoption of eco-friendly and sustainable practices in various industries, significantly influencing the hydroseeding market. Environmental concerns, including soil erosion, water conservation, and biodiversity preservation, are driving the demand for greener alternatives in land reclamation and landscaping. Hydroseeding provides an efficient and sustainable method of establishing vegetation, particularly in areas where traditional seeding may fail. Its ability to reduce water usage, improve soil structure, and prevent erosion aligns with the growing focus on sustainability. Industries are adopting hydroseeding not only for its effectiveness but also to meet stringent environmental regulations and corporate sustainability goals. This shift towards eco-friendly solutions is expanding hydroseeding’s market presence across multiple sectors.
- For instance, a study by Gorgan University of Agricultural Sciences and Natural Resources found that hydroseed mix 2, which included biohumus and cellulose fibre mulch, significantly reduced irrigation water use and improved grass biomass production on artificial soil slopes over a 30-day period compared to conventional methods.
Technological Advancements in Hydroseeding Equipment
Technological innovations are shaping the hydroseeding market by improving the efficiency and effectiveness of the process. New advancements in hydroseeding equipment, such as automated seeders and precision spraying technology, are increasing the speed and accuracy of applications. These innovations allow for better control over seed distribution, ensuring more uniform coverage and faster establishment of vegetation. Hydroseeding equipment is also becoming more versatile, capable of handling a broader range of soil types and terrains. The integration of data-driven technologies, like GPS mapping and moisture sensors, enables more precise and resource-efficient application, further driving its adoption. These technological advancements make hydroseeding a more attractive option for large-scale and complex projects, contributing to the market’s growth.
- For instance, the Green National Highway Corridors Project in India deployed advanced hydroseeding equipment to cover 781 kilometers of highway corridors, demonstrating the scalability and effectiveness of modern hydroseeding solutions.
Market Challenges Analysis:
High Initial Investment Costs and Equipment Maintenance
One of the significant challenges faced by the hydroseeding market is the high initial investment cost associated with specialized equipment. Hydroseeding requires specialized machines, such as sprayers and mixers, which can be expensive for small and medium enterprises to acquire. These costs, along with the need for regular maintenance and skilled operators, can deter potential adopters. For businesses looking to offer hydroseeding services, the cost of purchasing and maintaining high-quality equipment may be a barrier. This challenge could limit market expansion, especially in regions with fewer infrastructure projects or limited financial resources.
- For instance, Easy Lawn reports that a mid-sized hydroseeder suitable for most residential landscaping projects typically costs around $5,000, but many small landscapers have found that by completing just 5 to 10 jobs, they are able to recoup the initial investment, making the business viable even for newcomers.
Weather Dependency and Environmental Conditions
Hydroseeding’s effectiveness is highly dependent on weather conditions, presenting another challenge for the market. It requires specific temperature and moisture levels to ensure successful germination and growth. In areas prone to extreme weather conditions, such as droughts or heavy rainfall, the success rate of hydroseeding may be compromised. This unpredictability can result in delays or increased costs for project completion. The market must address these weather-related challenges by improving equipment and techniques that can mitigate environmental risks and ensure consistent results, particularly in regions with variable climates.
Market Opportunities:
Expanding Demand in Urban Landscaping and Green Infrastructure
The growing trend of urbanization presents significant opportunities for the hydroseeding market. With more cities focusing on sustainable development and green infrastructure, there is increasing demand for eco-friendly landscaping solutions. Hydroseeding offers an efficient and cost-effective way to establish green spaces in urban areas, such as parks, rooftops, and streetscapes. As municipalities prioritize environmental preservation and green building initiatives, the demand for hydroseeding services is expected to rise. It provides a viable solution for quickly creating aesthetically appealing and sustainable landscapes in urban environments, which supports the broader trend of integrating nature into cities.
Opportunities in Land Rehabilitation and Agriculture
Hydroseeding also presents substantial opportunities in land rehabilitation and agricultural sectors. With rising concerns about soil erosion, desertification, and the need for land restoration, hydroseeding offers a reliable solution for stabilizing and re-vegetating disturbed land. In agriculture, it can be used to improve soil health and prevent further degradation. The increasing focus on sustainable agriculture practices provides a growing market for hydroseeding, especially in regions facing land degradation and erosion. It offers a low-maintenance, efficient alternative for enhancing soil fertility and preventing erosion in agricultural lands, further driving its market adoption.
Market Segmentation Analysis:
By Type
The hydroseeding market is segmented into hydroseeding slurry, hydroseeding equipment, and hydroseeding mulch. Hydroseeding slurry holds the largest share due to its widespread use in large-scale land reclamation, soil stabilization, and landscaping projects. The slurry’s composition of seeds, water, and nutrients ensures even distribution, which drives its demand. Hydroseeding equipment is also gaining traction with technological advancements in sprayers and mixers that improve efficiency, leading to faster and more effective results.
- For instance, the Finn 3,300-gallon hydroseeder can cover approximately 1 acre per tank load using 30 bales of mulch, streamlining large-scale applications for roadside and land management projects.
By Application
The market is divided into land reclamation, landscaping, agriculture, and erosion control applications. The land reclamation segment is the largest due to growing concerns over environmental degradation and soil erosion. Hydroseeding plays a critical role in restoring soil health in these areas. Landscaping follows closely as hydroseeding is increasingly preferred for its efficiency in creating green spaces in urban environments. Agricultural applications present significant growth opportunities, with hydroseeding being used for cover crops, pasture management, and improving soil health.
- For instance, GeoGrow hydroseeded a 60-degree slope at Halesfield, transforming 1,200 m² of barren clay into a vegetated area within two days.
By End-User
The hydroseeding market is segmented by end-user into construction, agriculture, and government organizations. The construction segment dominates, driven by the increasing demand for efficient and sustainable landscaping solutions in urban development. Government organizations are adopting hydroseeding for land reclamation, erosion control, and environmental sustainability. The agriculture sector, with its focus on improving land quality and productivity, is also a key end-user, as hydroseeding offers an effective method for soil stabilization and crop growth.
Segmentations:
By Type
- Hydroseeding Slurry
- Hydroseeding Equipment
- Hydroseeding Mulch
By Application
- Land Reclamation
- Landscaping
- Agriculture
- Erosion Control
By End-User
- Construction
- Agriculture
- Government Organizations
By Equipment Type
- Sprayers
- Mixers
- Blowers
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America Leading the Hydroseeding Market
North America holds a dominant position in the hydroseeding market, accounting for 35% of the global share. This growth is driven by a strong construction sector and significant investments in land reclamation and erosion control. The United States, in particular, has seen a significant rise in infrastructure projects, including highways, roads, and residential complexes, where hydroseeding is widely employed for landscaping and soil stabilization. The region’s stringent environmental regulations also contribute to the growing adoption of hydroseeding as an eco-friendly solution. As green building initiatives gain momentum, the demand for sustainable landscaping and erosion control methods, such as hydroseeding, continues to rise.
Europe Seeing Increased Adoption Due to Environmental Initiatives
Europe holds a 25% share in the hydroseeding market, supported by strong environmental regulations and sustainability efforts. The European Union’s focus on green infrastructure, land rehabilitation, and sustainable development fosters the adoption of hydroseeding across various industries. Countries such as Germany, France, and the United Kingdom have seen increased use of hydroseeding in urban landscaping, agriculture, and land reclamation projects. Governments in the region are increasingly incorporating green building and environmental standards, making hydroseeding an attractive alternative to traditional seeding methods. The trend toward eco-friendly solutions continues to gain traction, further boosting market growth.
Asia Pacific Showing Significant Growth Potential
The Asia Pacific region accounts for 20% of the global hydroseeding market share, with substantial growth opportunities driven by rapid urbanization and expanding infrastructure projects. Countries like China, India, and Japan are experiencing a construction boom, creating increased demand for landscaping and erosion control solutions. Hydroseeding is also gaining traction in land rehabilitation and agriculture due to its cost-effectiveness and environmental benefits. As agriculture continues to modernize and face challenges like soil erosion, hydroseeding presents a valuable tool for sustainable land management. The growing awareness of environmental sustainability and the need for efficient land use in the region is expected to drive further adoption of hydroseeding technologies.
Key Player Analysis:
- Finn Corporation
- TurfMaker
- HydroGrass Technologies
- Epic Manufacturing
- Bowie Industries
- Turbo Turf
- Reed Hydromulch
- Kincaid Equipment Manufacturing
- Landmark Erosion Control
- Hydroseeding Technologies
Competitive Analysis:
The hydroseeding market is highly competitive, with key players focusing on innovation, technological advancements, and sustainability to secure their positions. Leading companies provide a variety of products, including hydroseeding slurry, mulch, and specialized equipment such as sprayers, mixers, and blowers. Market leaders are investing in research and development to improve efficiency, reduce costs, and enhance the environmental impact of hydroseeding techniques. Expanding their presence in emerging markets, especially in regions with growing infrastructure and land reclamation needs, allows these companies to tap into new opportunities. Collaborations with government and construction sectors further strengthen their competitive edge. As demand for sustainable solutions increases, market players are aligning their offerings with eco-friendly practices, driving innovation and growth in the hydroseeding market. Strategic mergers and acquisitions are also shaping the competitive landscape, enabling companies to expand their product portfolios and market reach. The rise in environmentally conscious construction and agricultural practices further intensifies competition.
Recent Developments:
- In January 2025, Epic Group (Epic Manufacturing) announced a strategic joint venture with Creative Group to expand operations in India’s apparel sector.
- In August 2024, Landmark Construction Company announced its involvement in "Project Connect" in Blythewood, South Carolina.
- In March 2025, Kincaid Equipment Manufacturing highlighted the delivery of its most recent Classic Flex 4-row, 36" Row Spacing Planter, customized for a Florida customer for peanuts, corn, cotton, and soybeans.
Market Concentration & Characteristics:
The hydroseeding market is moderately concentrated, with several key players holding significant market share. These companies are focused on product innovation, enhancing the efficiency of hydroseeding equipment, and ensuring sustainability in their solutions. The market features a mix of established players and smaller, regional firms that offer specialized products tailored to specific applications, such as land reclamation, landscaping, and erosion control. The competition is driven by technological advancements, cost efficiency, and the growing demand for eco-friendly and sustainable solutions. Companies in the hydroseeding market are increasingly focusing on expanding their geographic footprint, particularly in emerging markets with increasing infrastructure and agricultural development needs. The industry sees a steady flow of collaborations and partnerships, further strengthening the market's competitive dynamics. Hydroseeding’s cost-effectiveness and environmental benefits are key factors that continue to drive its adoption across various sectors.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application, End-User, Equipment Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Hydroseeding technology will see increased adoption in urban development projects as cities focus on enhancing green spaces.
- Environmental regulations and sustainable landscaping practices will drive the demand for hydroseeding solutions across various industries.
- The market will benefit from innovations in seed mix formulations, improving the efficiency and success rates of hydroseeding applications.
- The growing focus on erosion control and land reclamation will boost the adoption of hydroseeding in construction and mining sectors.
- Increased awareness about soil conservation will encourage the use of hydroseeding in areas prone to soil erosion.
- Hydroseeding will be utilized more in large-scale government and infrastructure projects, including highways and public parks.
- The rise in demand for drought-tolerant and native plants will influence the evolution of hydroseeding solutions to meet these needs.
- Technological advancements in application equipment will reduce costs and improve precision in hydroseeding operations.
- Increased use of hydroseeding in disaster recovery efforts, especially after wildfires or floods, will expand its market reach.
- Stronger partnerships between hydroseeding providers and landscape architects will lead to more customized and innovative solutions for different applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Hydroseeding Market?
What factors are driving the growth of the Hydroseeding Market?
Which regions are leading in the Hydroseeding Market?
What are the benefits of using hydroseeding?
Why is the construction industry contributing to the demand for hydroseeding?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Hydroseeding Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Hydroseeding Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,593.83 million → 2032: USD 2,914.66 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Hydroseeding Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Hydroseeding Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Hydroseeding Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Hydroseeding Market Drivers
- 3.3 Hydroseeding Market Restraints & Challenges
- 3.4 Hydroseeding Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Hydroseeding Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Hydroseeding Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Hydroseeding category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Hydroseeding Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Hydroseeding Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Hydroseeding market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Hydroseeding Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Hydroseeding Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Hydroseeding Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Hydroseeding (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Hydroseeding Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Hydroseeding Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Hydroseeding Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Hydroseeding Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Hydroseeding Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Hydroseeding Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Hydroseeding Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Hydroseeding Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Hydroseeding Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
