
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
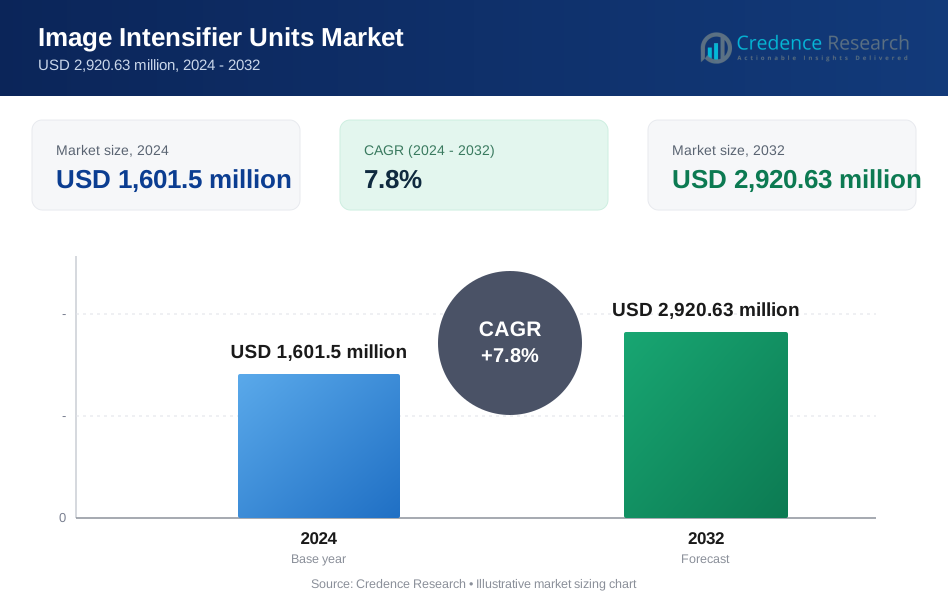
| Image Intensifier Units market Size 2024 | USD 1,601.5 million |
| Image Intensifier Units market, CAGR | 7.8% |
| Image Intensifier Units market Size 2032 | USD 2,920.63 million |
Market Overview
The global Image Intensifier Units market is projected to grow from USD 1,601.5 million in 2024 to USD 2,920.63 million by 2032, exhibiting a CAGR of 7.8% during the forecast period.
The growth of the image intensifier units market is driven by increasing demand for advanced imaging systems in defense, medical diagnostics, and industrial applications. Rising investments in night vision technology and surveillance solutions, coupled with advancements in image intensifier technologies, enhance operational efficiency and imaging clarity. Additionally, the expanding use of image intensifiers in emerging markets, driven by improved healthcare infrastructure and growing military expenditures, fuels market growth. Industry trends include the integration of lightweight, portable devices and the adoption of digital image intensifiers, addressing the need for enhanced performance, durability, and energy efficiency across diverse applications.
The Image Intensifier Units (IIUs) market is experiencing significant growth across various regions, driven by advancements in defense, healthcare, and industrial applications. Key players like Harris Corporation (U.S.), L3 Technologies (U.S.), Thales Group (France), Siemens AG (Germany), and Canon Medical Systems (Japan) lead the market with innovative technologies and solutions. These companies are expanding their presence in emerging markets, such as Asia-Pacific and the Middle East, where rising defense budgets and increasing demand for medical imaging systems are fueling the adoption of IIUs. Continued technological advancements and regional investments in security and healthcare further drive market expansion.
Market Drivers
Increasing Adoption in Industrial and Scientific Applications
IIUs are finding growing applications in industrial and scientific sectors due to their ability to deliver precise imaging in low-light conditions. For instance, a survey by the National Institute of Standards and Technology (NIST) indicates that IIUs play a vital role in non-destructive testing, quality control, and maintenance in industries such as aerospace, automotive, and manufacturing. Scientific research also benefits significantly, with IIUs aiding researchers in fields like astronomy, biology, and materials science by capturing detailed images and data that would otherwise remain obscured in low-light settings.
Advancements in Medical Imaging
Medical imaging advancements are driving the adoption of IIUs in healthcare. For instance, a study published in the Journal of Medical Imaging and Radiation Sciences shows that IIUs enhance image quality in diagnostic imaging, enabling earlier and more accurate detection of diseases. These units are also integrated into surgical equipment to improve visualization during minimally invasive procedures, boosting surgical precision and outcomes. The expanding healthcare infrastructure and demand for advanced imaging technologies further propel this growth, making IIUs indispensable in modern medical practices.
Technological Innovations and Rising Security Needs
Technological advancements have significantly improved the performance of IIUs, with innovations such as higher-resolution imaging, reduced noise, miniaturization, and increased sensitivity enhancing their utility across industries. Additionally, rising global security concerns and increasing defense spending are driving demand for IIUs in fraud detection, document verification, and security screening systems, solidifying their role in both safety and operational excellence.
Growing Demand for Night Vision Technology
The expanding use of Image Intensifier Units (IIUs) in night vision technology is a key driver for market growth. Law enforcement agencies rely on these units for surveillance, night patrols, and tactical operations, ensuring public safety and crime prevention. Furthermore, IIUs are integral to security and surveillance systems, providing clear visuals for border patrol, wildlife conservation, and industrial security, where reliable monitoring in challenging environments is essential.
Market Trends
Technological Advancements Driving Performance and Accessibility
Technological innovations are reshaping the Image Intensifier Units (IIUs) market by significantly enhancing their performance and expanding their applicability. For instance, a report by the U.S. Department of Defense highlights that manufacturers are focusing on improving image quality, introducing IIUs capable of delivering high-resolution, low-noise visuals even in extremely low-light conditions. This advancement is critical for applications requiring precise imaging, such as military operations and medical diagnostics. Miniaturization is another key trend, with smaller, lighter IIUs making these devices more portable and suitable for diverse uses, including wearable devices and compact surveillance systems. Additionally, increased sensitivity in newer IIU models enables them to capture faint light signals, broadening their application in fields like astronomy and security. The integration of IIUs with cutting-edge technologies, such as artificial intelligence and machine learning, further enhances their functionality, allowing for more accurate image analysis and interpretation.
Expanding Applications Across Diverse Sectors
The versatility of IIUs is driving their adoption across a wide range of industries. In the military and defense sector, these units remain essential for night vision applications, ensuring operational efficiency in low-light environments. Law enforcement agencies utilize IIUs for surveillance, tactical operations, and night patrols, while security and surveillance systems integrate them for monitoring in border security, wildlife conservation, and industrial settings. In the medical field, IIUs enhance diagnostic imaging by providing clearer visuals for earlier disease detection and improved visualization during minimally invasive surgeries. Industrial inspection also benefits from IIUs, which are used for non-destructive testing and quality control in aerospace, automotive, and manufacturing industries. Scientific research leverages IIUs in fields like biology, materials science, and astronomy to capture detailed data in dimly lit conditions. With growing demand in emerging markets like Asia-Pacific and the Middle East, driven by increasing defense budgets and economic growth, as well as heightened focus on cybersecurity and critical infrastructure protection, the applications of IIUs are set to expand further.
Market Challenges Analysis
High Costs and Operational Limitations
The production of Image Intensifier Units (IIUs) involves complex manufacturing processes and specialized components, resulting in high costs that can hinder their widespread adoption, particularly in price-sensitive consumer markets. For instance, a report by the U.S. Department of Defense highlights that the development and production of advanced IIUs require significant investment in research and development, sophisticated manufacturing processes, and high-quality materials. Additionally, the reliance of portable IIUs on power-intensive components leads to limited battery life, which restricts their operational duration in field applications. These factors pose significant challenges for users requiring extended use or those operating within budget constraints, impacting their appeal in certain applications. Despite technological advancements, IIUs still face image quality limitations, especially in adverse conditions like low light, fog, and smoke, which can compromise their effectiveness in critical environments such as military or security operations.
Environmental Sensitivity and Market Competition
IIUs are susceptible to environmental factors like temperature extremes, humidity, and physical shocks, which can affect their performance and longevity. Such sensitivity demands robust design solutions, increasing development complexity and costs. Furthermore, IIUs face growing competition from emerging technologies like thermal imaging and advanced digital sensors. These alternatives offer distinct advantages, such as enhanced performance in diverse conditions, influencing market preferences and challenging IIU adoption in certain sectors. Regulatory hurdles, particularly in military and aerospace applications, add to the complexity, with stringent quality and performance standards driving up costs and prolonging time-to-market. Additionally, supply chain constraints for specialized components and materials create potential disruptions, leading to increased production costs and delayed delivery schedules, further challenging the IIU market.
Market Segmentation Analysis:
By Diameter:
The Image Intensifier Units (IIUs) market is segmented by diameter, catering to varying operational needs. Units with diameters of <18 mm and 18 mm are primarily used in portable and lightweight devices, making them suitable for goggles and compact surveillance systems. The 25 mm category finds application in mid-range devices, offering a balance between portability and performance, commonly used in industrial inspections and night vision scopes. Larger diameters, such as >25 mm, cater to high-performance requirements, delivering superior image quality for demanding applications in defense and security. Diameters classified as 6-inch, <6-inch, 9-inch, 12-inch, and 16-inch address diverse imaging needs across healthcare, military, and industrial sectors, with larger diameters often used in advanced medical imaging and long-range surveillance systems. This segmentation allows manufacturers to target specific market demands while addressing application-specific challenges such as resolution, sensitivity, and durability.
By Application: Segmented by application, IIUs serve diverse functions in cameras, scopes, goggles, and X-ray detectors. Cameras equipped with IIUs are integral to night vision and low-light photography, addressing needs in security, wildlife monitoring, and law enforcement. Scopes utilizing IIUs are prevalent in defense and hunting, enabling precision targeting under low visibility. Goggles, a critical application in defense and surveillance, enhance mobility and situational awareness in dark environments. X-ray detectors equipped with IIUs are essential in healthcare, providing clear, high-resolution imaging for diagnostic and surgical procedures. These applications highlight the adaptability of IIUs across industries, where their ability to enhance visibility and imaging quality under low-light or specialized conditions is paramount. The increasing demand for IIUs in such applications reflects their indispensable role in enabling effective operations, whether in healthcare facilities, industrial environments, or on the field. This versatility ensures continued growth and innovation in the IIU market.
Segments:
Based on Diameter
- <18 mm
- 18 mm
- 25 mm
- >25 mm
- 6 inch
- <6 inch
- 9 inch
- 12 inch
- 16 inch
Based on Application
- Cameras
- Scope
- Goggles
- X-Ray Detectors
Based on End User
- Healthcare
- Defense & Surveillance
- Manufacturing
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest share of the Image Intensifier Units (IIUs) market, accounting for over 35%. This dominance is driven by robust investments in defense and surveillance technologies, alongside advancements in healthcare infrastructure. The United States, in particular, has a substantial demand for IIUs in military applications, including night vision systems for border security and tactical operations. Additionally, the region’s healthcare sector integrates IIUs into diagnostic imaging and surgical procedures, supported by cutting-edge medical technology adoption. The presence of key manufacturers and a well-established supply chain further strengthens the market, ensuring innovation and timely delivery of high-performance IIUs. Continued defense spending and the growing focus on security and healthcare advancements are anticipated to sustain North America's leadership in the IIU market.
Asia-Pacific Asia-Pacific is emerging as a rapidly growing market for IIUs, with an estimated share of 27%. The region's growth is fueled by increasing defense budgets in countries like China, India, and South Korea, which prioritize the adoption of advanced surveillance and night vision technologies for military and border security applications. The industrial sector also contributes to the demand for IIUs, with industries such as automotive, aerospace, and manufacturing using these units for non-destructive testing and quality control. Furthermore, the expanding healthcare infrastructure in Asia-Pacific supports the integration of IIUs in medical imaging systems, addressing the rising demand for efficient diagnostic tools. Favorable government initiatives and investments in technology development are enhancing the accessibility of IIUs, fostering regional market growth. As countries in Asia-Pacific continue to prioritize security and technological innovation, the IIU market is poised for robust expansion, cementing the region’s position as a critical player in the global landscape.
Key Player Analysis
- FLIR Systems (France)
- Thales Group (France)
- Siemens AG (Germany)
- Argus Imaging BV (Netherlands)
- Photonics Technology (France)
- Canon Medical Systems (Japan)
- Harris Corporation (U.S.)
- Tak Technologies Pvt. Ltd (India)
- L3 Technologies (U.S.)
- Photok Limited (UK)
Competitive Analysis
The Image Intensifier Units (IIUs) market is highly competitive, with leading players such as Harris Corporation, L3 Technologies, Thales Group, Siemens AG, Canon Medical Systems, FLIR Systems, Photonics Technology, Photok Limited, Argus Imaging BV, and Tak Technologies Pvt. Ltd. Players in the industry focus on enhancing image resolution, portability, and sensitivity to meet the growing demand in defense, healthcare, and industrial applications. Companies involved in defense applications are concentrating on developing advanced night vision technologies, while those in the medical sector are integrating IIUs into diagnostic imaging systems to enhance early disease detection. Additionally, companies in the security and surveillance sectors are prioritizing high-performance solutions for border security and law enforcement. To maintain a competitive edge, firms are investing in R&D and expanding their geographical reach, ensuring they remain at the forefront of innovation. Their focus on meeting evolving market needs and incorporating emerging technologies is vital for sustaining growth and gaining a larger market share in the IIU industry.
Recent Developments
- In November 2022, L3Harris Technologies delivered its 10,000th Enhanced Night Vision Goggle-Binocular to the U.S. Army and received a new production order for additional ENVG-Bs. Unlike any other night vision system, the combat-proven ENVG-B enables soldiers to locate, evaluate, and engage a target with better accuracy and speed. The ENVG-B gives soldiers vital situational awareness during low-light and night operations to keep them safe during the mission with the help of cutting-edge fusion technology.
- In July 2022, Subtle Medical, a key provider of artificial intelligence (AI) solutions for medical imaging, and Siemens Healthineers, a leading medical technology company, officially announced the integration of Subtle Medical's SubtleMR image-enhancement software into the new reconstruction pipeline of Siemens Healthineers, Open Recon. SubtleMR offers DL (deep learning) post-processing for denoising and increased sharpness on faster MRI sequences, enabling improved image quality, optimized workflow, and a better patient experience.
- In July 2022, Canon medical systems corporation launched Vantage Fortian at ECR 2022. The new MRI system has cutting-edge workflow strategies, image enhancement, and expedited scan technologies, all of which help shorten the time needed for MRI treatments. The Vantage Fortian uses machine learning and deep learning technologies to automate various scan processes, validate setup steps to save time, and improve image quality by reducing noise and restoring signal-to-noise ratio (SNR).
- In June 2022, Teledyne FLIR announced the addition of an E52 camera to its range of Exx thermal Imaging devices which currently include the E96, E86, E76, and E54 models. The new E52 camera offers professional quality thermal resolution to ensure that images are easy-to-read and on-camera routing capability to improve field survey efficiency.
- In March 2022, Hamamatsu Photonics announced the development of THz-I.I., the world’s first terahertz image intensifier which is capable of real-time non-destructive imaging, the device could have applications in the foreign matter inspection of food products and in (human) body scanning.
Market Concentration & Characteristics
The market for Image Intensifier Units (IIUs) is moderately concentrated, with several key players leading innovation and driving industry growth. This concentration is characterized by the presence of established companies that dominate the defense, healthcare, and industrial sectors, where IIUs play a critical role. These players are continually advancing their technology to offer higher resolution, increased sensitivity, and enhanced portability. The market is also marked by a significant focus on R&D investments, with companies working to develop next-generation solutions that meet the evolving demands of defense applications, medical imaging, and industrial inspection. Additionally, strategic partnerships and collaborations are common, enabling firms to expand their product portfolios and regional reach. While there are dominant players, smaller companies with specialized offerings also carve out niches by providing tailored solutions for specific applications. This dynamic balance between large enterprises and specialized players shapes the competitive landscape of the IIU market.
Report Coverage
The research report offers an in-depth analysis based on Diameter, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for Image Intensifier Units (IIUs) is expected to grow significantly due to increased defense and security needs globally.
- Advancements in IIU technology will continue, focusing on improving image quality and sensitivity in low-light conditions.
- The integration of IIUs with artificial intelligence and machine learning will enhance their image analysis capabilities.
- Miniaturization of IIUs will drive their adoption in portable and wearable devices.
- Rising investments in healthcare infrastructure will spur the use of IIUs in diagnostic imaging and surgical procedures.
- The growing focus on border security and law enforcement will lead to higher demand for IIUs in surveillance applications.
- IIUs will see increased application in industrial inspection, particularly in aerospace and automotive industries.
- As defense budgets increase in emerging economies, there will be a rise in IIU adoption for military and surveillance operations.
- The Asia-Pacific region will continue to be a key growth area due to its expanding defense and healthcare sectors.
- Strict regulatory standards will drive innovation, ensuring higher performance and compliance in IIU manufacturing.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Image Intensifier Units market?
What factors are driving the growth of the Image Intensifier Units market?
What are the key segments within the Image Intensifier Units market?
What are some challenges faced by the Image Intensifier Units market?
Who are the major players in the Image Intensifier Units market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Image Intensifier Units Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Image Intensifier Units Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,601.5 million → 2032: USD 2,920.63 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Image Intensifier Units Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Image Intensifier Units Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Image Intensifier Units Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Image Intensifier Units Market Drivers
- 3.3 Image Intensifier Units Market Restraints & Challenges
- 3.4 Image Intensifier Units Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Image Intensifier Units Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Image Intensifier Units Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Image Intensifier Units category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Image Intensifier Units Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Image Intensifier Units Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Image Intensifier Units market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Image Intensifier Units Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Image Intensifier Units Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Image Intensifier Units Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Image Intensifier Units (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Image Intensifier Units Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Image Intensifier Units Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Image Intensifier Units Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Image Intensifier Units Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Image Intensifier Units Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Image Intensifier Units Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Image Intensifier Units Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Image Intensifier Units Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Image Intensifier Units Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
