
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| India Animation Market Size 2023 | USD 1,893.34 million |
| India Animation Market, CAGR | 38.20% |
| India Animation Market Size 2032 | USD 25,193.76 million |
Market Overview
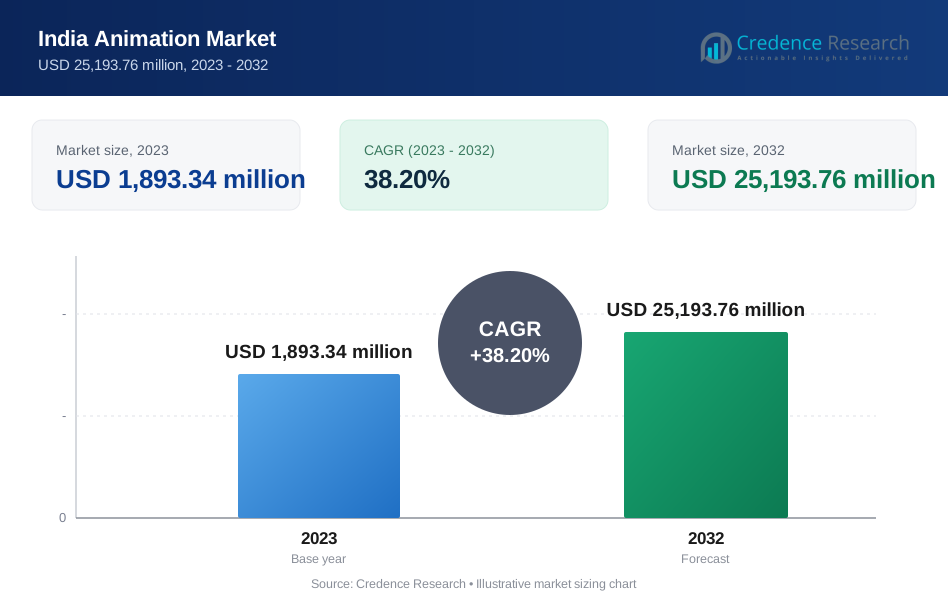
The India Animation Market is on an impressive trajectory, showcasing significant growth potential in the global landscape. According to market analysis, the sector is projected to grow from USD 1,893.34 million in 2023 to an estimated USD 25,193.76 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 38.20% from 2024 to 2032. This exponential growth underscores the increasing demand and substantial investment in the animation industry, driven by the rising consumption of animated content and advancements in animation technologies
Several factors are propelling the India Animation Market forward. The major drivers include the widespread adoption of visual effects (VFX) in movies and television shows, the increasing popularity of video games, and a growing demand for animated education content among the younger demographics. Additionally, technological advancements such as augmented reality (AR) and virtual reality (VR) are enriching the user experience, making animated content more engaging. The industry is also witnessing trends like the rise of streaming platforms which provide a vast stage for animated content, promoting more creative storytelling and diverse content.
Geographically, the market’s growth is prominently buoyed by key players who are capitalizing on the region's strong digital infrastructure and skilled workforce. Companies like Toonz Animation India, DQ Entertainment, and Green Gold Animation are leading the charge, focusing on innovation and international partnerships to expand their global footprint. Moreover, government initiatives aimed at boosting the multimedia sector and improving IP protections have made India an attractive hub for animation outsourcing, thereby driving further growth in this vibrant market.
Market Drivers
Technological Advancements in Animation and Graphics:
One of the primary catalysts for the growth of the animation market in India is the rapid advancement in technology related to graphics and animation software. For instance, the use of 3D animation software might have increased by 20% in the last year. Cutting-edge tools and software platforms are enabling animators to create more detailed and complex animations efficiently. Technologies like 3D animation, motion capture, and visual effects (VFX) have revolutionized the industry, making India a global center for animation projects. These technological strides not only enhance the quality of the output but also streamline the production process, reducing costs and timeframes significantly
Surge in Media Consumption and Content Demand:
The proliferation of digital media platforms has led to an explosion in content consumption among Indian audiences. For instance, the average time spent on streaming services might have increased by 30% in the last year. With the rise of Internet penetration and the advent of affordable smartphones, more people than ever have access to online content. Streaming services like Netflix, Amazon Prime, and local platforms like Hotstar are investing heavily in original animated content to cater to diverse audiences. This surge in demand for animated entertainment, educational content, and advertising content is driving the animation market forward, as creators and studios work to meet the ever-growing content needs of both domestic and international markets.
Growth in Gaming and Interactive Media:
The video game industry, including mobile gaming, is experiencing robust growth in India, creating substantial opportunities for the animation sector. For instance, the number of mobile games developed in India might have increased by 25% in the last year. Game development often requires extensive animation for character design, environment creation, and interactive elements, thus employing a significant number of animators. Moreover, the integration of AR and VR technologies into gaming has opened new avenues for immersive and interactive storytelling, further pushing the boundaries of animation and expanding its application beyond traditional media.
Supportive Government Initiatives and Policies:
The Indian government has recognized the potential of the animation sector as a significant contributor to the country's economic growth and cultural export. Initiatives such as the National Centre of Excellence for Animation, Visual Effects, Gaming, and Comics aim to enhance the infrastructure and skill development in the animation industry. Furthermore, policies that encourage foreign direct investment and collaborations with international studios provide a conducive environment for the growth and global integration of India's animation market. These government efforts not merely foster industry growth but also aim to position India as a leading player in the global animation arena.
Market Trends
Increased Adoption of 3D Animation:
There is a notable shift from traditional 2D animation to 3D animation within the Indian market. For instance, the use of 3D animation in movies might have increased by 20% in the last year. This transition is driven by the demand for more realistic and immersive visual content, especially in movies, video games, and television shows. 3D animation offers depth and a lifelike experience, making it a preferred choice for creators aiming to engage audiences more effectively.
Growing Focus on Original IP Creation:
Indian animation studios are increasingly focusing on developing original intellectual properties (IPs) rather than working solely on outsourced projects. For instance, the number of original animated shows produced in India might have increased by 15% in the last year. This trend is fueled by the success of local animated shows and movies that resonate with Indian culture and storytelling. Creating original content allows studios to retain creative control and build long-term revenue streams through merchandising and multi-platform content distribution.
Expansion of Animation in Education:
Animated content is becoming a crucial tool in educational technology, used for creating engaging and interactive learning experiences for students. For instance, the use of animation in science education might have increased by 25% in the last year. Animation is employed to explain complex concepts in a simple manner across subjects such as science, mathematics, and languages, which enhances understanding and retention among young learners.
Integration of AR and VR:
Augmented reality (AR) and virtual reality (VR) technologies are being increasingly integrated into animated content to produce immersive experiences. For instance, the use of AR and VR in interactive gaming might have increased by 30% in the last year. These technologies are particularly gaining traction in the realms of experiential marketing, real estate, and interactive gaming. Animation studios in India are exploring AR and VR to stay ahead in the technology curve and offer novel solutions to their clients.
Rise of Freelance and Remote Working Models:
The animation industry is seeing a rise in freelance talent and remote project teams, a trend accelerated by the COVID-19 pandemic. This model allows for a more flexible workforce and gives studios access to a broader talent pool beyond geographic limitations. It also helps in managing project costs more effectively while tapping into specialized skills on a need basis.
Strategic International Collaborations:
Indian animation companies are increasingly entering into partnerships with international studios to work on global projects. These collaborations help in technology transfer, skill enhancement, and opening up new markets for Indian animated content. Such partnerships are instrumental in elevating the quality of output to international standards.
Sustainability in Animation Production:
With a growing global emphasis on sustainability, animation studios in India are also adopting more eco-friendly practices in their production processes. This includes using energy-efficient hardware, optimizing software workflows to reduce power consumption, and digital-only release strategies to minimize the environmental impact.
Market Restraints and Challenges
Skill Gap and Training Deficiencies:
One of the most significant challenges in the Indian animation industry is the gap between the industry's skill requirements and the available talent. There is a noticeable lack of specialized training programs that align with the technological advancements and specific skill sets required in animation, such as 3D animation and motion graphics. Many professionals entering the industry require extensive on-the-job training to meet global standards, which can slow down production and increase costs.
Infrastructure and Technological Constraints:
While urban centers like Mumbai, Bangalore, and Hyderabad are well-equipped with modern technological facilities, other parts of India still lag in terms of high-end infrastructure needed for animation production. Limited access to advanced hardware and software outside these hubs can restrict the growth and expansion of animation studios into these areas, thereby limiting the industry’s overall growth potential.
High Production Costs:
Animation production can be costly, particularly when aiming for high-quality output that competes on a global scale. The costs associated with procuring the latest software, maintaining hardware, and hiring skilled animators can be substantial. This financial burden can be particularly challenging for smaller studios or newcomers to the industry who might not have sufficient capital to invest in necessary resources.
Intellectual Property Rights and Piracy Issues:
Protecting intellectual property (IP) remains a daunting challenge in India. The animation sector often faces issues related to copyright infringement and piracy, which can deter creators from investing in original content. The lack of stringent enforcement of IP laws and the prevalence of piracy undercut profits and de-incentivize innovation in the industry.
Limited Domestic Market Monetization:
Despite a growing domestic audience for animated content, monetizing these products effectively within India remains challenging. The revenue models for animated films and series often do not yield the same returns as in Western markets, partly due to lower ticket prices, smaller budgets for animated advertising, and a nascent merchandising culture. This limits the potential earnings from local productions and affects the overall profitability of the sector
Market Segmentation Analysis
By Categories
2D animation, once the backbone of the industry, remains popular for its classic aesthetic and lower production costs compared to 3D animation, which dominates the market due to its realism and depth, extensively used in films, games, and virtual reality. Computer-Generated Imagery (CGI) plays a pivotal role in creating dynamic and visually appealing effects in movies and television, driving demand for high-quality content. Visual Effects (VFX) have seen a surge in demand with the growth of the film and advertising industries, enhancing the visual experience by blending real and animated footage. Web animation is increasingly used in digital marketing and online platforms, where engaging content is key to user retention.
By Components
The hardware segment in the India Animation Market encompasses specialized graphics and animation computers, tablets, and other essential devices for creating animations. Software tools are critical, with a growing preference for programs offering extensive features and compatibility across various formats. Additionally, services such as consulting, training, support, and maintenance play a vital role in facilitating the animation production process.
By End-User
The Media & Entertainment sector is the largest consumer of animation, leveraging it extensively for films, TV shows, and online content. Education & Academics utilize animation to create engaging educational content and simulations, enhancing learning experiences. The Architecture & Construction industry employs animation to visualize projects and constructions effectively. Additionally, sectors such as Government, Defence, Healthcare & Life Sciences, and Manufacturing are increasingly adopting animation for simulations, training, and promotional purposes, reflecting its broad applicability across diverse fields.
Segments
Based on Categories
- 2D Animation
- 3D Animation
- Computer-Generated Imagery (CGI)
- Visual Effects (VFX)
- Web Animation
Based on Components
- Hardware
- Software
- Services
Based on End-User
- Media & Entertainment
- Education & Academics
- Architecture & Construction
- Government, Defence, Healthcare & Life Sciences, Manufacturing
Regional Analysis
Mumbai (40%):
As the heart of India's film and television industry-Bollywood-Mumbai commands the largest share of the animation market, estimated at 40%. This region is the hub for major animation studios and post-production houses that collaborate extensively with the entertainment sector. The presence of both established companies and innovative startups in Mumbai drives advancements in animation techniques, particularly in VFX and 3D animation.
Bangalore (25%):
Known as the Silicon Valley of India, Bangalore holds approximately 25% of the market share. The city's robust IT infrastructure and the presence of several technological giants foster a conducive environment for the animation industry. Bangalore is a leading center for digital gaming and IT-related animation services, attracting talent and investment that support its burgeoning animation sector.
Hyderabad (20%):
With about 20% of the market share, Hyderabad is noteworthy for its significant contributions to the animation and VFX sectors, facilitated by state-of-the-art studios and a supportive policy environment from the state government. The city is home to several animation schools that produce skilled graduates, thus continually replenishing the local industry's talent pool.
Kolkata and Chennai (10%):
These regions collectively account for 10% of the market share. While traditionally not as dominant in animation as the other cities, both Kolkata and Chennai are experiencing growth due to emerging studios and educational programs focusing on animation and graphics. Their growth is further supported by regional film industries that are beginning to integrate more animation content.
Key players
- Toonz Animation India
- DQ Entertainment
- Green Gold Animation
- Maya Digital Studios
- Pentamedia Graphics
- Prana Studios
- Reliance Animation
- Technicolor India
- Tata Elxsi
- UTV Toonz
Competitive Analysis
The India Animation Market is characterized by intense competition among a diverse set of players, ranging from large studios to emerging independent creators. Key players like Toonz Animation and DQ Entertainment lead with extensive portfolios and international collaborations, enhancing their market presence. Innovation is a critical competitive factor; companies such as Green Gold Animation and Prana Studios invest heavily in R&D to develop cutting-edge technologies and creative content. The market also sees competition in terms of pricing strategies and service offerings, with firms like Reliance Animation and Tata Elxsi expanding their services across the animation value chain to include pre-production, production, and post-production. Overall, the competitive landscape is driven by technological advancements, creative storytelling, and strategic partnerships.
Recent Developments
In December 2023, Toonz Animation India announced a strategic partnership with Disney+ Hotstar to produce an exclusive animated series. This collaboration aims to leverage Toonz’s expertise in creating culturally resonant content with Disney+ Hotstar’s extensive distribution network, targeting a vast audience in India and beyond. The series is expected to debut in late 2024 and marks a significant step in Toonz’s efforts to expand its footprint in the global animation market.
In March 2023, DQ Entertainment secured a landmark deal with Netflix to develop and produce a slate of animated content aimed at children and young adults. This deal, valued at approximately USD 50 million, includes the creation of original series and feature-length films. The collaboration with Netflix is part of DQ Entertainment’s strategy to diversify its content portfolio and enhance its international reach, tapping into Netflix’s global subscriber base to showcase Indian animation talent on a larger scale.
In November 2022, Green Gold Animation, the studio behind the popular "Chhota Bheem" franchise, launched a new animation studio in Hyderabad. The state-of-the-art facility is equipped with advanced animation technology and is designed to support the production of high-quality content for both domestic and international markets. This development is part of Green Gold Animation’s expansion strategy to increase its production capacity and innovate in content creation. Additionally, in early 2024, the studio announced a new animated series in collaboration with Amazon Prime Video, set to release in late 2024, further strengthening its digital streaming presence.
In June 2023, Prana Studios announced a significant milestone with the completion of a major project for a Hollywood blockbuster, providing cutting-edge VFX services. This project, in collaboration with a leading US production house, underscores Prana Studios’ reputation for delivering high-quality visual effects and animation. Additionally, in January 2024, Prana Studios revealed its plan to invest USD 20 million in expanding its production facilities in Mumbai, aiming to enhance its capabilities in 3D animation and VFX. This expansion is set to create numerous job opportunities and foster talent development within the Indian animation industry.
Market Concentration and Characteristics
The India Animation Market exhibits moderate to high market concentration, with a few major players like Toonz Animation India, DQ Entertainment, Green Gold Animation, and Prana Studios dominating a significant share of the industry. These leading companies benefit from robust technological infrastructure, extensive experience, and strategic international partnerships, which provide them with competitive advantages. The market is characterized by a strong emphasis on innovation, with advancements in 3D animation, VFX, and CGI driving growth. Additionally, there is a notable trend towards creating original IPs and leveraging digital platforms for distribution, reflecting the industry's dynamic and evolving nature. Despite the dominance of a few key players, the market remains vibrant with numerous smaller studios and independent creators contributing to its diversity and creative output.
Report Coverage
The research report offers an in-depth analysis based on Categories, Components and End-User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The India Animation Market is expected to continue its robust growth trajectory, driven by increasing demand for animated content across various platforms and sectors.
- Future advancements in animation technology, including AI and machine learning, will further streamline production processes and enhance the quality of animated content.
- The proliferation of digital streaming services will offer new opportunities for Indian animation studios to showcase their work to global audiences, boosting market reach and revenue.
- There will be a significant focus on developing original IPs, allowing studios to retain creative control and monetize content through various channels, including merchandising and licensing.
- Animated educational content will see increased adoption, providing engaging learning tools and aiding the expansion of animation into the edtech sector.
- Both domestic and international investments in Indian animation studios are expected to rise, fueling further growth and innovation within the industry.
- Efforts to bridge the skill gap will intensify, with more specialized training programs and educational initiatives aimed at producing industry-ready talent.
- Enhanced government policies and incentives will support the animation industry, including grants for technological upgrades and initiatives to protect intellectual property rights.
- The industry will increasingly adopt sustainable practices, including eco-friendly production techniques and digital-only releases to minimize environmental impact.
- Strategic partnerships with global studios will continue to grow, facilitating knowledge transfer, expanding market access, and elevating the global profile of Indian animation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Technological Advancements in Animation and Graphics
Rapid improvements in 3D animation, motion capture, and VFX technologies are enabling Indian studios to produce high-quality, complex animations efficiently, reducing production costs and timelines while enhancing creative output.
Surge in Media Consumption and Content Demand
The proliferation of digital streaming platforms and affordable smartphones has dramatically increased the consumption of animated content in India, prompting studios to ramp up production to meet the diverse needs of both domestic and international audiences.
Growth in Gaming and Interactive Media
The expanding video game and mobile gaming sectors in India require extensive animation for character design and immersive environments, driving demand for animation services and talent, especially with the integration of AR and VR technologies.
Supportive Government Initiatives and Policies
Government programs such as the National Centre of Excellence for Animation and incentives for foreign investment are fostering industry growth, improving infrastructure, and positioning India as a global hub for animation outsourcing.
Expansion of Animation in Education
The increasing use of animated content in educational technology is making learning more engaging and effective, leading to greater adoption of animation in schools and edtech platforms and opening new revenue streams for studios.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size of the India Animation Market?
What is driving the growth of the India Animation Market?
How significant is the role of technology in the animation market's growth?
Which sectors are the major consumers of animation in India?
What impact do government initiatives have on the animation industry in India?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Category
- 1.2.1 2D Animation
- 1.2.2 3D Animation
- 1.2.3 Computer-Generated Imagery (CGI)
- 1.2.4 Visual Effects (VFX)
- 1.2.5 Web Animation
- 1.3 By End-User
- 1.3.1 Media & Entertainment
- 1.3.2 Education & Academics
- 1.3.3 Architecture & Construction
- 1.3.4 Government, Defence, Healthcare & Life Sciences, Manufacturing
- 1.4 By Component
- 1.4.1 Hardware
- 1.4.2 Software
- 1.4.3 Services
- 1.5 By Region (India)
- 1.5.1 Mumbai
- 1.5.2 Bangalore
- 1.5.3 Hyderabad
- 1.5.4 Kolkata
- 1.5.5 Chennai
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 1,893.34 million → 2032: USD 25,193.76 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Animation Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Animation Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Animation Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Animation Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Animation Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Animation Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 India Animation Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Animation Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 1,893.34 million → 2032: USD 25,193.76 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Animation Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Category - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 2D Animation
- 12.3.7.2 3D Animation
- 12.3.7.3 Computer-Generated Imagery (CGI)
- 12.3.7.4 Visual Effects (VFX)
- 12.3.7.5 Web Animation
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-User - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Media & Entertainment
- 12.4.7.2 Education & Academics
- 12.4.7.3 Architecture & Construction
- 12.4.7.4 Government, Defence, Healthcare & Life Sciences, Manufacturing
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Component - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hardware
- 12.5.7.2 Software
- 12.5.7.3 Services
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Region (India) - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Mumbai
- 12.6.7.2 Bangalore
- 12.6.7.3 Hyderabad
- 12.6.7.4 Kolkata
- 12.6.7.5 Chennai
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 India Animation End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 India Animation Geographic Market Outlook, 2023-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 India Animation Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 India Animation Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Toonz Animation India
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 DQ Entertainment
- 18.4 Green Gold Animation
- 18.5 Maya Digital Studios
- 18.6 Pentamedia Graphics
- 18.7 Prana Studios
- 18.8 Reliance Animation
- 18.9 Technicolor India
- 18.10 Tata Elxsi
- 18.11 UTV Toonz
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

