
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Outbound Tourism Market Size 2024 | USD 187,975 million |
| India Outbound Tourism Market, CAGR | 11.20% |
| India Outbound Tourism Market Size 2032 | USD 439,479.6 million |
Market Overview
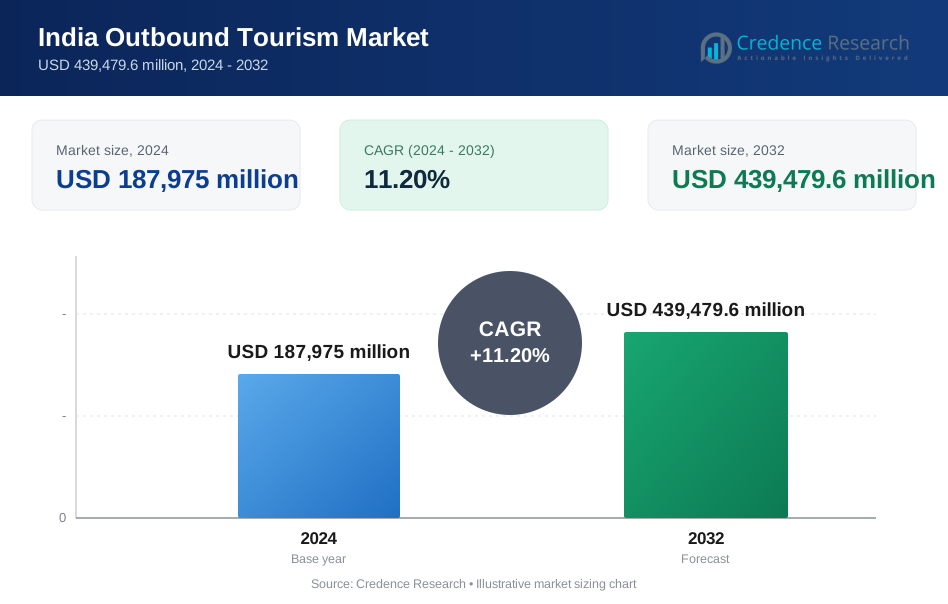
The India outbound tourism market is projected to grow from USD 187,975 million in 2024 to USD 439,479.6 million by 2032, registering a compound annual growth rate (CAGR) of 11.20% during the forecast period.
The India outbound tourism market is witnessing strong growth driven by rising disposable incomes, an expanding middle class, and greater accessibility to international travel through competitive airfares and streamlined visa processes. Increasing aspirations for global experiences, fueled by social media and exposure to diverse cultures, are significantly influencing travel decisions. The surge in international student enrollments and business travel from India also supports outbound traffic. Moreover, travel technology advancements and personalized online booking platforms enhance convenience and encourage frequent travel. Popular destinations such as Dubai, Singapore, the UK, and the US continue to attract Indian tourists for leisure, education, medical tourism, and shopping. There is a growing preference for curated experiences, wellness tourism, and eco-friendly travel, reflecting a shift toward value-based and conscious tourism. Additionally, travel aggregators and digital influencers are playing a pivotal role in shaping trends, while evolving consumer behavior is prompting service providers to offer more diversified and experiential travel packages tailored to niche segments.
The India outbound tourism market spans key regions including Asia-Pacific, Europe, North America, and the Rest of the World. Asia-Pacific leads with 44% share due to proximity and affordable travel, followed by Europe at 32%, driven by cultural, leisure, and educational demand. North America holds 18% share, supported by strong VFR, student, and business travel. The Rest of the World accounts for 6%, with growing interest in Africa, Oceania, and South America. Major players shaping the market include Thomas Cook, SOTC Kuoni, Cox and Kings, Kesari, TCI, Riya Travels, Amadeus, BTI Sita, Raj Travels, Orbit, Travelmart India, and In Orbit Tours. These companies compete on service quality, pricing, and destination offerings, while catering to diverse travel purposes including holiday, business, and VFR. Their presence across regions enables greater market penetration and responsiveness to evolving traveler preferences.
Market Insights
- The India outbound tourism market is projected to grow from USD 187,975 million in 2024 to USD 439,479.6 million by 2032, registering a CAGR of 11.20%.
- Rising disposable incomes, a growing middle class, and competitive airfares are expanding access to international travel across income groups and cities.
- Asia-Pacific holds 44% market share, followed by Europe at 32%, North America at 18%, and the Rest of the World at 6%, reflecting strong regional preferences.
- Increasing demand for curated experiences, wellness tourism, and eco-conscious travel is reshaping travel product offerings across key destinations.
- Currency volatility and high travel costs, including airfare and accommodation, remain significant challenges for mid-income travelers.
- Online platforms, social media, and digital influencers are driving travel discovery and simplifying the booking process for younger Indian tourists.
- Key players such as Thomas Cook, Cox and Kings, SOTC Kuoni, Kesari, and TCI continue to compete through personalized service, diversified itineraries, and regional outreach.
Market Drivers
Rising Disposable Income and Expanding Middle-Class Segment
The India outbound tourism market is benefitting from increasing disposable income levels and a rapidly expanding middle-class population. Economic growth has elevated consumer purchasing power, enabling more people to explore international travel opportunities. Aspirational spending on leisure and lifestyle experiences has become a priority for many Indian households. It supports higher spending on overseas vacations, including luxury stays, guided tours, and exotic destinations. This socio-economic shift continues to redefine travel expectations and boost outbound travel demand.
- For instance, Accor and InterGlobe are rapidly expanding their hospitality footprint, aiming to operate 300 hotels under Accor brands by 2030—a move responding directly to the surge in demand for quality, globally benchmarked hotel experiences among Indian travelers.
Improved Connectivity and Affordable Airfares
Air connectivity improvements and competitive ticket pricing are critical drivers of the India outbound tourism market. Low-cost carriers, expanded international routes, and strategic airline partnerships have increased travel frequency and accessibility. Tier-II and Tier-III cities now have better flight options to major international hubs. It enables broader demographic segments to consider international travel as a feasible option. Frequent flyer programs and digital booking platforms further support travel planning and cost-efficiency. These developments enhance outbound travel scalability.
- For instance, IndiGo’s Mumbai–Dubai route alone features four daily flights with over 5,200 seats weekly, operated by Airbus A320neo aircraft, reflecting the airline’s focus on high-frequency, high-capacity international corridors.
Easier Visa Policies and Government Support
Simplified visa procedures and bilateral agreements between India and popular tourist destinations are accelerating outbound travel. Countries offering visa-on-arrival or e-visa facilities for Indian passport holders attract more travelers. It shortens processing time, reduces barriers, and improves convenience. The Indian government also supports international tourism through campaigns and diplomatic engagements. Travel advisory improvements and better passport rankings strengthen traveler confidence. This fosters consistent outbound travel from both leisure and business segments.
Influence of Technology, Media, and Lifestyle Trends
The India outbound tourism market is strongly shaped by digital platforms, influencer marketing, and shifting consumer preferences. Exposure to international destinations through social media drives curiosity and demand. Technology makes it easier to research, book, and personalize travel plans with minimal effort. Millennials and Gen Z prioritize experiences such as wellness retreats, adventure travel, and culinary exploration. Travel is viewed as a lifestyle choice rather than luxury. It continues to redefine outbound tourism dynamics.
Market Trends
Preference for Experiential and Custom Travel Packages
Travelers are increasingly seeking personalized experiences over standardized tour itineraries. Demand for unique cultural, culinary, and wellness-based travel is rising, with many Indian tourists prioritizing authenticity and meaningful engagement during international trips. Travel companies are offering customized packages tailored to specific interests such as spiritual retreats, adventure sports, and offbeat destinations. The India outbound tourism market reflects this shift toward experiential tourism. It is reshaping the product offerings of travel agencies and influencing destination marketing strategies.
- For instance, Thomas Cook offers adventure-focused packages, including trekking in Leh-Ladakh and wildlife safaris in Gir, which can be fully customized for families or solo travelers seeking unique experiences.
Growth in Millennial and Gen Z Travelers
Millennials and Gen Z are emerging as dominant consumer segments in the India outbound tourism market. They favor digital convenience, flexible travel options, and immersive experiences. Social media platforms drive destination discovery and influence travel choices, encouraging spontaneous and visually appealing travel. These travelers value sustainability, wellness, and ethical tourism, prompting industry players to adapt services. It underscores the growing role of younger demographics in shaping outbound travel demand across regions.
- For instance, Travstarz, after being acquired by RezB2B Inc. in 2024, expanded its digital inventory and added five new DMC locations, with plans to cover Australia, New Zealand, South Africa, Kenya, and Morocco in 2025—broadening global access for Indian travelers.
Expansion of Online Travel Ecosystems
The rise of online travel agencies, aggregator platforms, and mobile apps is transforming how Indian travelers plan and book international trips. Real-time access to flights, accommodations, reviews, and pricing empowers travelers to make informed choices. Digital payments, loyalty programs, and AI-driven recommendations enhance user experience. The India outbound tourism market is increasingly digital in nature. It supports cost transparency, customer engagement, and market competitiveness, particularly among tech-savvy urban populations.
Surge in Medical, Education, and Business Travel
Beyond leisure, outbound travel for education, medical treatment, and business has seen sustained growth. Indian students are enrolling in foreign universities at higher rates, while affluent families seek quality healthcare overseas. Business professionals attend conferences, client meetings, and global networking events. The India outbound tourism market reflects these multifaceted travel purposes. It drives year-round demand, supports visa liberalization, and encourages partnerships between service providers and international institutions.
Market Challenges Analysis
Currency Volatility and High Travel Costs
Fluctuations in the Indian rupee against major global currencies pose a significant challenge to outbound travel affordability. Exchange rate instability often increases the overall cost of international trips, particularly for middle-income travelers. Rising airfare, accommodation charges, and overseas spending also strain travel budgets. The India outbound tourism market faces periodic slowdowns when currency pressure coincides with inflation or economic uncertainty. It directly affects demand for long-haul and premium destinations. Tour operators must adapt pricing strategies to maintain competitiveness.
Regulatory Barriers and Infrastructural Gaps
Stringent visa requirements, documentation delays, and security-related travel advisories can disrupt outbound travel plans. Limited international flight options from Tier-II and Tier-III cities also restrict seamless access to global destinations. The India outbound tourism market contends with infrastructural disparities that impact traveler convenience and confidence. Insufficient pre-departure support, lack of multilingual travel resources, and inconsistent travel insurance coverage create friction. Streamlined government cooperation and industry alignment are needed to reduce such regulatory and logistical constraints.
Market Opportunities
Rising Demand for Niche and Thematic Travel
The growing appetite for niche tourism segments presents a strong opportunity for service providers. Interest in wellness retreats, luxury cruises, adventure tourism, culinary exploration, and heritage circuits is increasing among Indian travelers. Tour operators can leverage this demand by curating themed packages that align with personal interests and lifestyle aspirations. The India outbound tourism market supports this diversification trend. It creates room for innovation in travel planning, destination promotion, and brand differentiation. Travel agencies focusing on curated experiences can gain a competitive edge.
Expansion into Emerging Travel Destinations
Emerging international destinations with relaxed visa policies and competitive pricing offer new growth avenues. Countries in Eastern Europe, Southeast Asia, and Central Asia are attracting Indian tourists seeking affordable and culturally rich experiences. These regions provide alternatives to saturated markets like Dubai, London, or Singapore. The India outbound tourism market can benefit from such diversification. It allows travel brands to tap into untapped traveler segments and distribute tourist traffic more evenly. Strategic partnerships with regional tourism boards can accelerate this expansion.
Market Segmentation Analysis:
By Purpose Type
The India outbound tourism market is segmented into Business, Holiday/Leisure, and VFR & Others (Visiting Friends and Relatives). Holiday/Leisure travel dominates the segment, driven by rising disposable income, lifestyle aspirations, and growing interest in international destinations. Business travel remains strong due to global trade participation and frequent corporate engagements. VFR travel supports consistent movement, especially to countries with significant Indian diaspora. It reflects cultural ties and seasonal travel patterns that influence outbound flows across key regions.
- For instance, Thomas Cook India and SOTC Travel reported in their 2025 India Holiday Report that 85% of surveyed Indians plan to double their holiday frequency, with 84% considering spending 20–50% more on travel this year.
By Booking Channel
Online Booking leads this segment in the India outbound tourism market due to widespread internet access, mobile penetration, and the rise of digital travel platforms. Travelers prefer the convenience, price comparison, and instant confirmation that online channels provide. Phone Booking continues to serve older travelers and corporate clients, while In-person Booking holds relevance for high-value or complex itineraries. It still appeals to customers seeking personalized consultation, especially in smaller cities and niche markets.
- For instance, Booking.com reported that the majority of its bookings from India now come from outbound and domestic travelers using its online platform, reflecting a significant shift from earlier trends focused on inbound travel.
By Tourist Type
International tourists form the core of the India outbound tourism market, reflecting strong demand for overseas travel across business, leisure, and education sectors. The segment sees growth from urban, high-income, and millennial travelers. While Domestic tourism is not a direct focus here, some outbound behavior links to cross-border regional movement within South Asia. It highlights the market's diverse traveler base and evolving expectations across various travel types and destinations.
Segments:
Based on Purpose Type:
- Business
- Holiday/Leisure
- VFR & Others
Based on Booking Channel:
- Phone Booking
- Online Booking
- In-person Booking
Based on Tourist Type:
- Domestic
- International
Based on Tourism Type:
- Cultural and Heritage Tourism
- Medical Tourism
- Eco/Sustainable Tourism
- Sports Tourism
- Wellness Tourism and Others
Based on Tour Type:
- Independent Traveller
- Package Traveller
- Tour Group
Based on Consumer Orientation:
- Men
- Women
Based on Age Group:
- 15 to 25 Years
- 26 to 35 Years
- 36 to 45 Years
- 46 to 65 Years
- 66 to 75 Years
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Asia-Pacific
Asia-Pacific holds the highest share in the India outbound tourism market at 44%. Proximity, cultural familiarity, affordable travel costs, and favorable visa policies drive consistent traffic to destinations such as Thailand, Singapore, Malaysia, and the UAE. Indian tourists prefer Asia-Pacific for leisure, shopping, and short-haul getaways. Frequent business interactions with Southeast Asian economies also boost corporate travel. The region benefits from strong air connectivity and aggressive tourism promotion targeting Indian travelers. It remains the preferred choice for both first-time and frequent outbound tourists.
Europe
Europe accounts for 32% of the India outbound tourism market. Its historical attractions, luxury experiences, and educational institutions attract a wide range of Indian travelers. Countries like the UK, France, Switzerland, and Italy witness steady inflow for leisure, higher education, and VFR travel. Schengen visa access simplifies multi-country tours, while seasonal packages drive high-volume travel during summer and festive breaks. The growing Indian diaspora in Western Europe also supports family visits. Europe continues to position itself as a premium travel destination for affluent and urban Indian tourists.
North America
North America holds 18% share of the India outbound tourism market. The United States and Canada see strong demand driven by education, family visits, and business travel. Indian students form a significant outbound segment, often accompanied by relatives for short-term stays. Long-haul leisure trips to popular cities and national parks are gaining traction among high-income groups. Strong diaspora presence supports repeat travel and seasonal spikes. Visa challenges and higher costs moderate volume growth, but the region retains high revenue per traveler.
Rest of the World
The Rest of the World contributes 6% to the India outbound tourism market. Destinations in Africa, Oceania, and South America are emerging slowly as niche interests rise. Safari tourism, eco-tourism, and long-haul cruises attract affluent and adventurous travelers. Marketing efforts and relaxed visa norms could boost future volumes.
Key Player Analysis
- TCI
- Riya Travels
- BTI Sita
- Thomas Cook
- Travelmart India
- Kesari
- Orbit
- SOTC Kuoni
- Raj Travels
- Amadeus
- Cox and Kings
- In Orbit Tours
Competitive Analysis
The India outbound tourism market features a competitive landscape marked by the presence of both legacy players and agile new entrants. Companies like Thomas Cook, SOTC Kuoni, Cox and Kings, and TCI have established strong brand recognition and international networks. They offer end-to-end travel solutions, including packages, visa assistance, insurance, and foreign exchange. Emerging firms and digital-first platforms are capturing younger, tech-savvy travelers by offering flexible, personalized, and cost-efficient itineraries. The market also includes niche players like Kesari and Raj Travels, which specialize in group tours and curated experiences. Orbit, Travelmart India, and In Orbit Tours serve diverse travel needs across business, leisure, and VFR segments. Riya Travels and Amadeus leverage strong backend systems and global partnerships to enhance travel booking infrastructure. The India outbound tourism market encourages innovation, competitive pricing, and service differentiation, compelling players to adapt quickly to evolving consumer expectations and shifting global travel dynamics.
Recent Developments
- In June 1, 2025, IndiGo signed an MoU with Delta Air Lines, Air France‑KLM, and Virgin Atlantic to enhance air connectivity between India, Europe, and North America.
- In June 23, 2025, the Los Angeles Tourism Board launched a dedicated “Travel Trade Hub” for Indian travel agents, offering exclusive itineraries, training modules, and marketing tools.
- In June 27, 2025, Thomas Cook India and SOTC Travel introduced the Monsoon Holidays 2025 packages, featuring buy-one-get-one-free offers and promotional discounts.
- In June 2, 2025, Air India and Icelandair entered a codeshare agreement to simplify travel bookings and strengthen connectivity between India and Europe.
Market Concentration & Characteristics
The India outbound tourism market exhibits moderate to high market concentration, with a mix of established players and emerging service providers competing across diverse travel segments. A few dominant firms like Thomas Cook, SOTC Kuoni, and Cox and Kings hold substantial market share due to their international networks, brand recognition, and comprehensive service portfolios. At the same time, digitally native platforms and regional operators are gaining traction by targeting younger travelers and offering customized, experience-led itineraries. The market is highly seasonal, driven by school vacations, festivals, and weather patterns in destination countries. It is also characterized by price sensitivity, strong reliance on digital engagement, and growing demand for experiential and value-based travel. Travel decisions are influenced by visa policies, exchange rates, and safety perceptions. The India outbound tourism market reflects fast-evolving consumer preferences, rising demand from Tier-II cities, and an increasing shift toward multi-purpose travel combining leisure, business, education, or medical needs.
Report Coverage
The research report offers an in-depth analysis based on Purpose Type, Booking Channel, Tourist Type, Tourism Type, Tour Type, Consumer Orientation, Age Group and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Travelers will prioritize customized, experience-rich vacations over traditional sightseeing group packages and rigid itineraries.
- Wellness retreats, eco-tourism, and adventure trips will attract health-conscious and thrill-seeking Indian outbound tourists.
- Rising incomes in Tier-II and Tier-III cities will drive significant growth in outbound travel demand.
- Online platforms and mobile apps will streamline bookings, itineraries, and destination discovery for all travelers.
- Simplified visa rules and faster processing will strongly influence destination selection among Indian tourists.
- Companies will diversify offerings to target students, medical tourists, and corporate travelers with tailored packages.
- Low-cost carriers and airline alliances will improve affordability and access to non-traditional global destinations.
- Currency exchange fluctuations and inflation may impact travel plans and destination affordability for Indian tourists.
- Social media influencers and travel bloggers will continue to guide travel trends and destination preferences.
- Travelers will seek destinations offering flexibility, safety protocols, and hygiene assurance in post-pandemic environments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the India outbound tourism market?
What are the key segments within the India outbound tourism market?
What are some challenges faced by the India outbound tourism market?
Who are the major players in the India outbound tourism market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 India Outbound Tourism Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global India Outbound Tourism Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 187,975 million → 2032: USD 439,479.6 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 India Outbound Tourism Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. India Outbound Tourism Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 India Outbound Tourism Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 India Outbound Tourism Market Drivers
- 3.3 India Outbound Tourism Market Restraints & Challenges
- 3.4 India Outbound Tourism Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 India Outbound Tourism Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 India Outbound Tourism Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, India Outbound Tourism category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 India Outbound Tourism Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. India Outbound Tourism Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the India Outbound Tourism market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 India Outbound Tourism Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 India Outbound Tourism Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 India Outbound Tourism Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in India Outbound Tourism (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New India Outbound Tourism Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global India Outbound Tourism Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America India Outbound Tourism Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe India Outbound Tourism Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific India Outbound Tourism Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America India Outbound Tourism Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East India Outbound Tourism Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa India Outbound Tourism Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. India Outbound Tourism Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
