
Carabeef, not cow beef, carries the domestic market
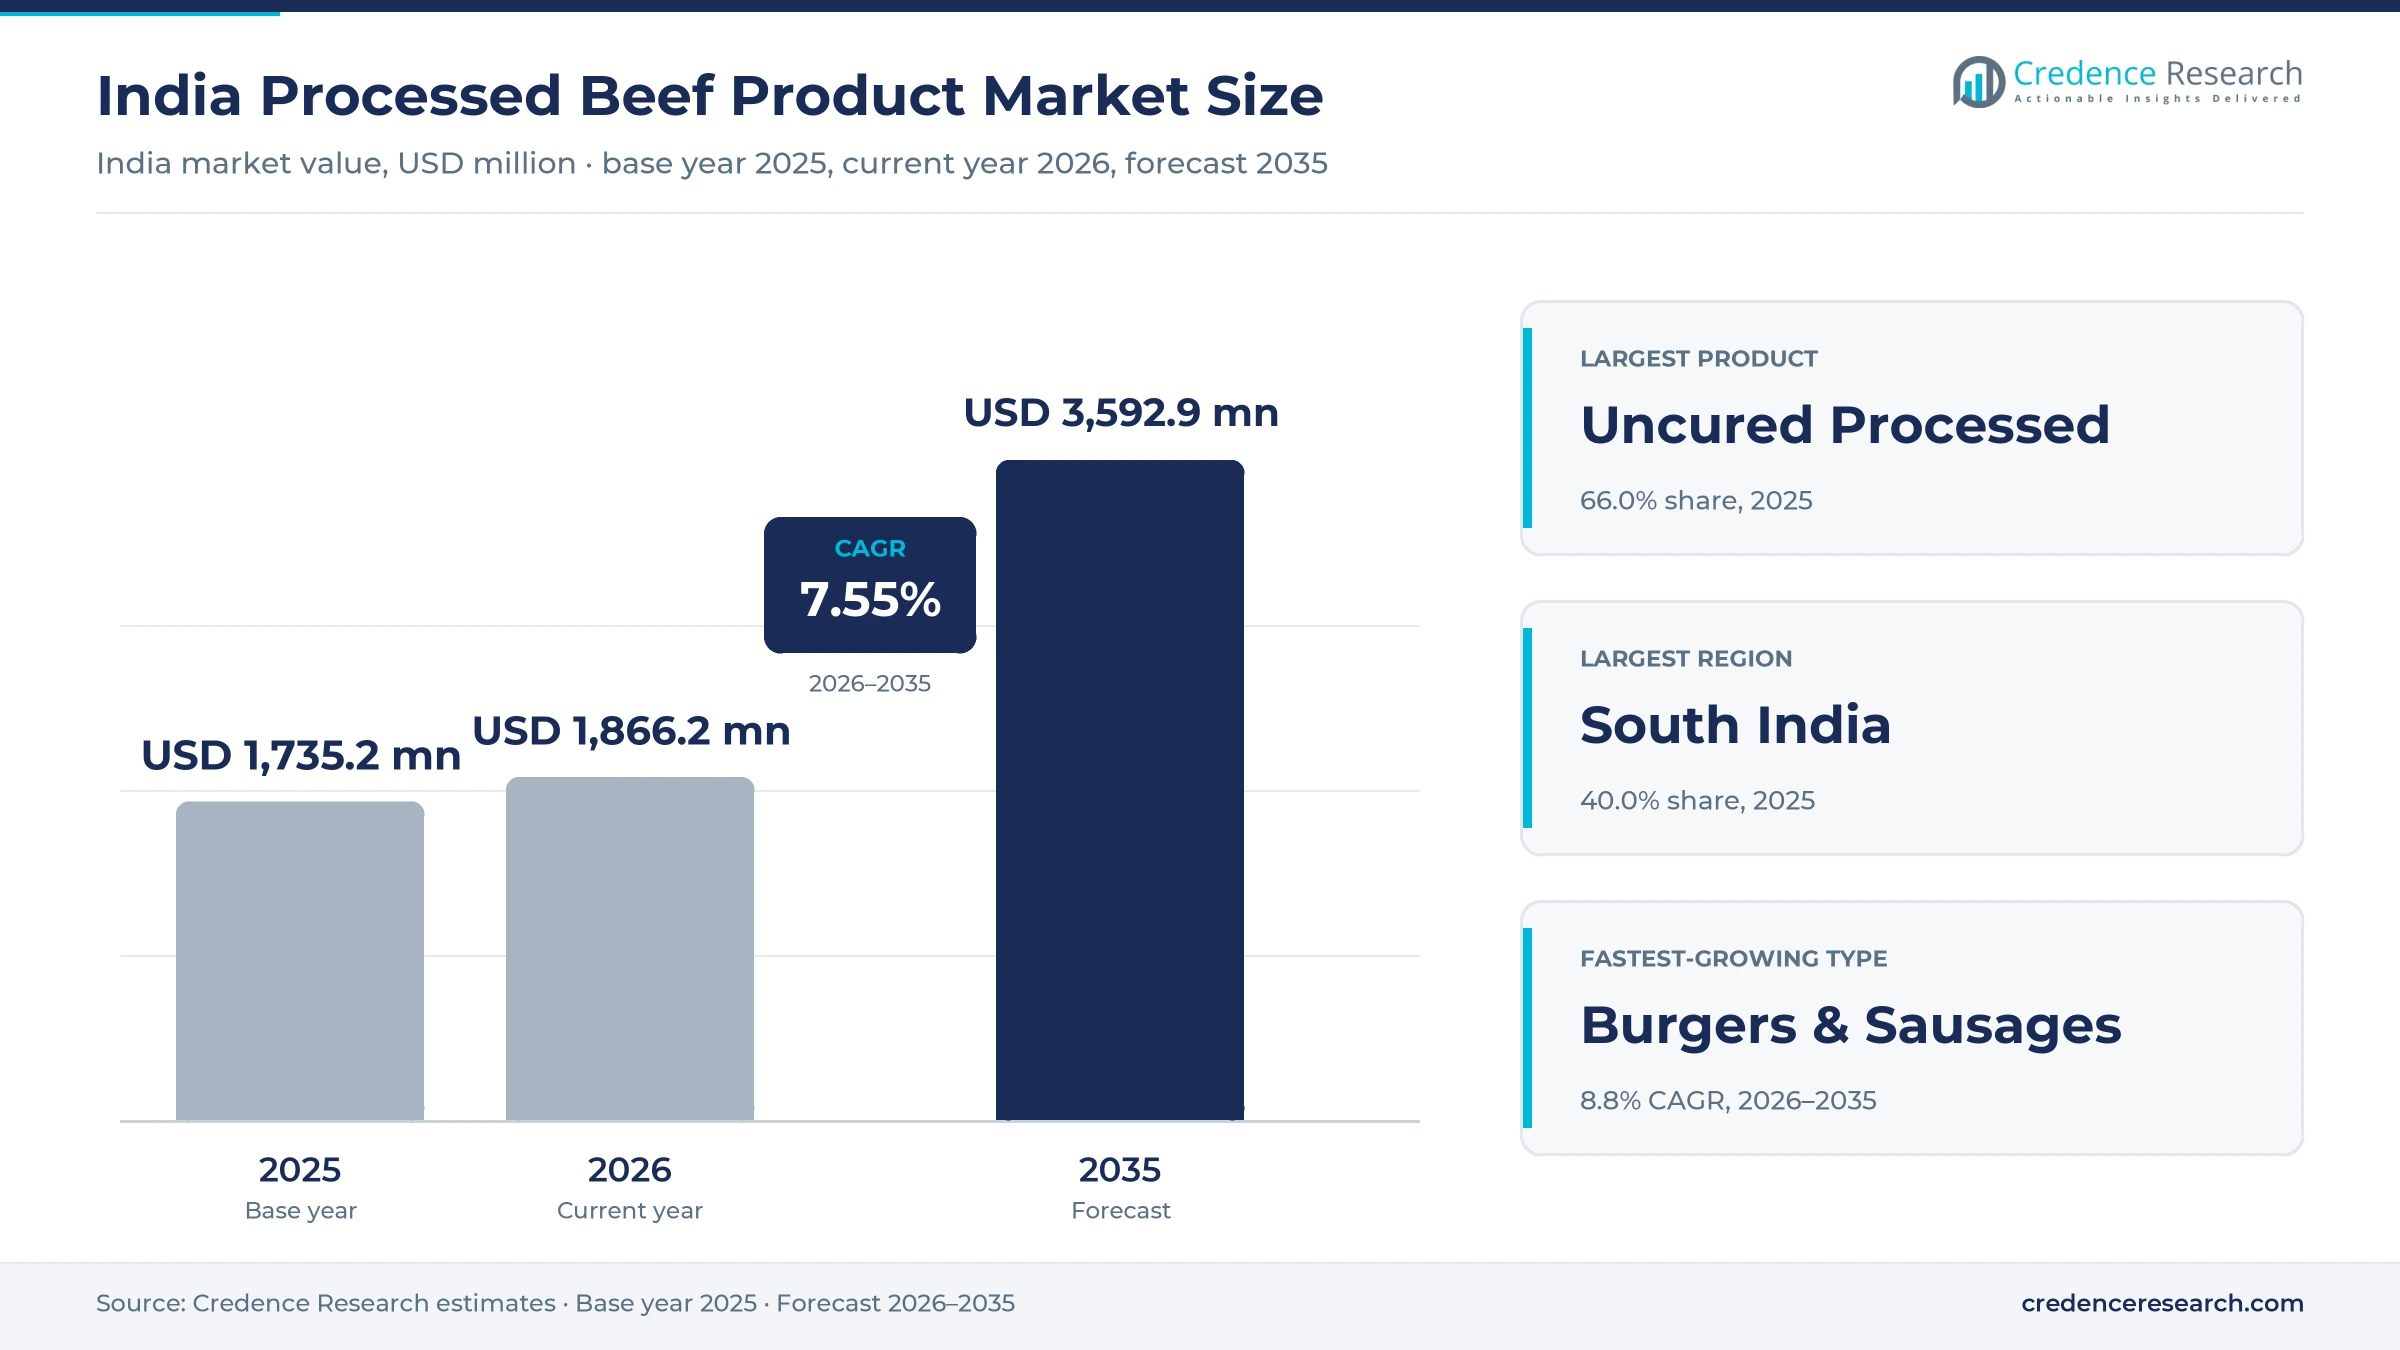
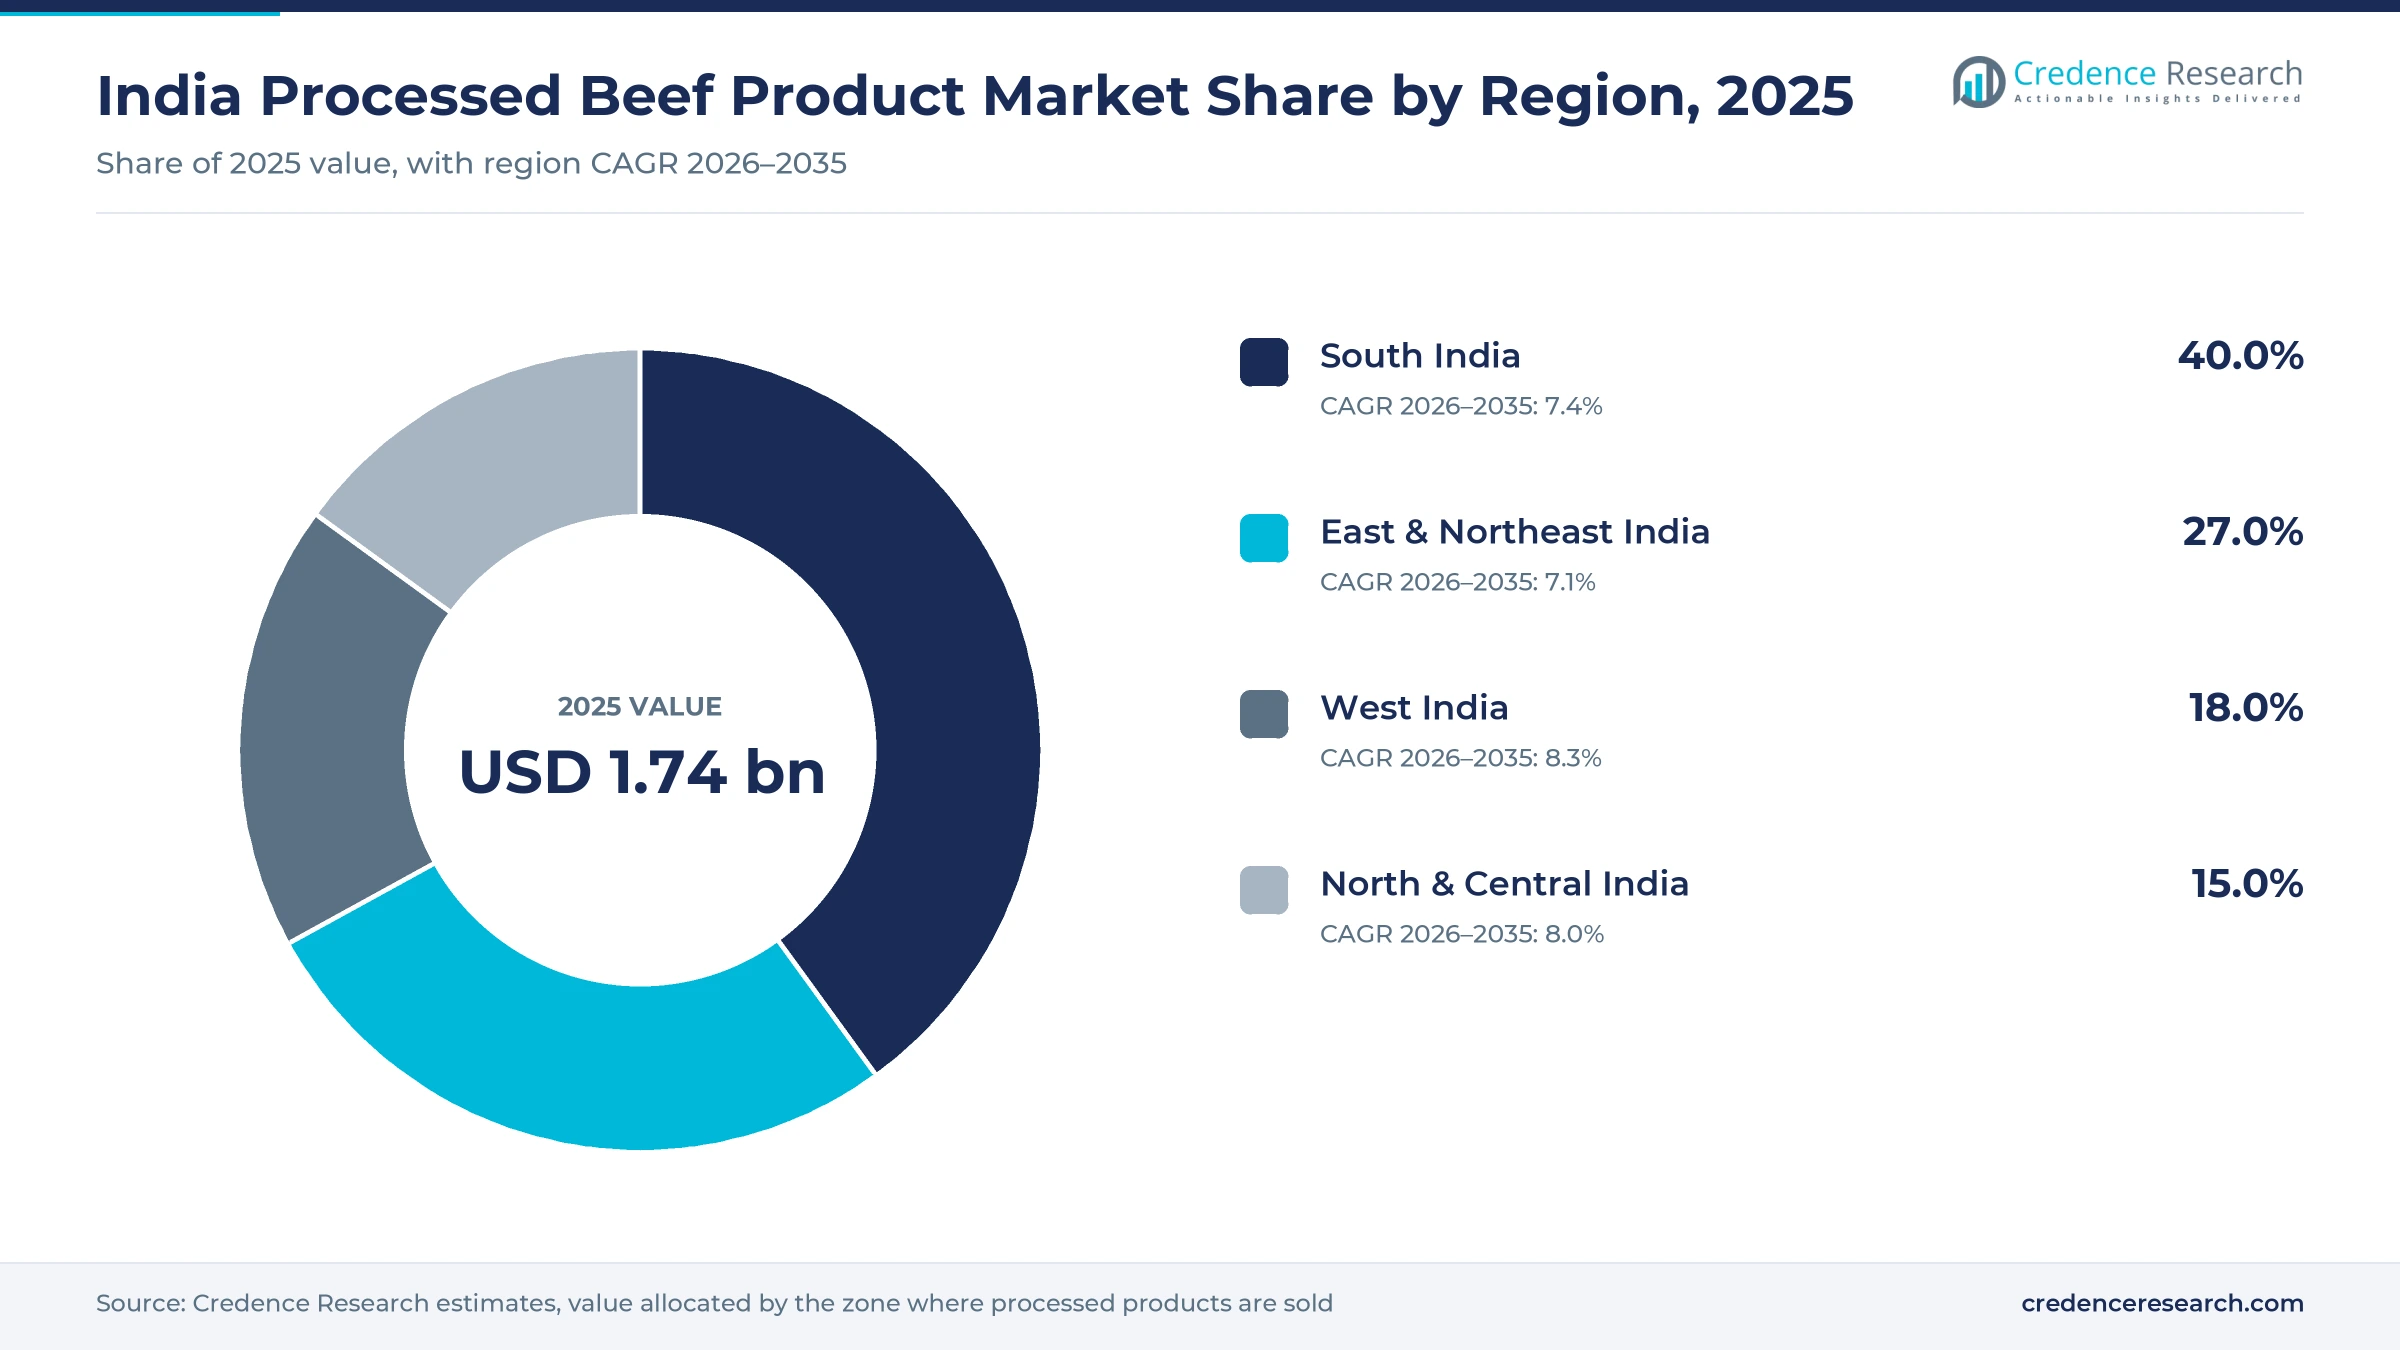
The India processed beef product market was valued at USD 1.74 billion in 2025 and is projected to increase from USD 1.87 billion in 2026 to USD 3.59 billion by 2035, registering a CAGR of 7.55% during 2026–2035. The market counts processed bovine meat sold inside India, and most of it is carabeef, the meat of water buffalo, because cow slaughter is banned or restricted in most states. Hotels, restaurants, caterers and urban households buy deboned frozen cuts, sausages, cured meats and marinated packs from integrated abattoirs and regional processors. South India held the largest share, 40.0% in 2025, as Kerala and Telangana keep beef on everyday menus and host nearby plants. West India is the fastest-growing region at 8.3% a year, helped by Mumbai food service and new ready-to-cook capacity in Maharashtra. A lower goods and services tax on preserved and processed meat since September 2025 narrows the price gap with fresh stall meat. Cattle supply shortages and state transport controls, however, keep raw material costs volatile.
Buffalo meat cuts, cured lines and ready meals define scope
The estimate measures what Indian buyers pay for bovine meat that has been deboned and chilled or frozen, cured, smoked, minced, formed into burgers or sausages, marinated or cooked before sale. It covers carabeef and, in states where cattle slaughter is legal, such as Kerala and West Bengal, cattle meat, sold through food service, packaged retail and online channels. Beef from cows can legally be bought in Kerala and several northeastern states, and in West Bengal from animals certified fit for slaughter, while buffalo meat is legal in many states that ban cow slaughter.
The estimate excludes fresh carcass meat cut and sold the same day by local butchers, live animals and meat exported from India. Export of beef from cows, oxen and calves is prohibited, and only buffalo meat in specified frozen or chilled forms leaves the country through registered plants. Value flows from farmers who sell spent buffaloes through traders to integrated abattoirs and processors, then to distributors, cold stores, food service buyers and retailers.
India Processed Beef Product Market Insights
- The India processed beef product market grows from USD 1.74 billion in 2025 to USD 3.59 billion by 2035 at a 7.55% CAGR, as more carabeef reaches buyers in chilled, frozen and value-added form.
- South India held 40.0% of 2025 value, because Kerala and Telangana combine everyday beef demand with nearby deboning and freezing plants.
- Uncured processed meat led product types with 66.0% of 2025 value, because deboned frozen and chilled carabeef is what integrated plants are built to produce.
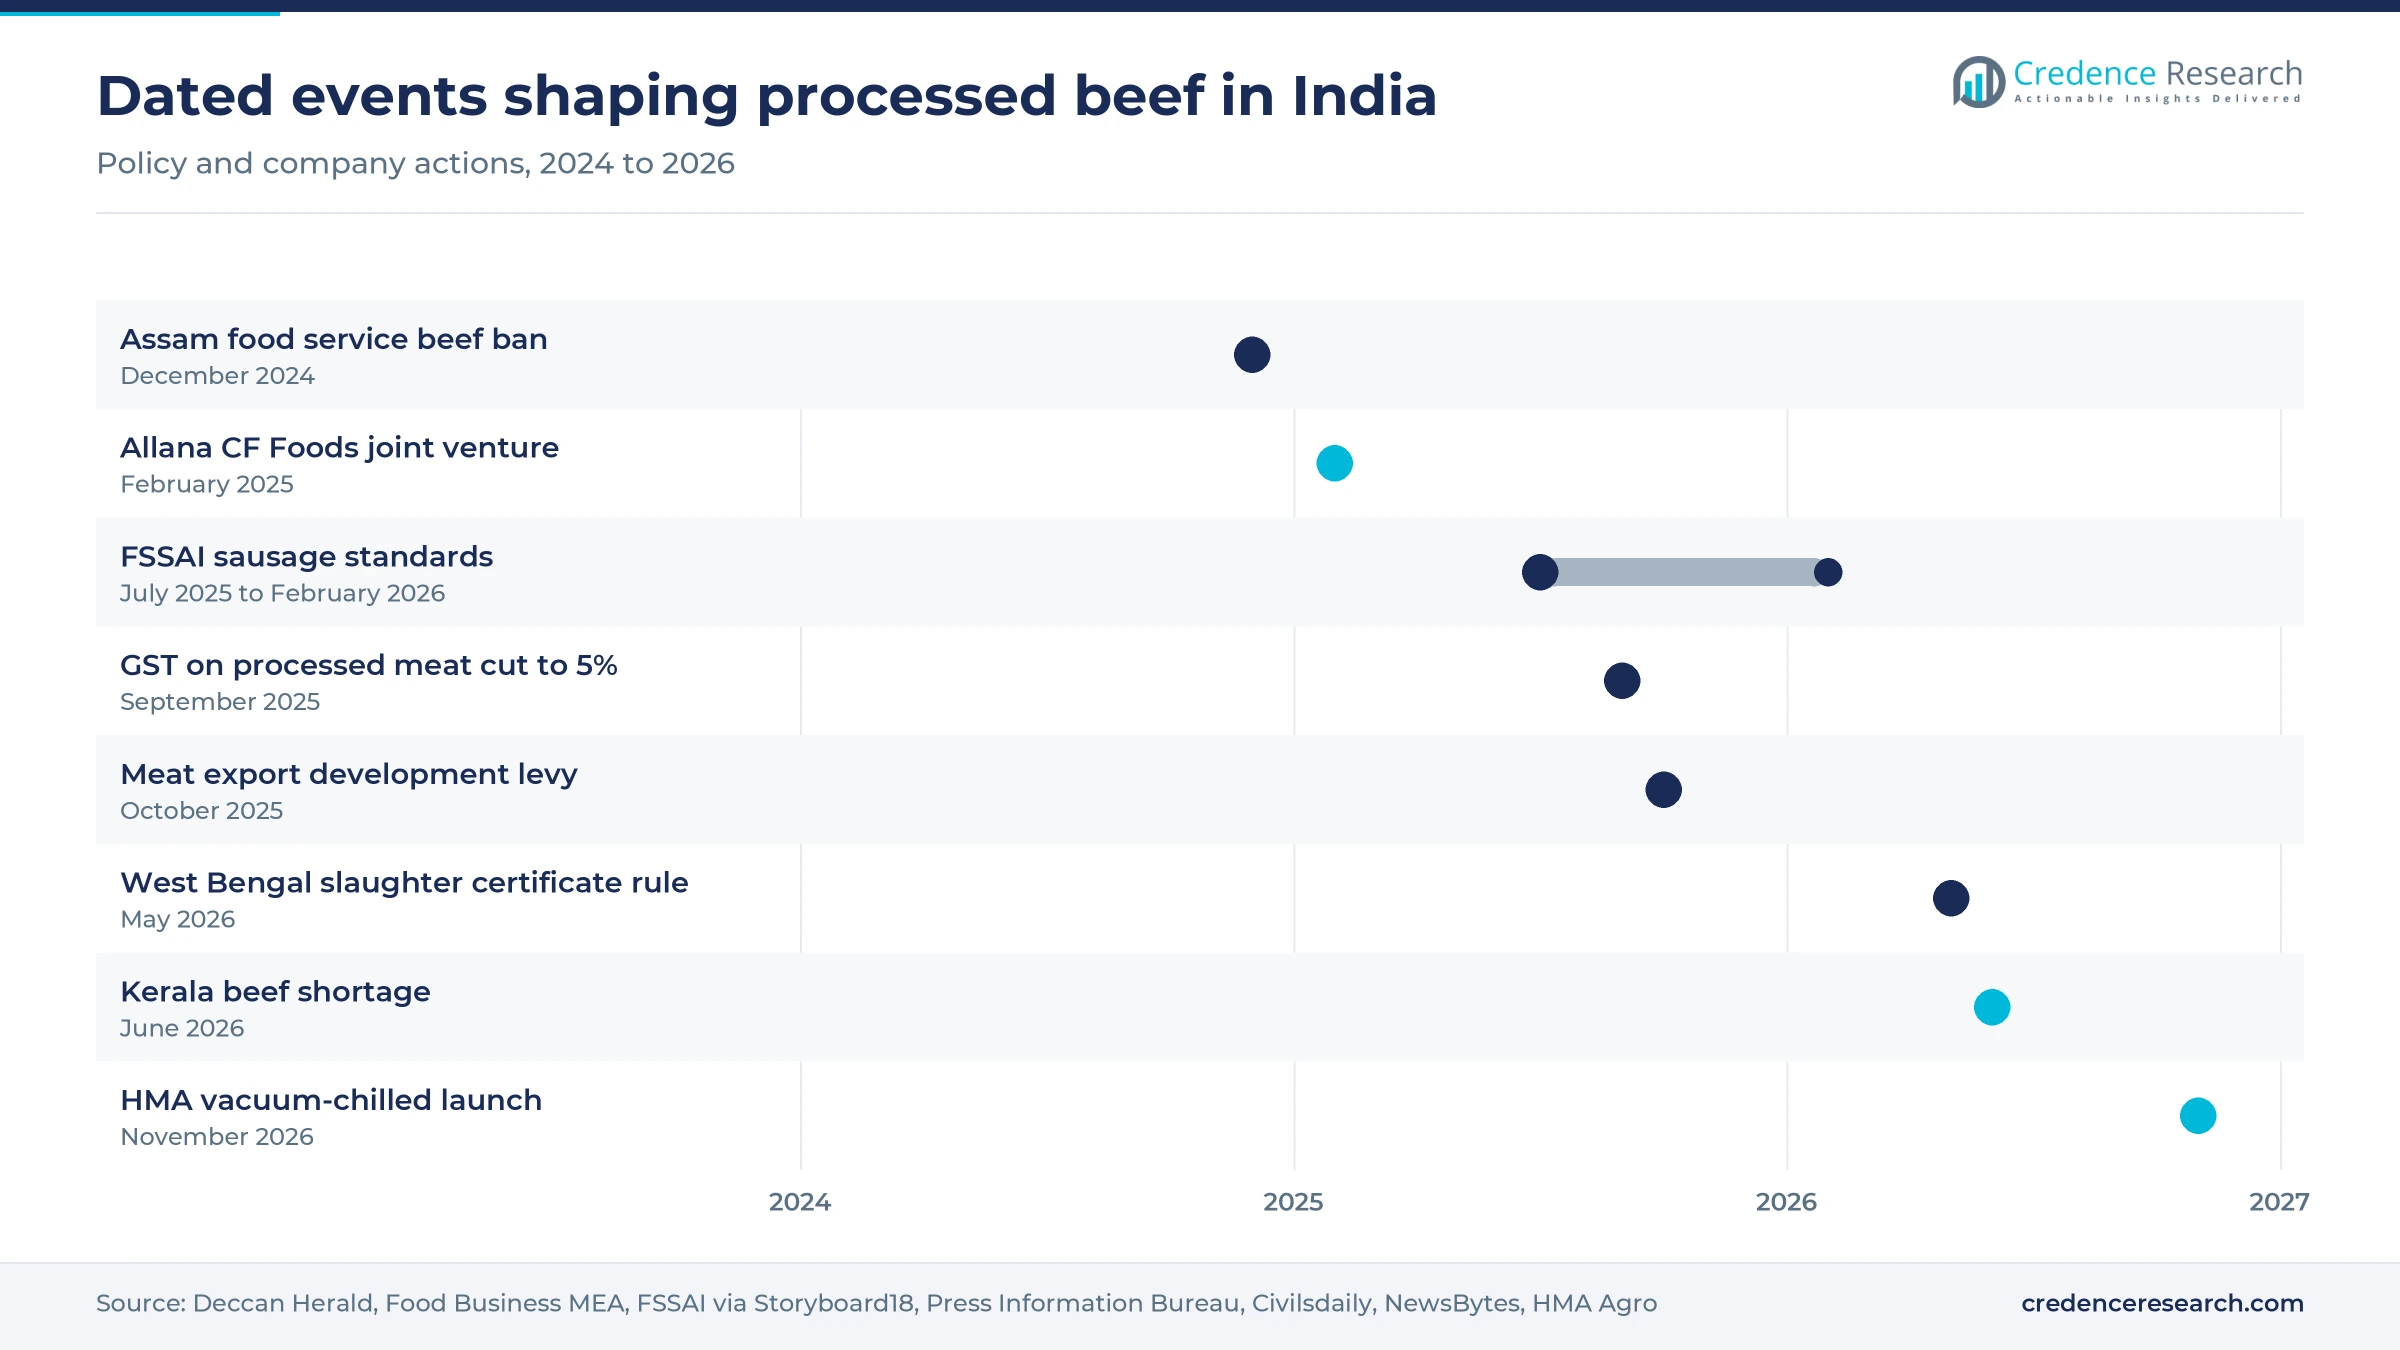
- The goods and services tax on sausages and other prepared or preserved meat fell from 12% to 5% under the September 2025 rate rationalization, according to the Press Information Bureau.
- Buffalo meat exports reached USD 5.1 billion in fiscal 2025-26, a level that sits outside this domestic market but sets the price and capacity base that home buyers draw on.
Uncured carabeef leads while sausages grow fastest
Uncured carabeef leads while ready-to-cook packs grow fastest
Based on product, the market is categorized into uncured processed, cured processed and marinated and ready-to-cook products. Uncured Processed led with 66.0% of 2025 value because integrated plants are built to debone, chill and freeze carabeef rather than cure it. India has 83 integrated abattoir-cum-processing plants registered with APEDA, the export promotion agency, Civilsdaily reported in 2026. Those plants also sell restaurant buyers the frozen boneless cartons they pack for export. Marinated & Ready-to-Cook grows fastest at 8.6% a year, as processors add cooking lines. Chatha Foods and Frigorifico Allana formed Allana CF Foods in February 2025 to build a 6,000-metric-ton-a-year ready-to-cook and ready-to-eat meat plant at Aurangabad.
Whole cuts lead as burgers and sausages grow fastest
Based on type, the market is categorized into beef meat, mechanically recovered meat, burgers and sausages and offal and by-products. Beef Meat led with 72.0% of 2025 value because food service kitchens buy boneless cuts for curries and biryani. Those kitchens rarely buy minced or formed product, which keeps mechanically recovered meat and burgers a small share of value. Burgers & Sausages grows fastest at 8.8% a year from a small base, as the lower tax and new FSSAI meat content rules favor registered sausage makers over informal producers. Fresh, cooked and fermented sausages must carry at least 50%, 60% and 65% meat under FSSAI sausage standards due to take effect on Feb. 1, 2026.
Fresh packs lead while vacuum packs grow fastest
Based on packaging, the market is categorized into fresh meat packaging, vacuum packaging and modified atmosphere packaging. Fresh Meat Packaging led with 55.0% of 2025 value because plants ship most chilled carabeef to hotels, caterers and distributors as wrapped primal cuts and bulk cartons rather than sealed retail packs. Buyers that cook within days see little value in paying for vacuum film, so the cheapest wrap wins in food service. Vacuum Packaging grows fastest at 8.2% a year, as retailers seek longer shelf life. HMA Agro said in November 2026 that it had launched vacuum-chilled meat aimed at hypermarket and supermarket demand.
Food service leads while online sales grow fastest
Based on distribution channel, the market is categorized into food services, retail and e-commerce. Food Services led with 47.0% of 2025 value because restaurants, hotels and caterers buy frozen boneless carabeef in bulk cartons. Allana Consumer Products, part of the Allana Group, announced in July 2026 that it plans to expand its domestic frozen food business for households and hotels, restaurants and cafes, The Hindu reported. E-Commerce grows fastest at 8.7% a year from a small base, as online grocery platforms extend frozen ranges in metro areas. No platform discloses beef volumes, so this rate carries the widest uncertainty.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product | Uncured Processed | 66.0% | Marinated & Ready-to-Cook | 8.6% |
| By Type | Beef Meat | 72.0% | Burgers & Sausages | 8.8% |
| By Packaging | Fresh Meat Packaging | 55.0% | Vacuum Packaging | 8.2% |
| By Distribution Channel | Food Services | 47.0% | E-Commerce | 8.7% |
Raw buffalo cost and tax set processed meat prices
Processed beef prices in India build up from the cost of spent buffaloes, plant yield and freezing cost, then tax and distribution. Raw material dominates, so shortages of animals move prices faster than any processing cost. Kerala retail beef rose to INR 450-500 a kg in 2026, the clearest recent sign of that pressure. Export unit values set the floor that plants expect from domestic buyers, because a carton not sold at home can be shipped abroad. Processed packs now carry 5% tax, which favors branded products over informal meat.
| Price point | Typical price or fee | Basis |
|---|---|---|
| Fresh beef retail, parts of Kerala | INR 300-350 a kg before, INR 450-500 a kg after the 2026 shortage | NewsBytes, June 2026 |
| Frozen buffalo meat export unit value | USD 3,591 a ton in 2025-26, USD 4,392 in April to June 2026 | Commerce Ministry data via Civilsdaily, 2026 |
| Payment to farmer per culled buffalo | About INR 50,000 an animal | Dairy News Today, August 2026 |
| GST on sausages and preserved meat | 5%, down from 12% | Press Information Bureau, September 2025 |
| Export development levy on buffalo meat | INR 250 a ton | APEDA levy from Oct. 29, 2025 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Carabeef supply, lower tax and disease control lift sales
A large carabeef base supplies domestic processing
A large and stable carabeef supply lets processors sell more chilled and frozen product at home without depending on cow slaughter. India's beef production, mostly carabeef, was forecast at 4.64 million metric tons in 2025, up from 4.57 million in 2024, according to the USDA Foreign Agricultural Service, with domestic consumption steady at about 2.99 million tons. Per capita beef consumption was only about 2.2 kg in 2022, Food Business MEA reported from USDA data. With total consumption flat, processors grow by moving more of that volume into deboned, frozen and value-added forms for food service and urban retail, so value rises through mix and price rather than tons, while farmers gain a steady outlet for spent buffaloes.
Export-grade plants push spare capacity into home sales
Integrated plants built for export have spare capacity that they can redirect to domestic chilled and frozen lines. Buffalo meat exports rose 25.6% to USD 5.1 billion in fiscal 2025-26, the first year above USD 5 billion, according to Commerce Ministry data summarized by Civilsdaily. These sales sit outside this market, yet they fund the deboning, chilling and freezing lines that also supply Indian buyers. HMA Agro announced on Nov. 4, 2026, that its plants run at 65% to 70% of capacity, leaving spare capacity that could serve domestic chilled lines. Plants with idle shifts can price domestic cartons at the margin, which helps restaurant buyers but pressures small regional processors.
Lower tax and new standards formalize processed meat
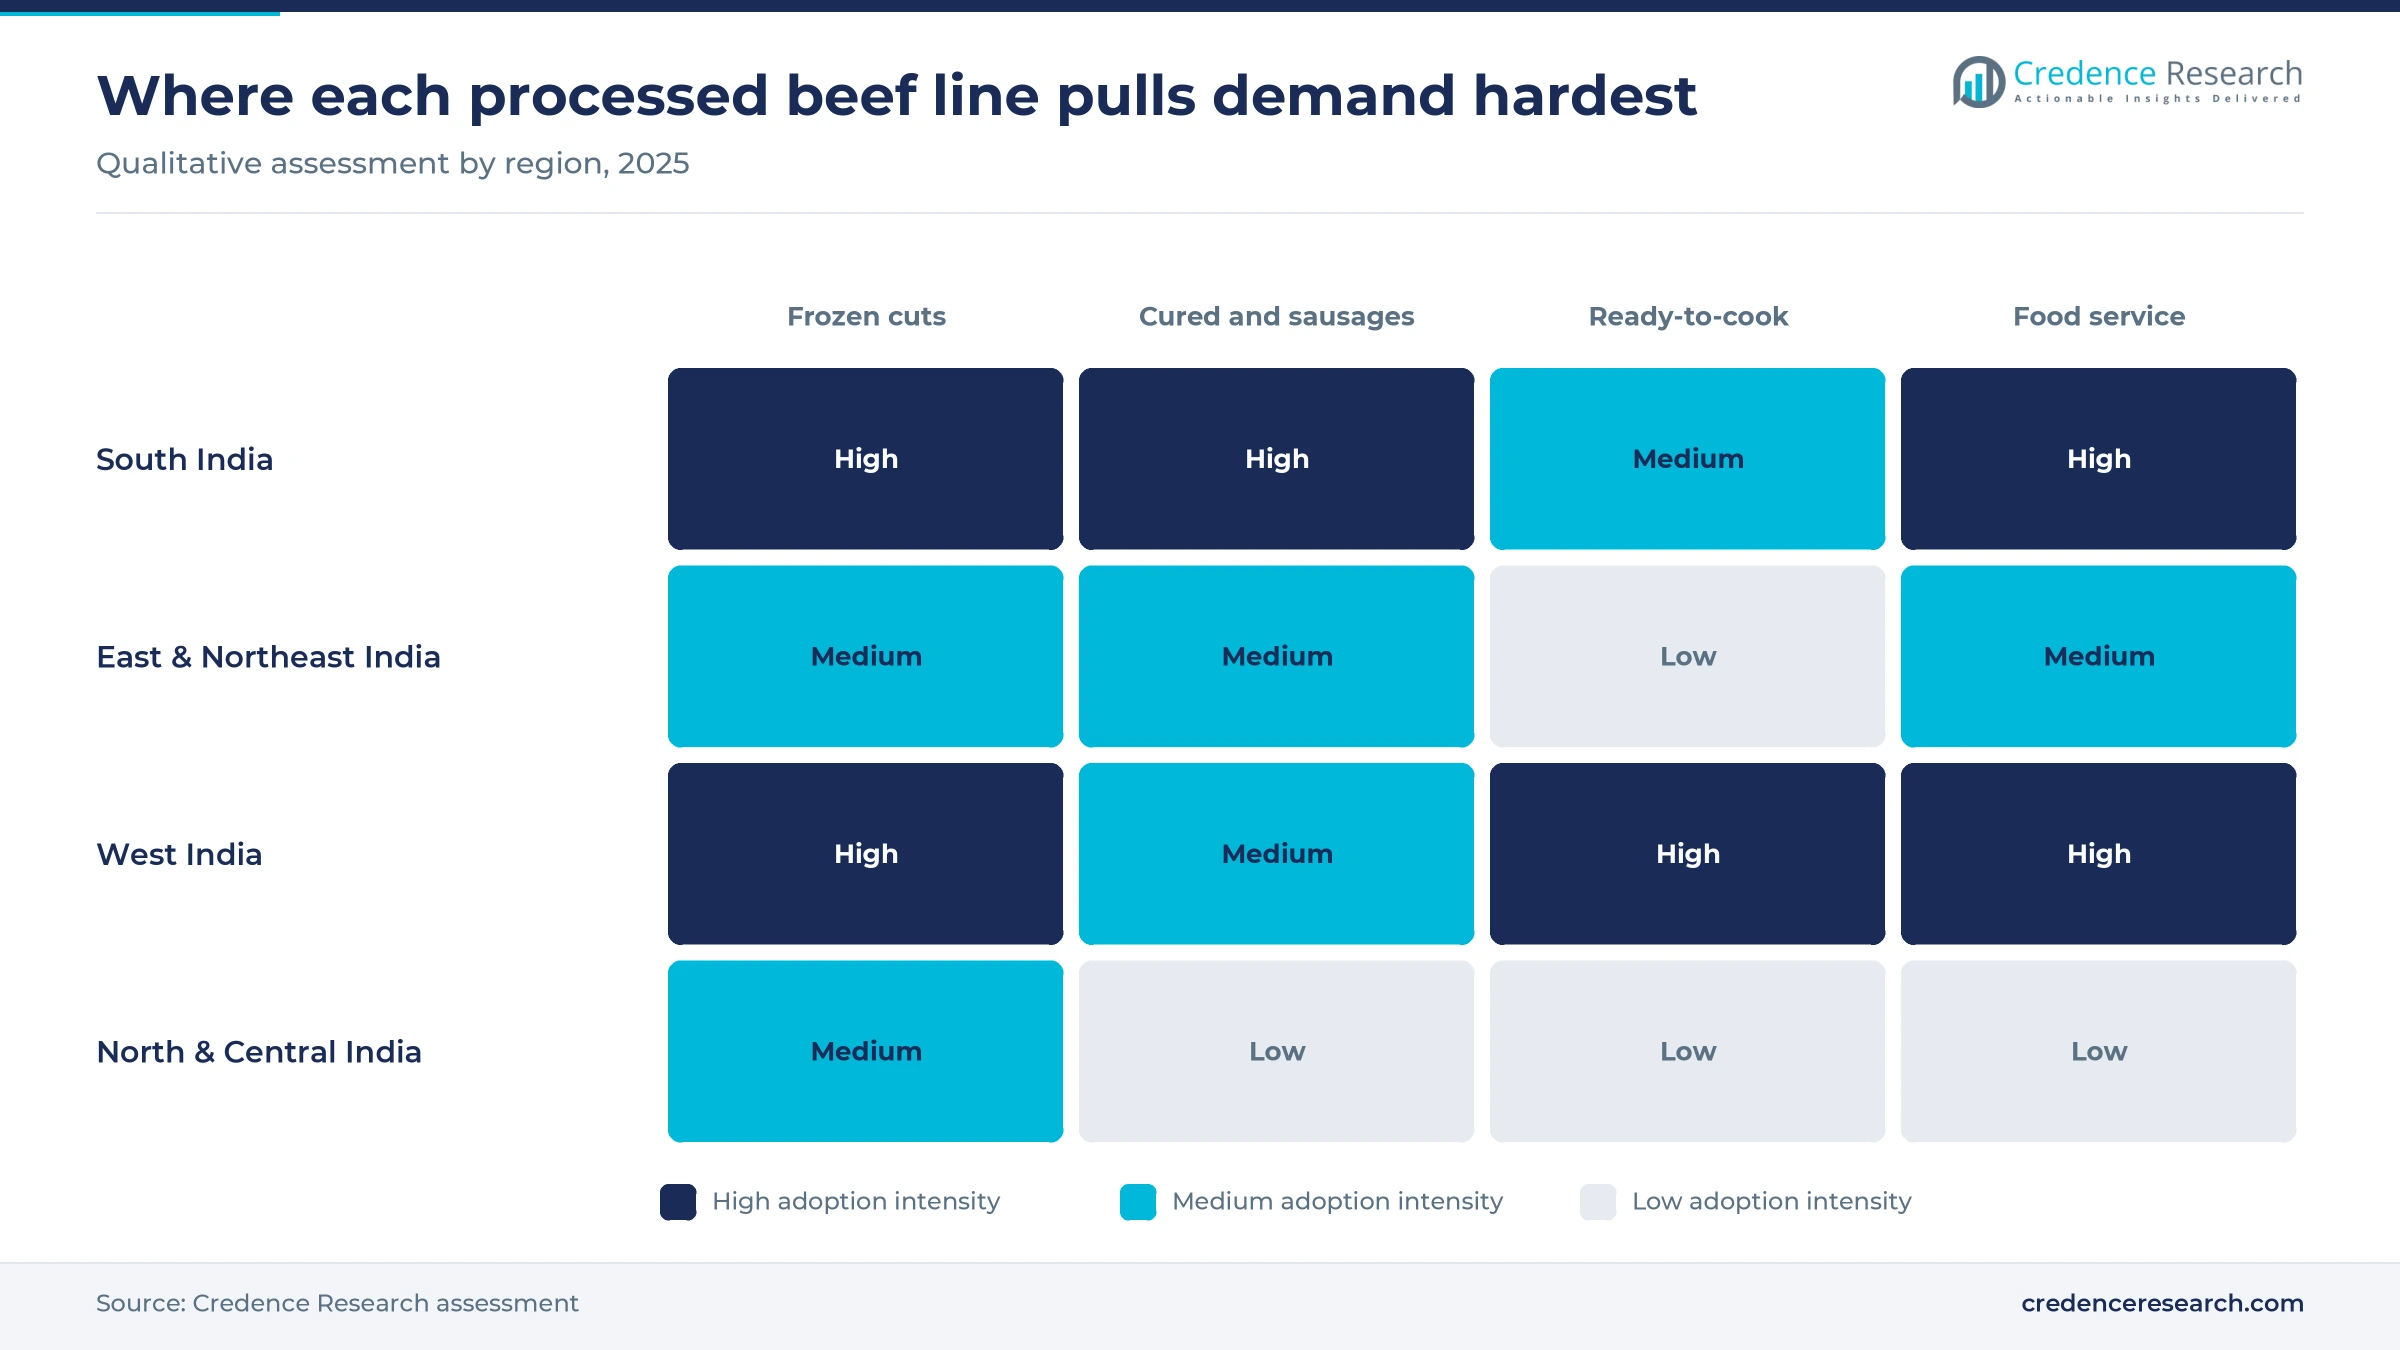
Tax and standards changes are moving processed meat from informal producers toward registered, labeled brands. The goods and services tax on preserved and processed meat such as sausages fell from 12% to 5%, according to the Press Information Bureau, after the GST Council meeting of Sept. 3, 2025. FSSAI notified sausage standards in July 2025 and later gave processors three more months to comply. Meat Products of India, the Kerala government company, is an early beneficiary, since its cured and cooked range now carries the lower rate. Lower tax narrows the price gap with stall meat, while compliance cost falls hardest on small sausage makers without testing capacity.
Disease control steadies herd supply for processors
Better livestock disease control reduces supply shocks for abattoirs and improves the case for value-added lines. India has given 147.16 crore foot-and-mouth disease vaccine doses under the National Animal Disease Control Programme, and reported outbreaks fell from 132 in 2019 to 40 in 2025, Drishti IAS summarized from government data in August 2026. The program targets eradication of the disease across cattle and buffalo herds by 2030. The Livestock Health and Disease Control Programme received INR 2,010 crore for 2026-27, a budget line that supports steady growth in slaughter supply. Fewer outbreaks mean fewer plant stoppages and fewer import bans in key markets, which favors integrated processors that sell both at home and abroad.
Exporters move toward chilled and retail-ready packs
Exporters shift from bulk frozen blocks to retail-ready packs
Large processors are shifting from bulk frozen blocks toward processed and retail-ready buffalo meat, a change that also lifts the quality of product offered at home. Average export value rose from USD 3,236 a metric ton in 2024-25 to USD 3,591 in 2025-26 and USD 4,392 in April to June 2026, Commerce Ministry data show. APEDA introduced a levy of INR 250 a ton on exporters on Oct. 29, 2025, to build a Meat Export Development Fund for promotion and market access work. HMA Agro's vacuum-chilled launch, noted above, points the same way. Processors that master chilled portion packs can sell them to Indian hotels and modern retail, while block-only plants lose pricing power.
Processors shift toward branded cured and cooked ranges
Processors in legal-beef states are shifting toward branded cured, smoked and cooked ranges to earn more than commodity cuts sold through edible meat retail. Meat Products of India markets more than 65 products, including sausages, bacon, ham and meatballs, through supermarkets and cold stores in Kerala and other states, according to its company profile. The FSSAI sausage standard also caps moisture at 60% for cooked or smoked and 50% for dry or fermented sausages, which shifts cured-meat demand toward makers with controlled drying rooms. Allana Consumer Products set out plans in July 2026 to widen its domestic frozen range, The Hindu reported. Brand owners gain margin and shelf space, although they must source carabeef or legal cattle meat with full paperwork in each state they sell into.
Opportunity in chilled carabeef for southern food service
Chilled carabeef from licensed plants is an opening for hotels and restaurants in Kerala, where cattle supply has become unreliable. Kerala consumes about 250,000 tons of beef a year, and beef prices in parts of the state rose from INR 300-350 to INR 450-500 a kg within about a month in 2026, NewsBytes reported in June 2026, a shortage that strengthens the case for frozen carabeef from licensed plants among Kerala restaurant buyers. Plants in Telangana, such as Al Kabeer Exports at Rudraram, sit within reach of southern buyers by refrigerated truck. Processors that offer fixed-price chilled contracts can win restaurant accounts that once relied on trucked cattle.
Opportunity in halal portion packs for nearby importers
Retail-ready halal packs give processors a second outlet that keeps plants busy and lowers the unit cost of domestic lines. Vietnam, Malaysia, Egypt, Saudi Arabia and the UAE each bought more than USD 100 million of Indian buffalo meat in 2025-26, and newer buyers include Uzbekistan, Russia, Georgia and Senegal, Dairy News Today reported in August 2026. Indonesia planned to import 100,000 tons of buffalo meat in 2025, with Berdikari buying from India since 2018. Rising demand from UAE frozen meat imports rewards plants that pack portions. Plants that sell both abroad and at home spread their fixed cost over more tons.
State slaughter laws and cattle shortages limit supply
State slaughter laws split the market into legal zones
Slaughter laws differ by state, so a product legal in one state can be illegal in the next. Maharashtra has banned slaughter of cows, bulls and bullocks since March 2015, Gujarat's 2017 amendment allows life imprisonment for cow slaughter, and the Uttar Pradesh Prevention of Cow Slaughter Act, 1955, bans the slaughter of cows and the sale of their meat. Kerala and several northeastern states do not ban cow slaughter, and West Bengal allows it for cattle certified fit for slaughter. National brands carry the highest compliance cost, because each pack must prove its species and source.
Assam food service ban removes a beef outlet
Assam closed a large food service outlet for beef when its cabinet resolved on Dec. 4, 2024, to ban serving beef in restaurants, hotels and public places, Deccan Herald reported. The state's 2021 cattle law already barred sales near temples, and violations carry up to eight years in jail and fines of INR 3 lakh to 5 lakh. Restaurants and suppliers in Assam are the most exposed, and the ban raises the political risk of selling into other northeastern states.
Cattle movement controls squeeze southern supply
Southern buyers depend on animals trucked across state borders, and stricter checks along those routes cut supply quickly. Delays with paperwork, seizures and extortion cut weekly cattle truckloads into Kerala by 75% in mid-2026, NewsBytes reported in June 2026, and traders asked for the transport rules that the Supreme Court sought in 2018. Many local beef stalls in Kerala shut during the shortage, cutting retail demand. Small butchers that buy live cattle are the most exposed, while plants with their own buffalo procurement suffer less.
Scarce buffaloes and costly transport cut plant margins
Abattoirs face fewer animals and higher moving costs, which narrows margins on domestic and export product alike. Farmers now receive about INR 50,000 for each culled buffalo, Dairy News Today reported in August 2026, a price that reflects scarcer animals after the milking cycle. Slower checks on interstate livestock trucks, which cut cattle arrivals into Kerala by three quarters in mid-2026 as the challenge above describes, add to the delivered cost of each animal. Plants without contract procurement in villages carry the most raw material risk.
South India leads as West India grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| South India | 0.69 | 40.0% | 7.4% |
| East & Northeast India | 0.47 | 27.0% | 7.1% |
| West India | 0.31 | 18.0% | 8.3% |
| North & Central India | 0.26 | 15.0% | 8.0% |
South India leads on Kerala beef habits and Telangana plants
South India held 40.0% of 2025 value and grows at 7.4% a year. Kerala is the main center of cattle meat production, yet state cattle meat output fell 34% over four years, Factly reported from government survey data, which pushes buyers toward carabeef. Telangana has the highest per capita meat availability in India at 28.8 kg a year across all meats, a figure led by poultry and mutton that signals meat-eating habits rather than beef demand. Al Kabeer Exports runs its APEDA-registered plant at Rudraram in Sangareddy district, giving the zone local deboning and freezing capacity.
East and Northeast rely on West Bengal while Assam tightens
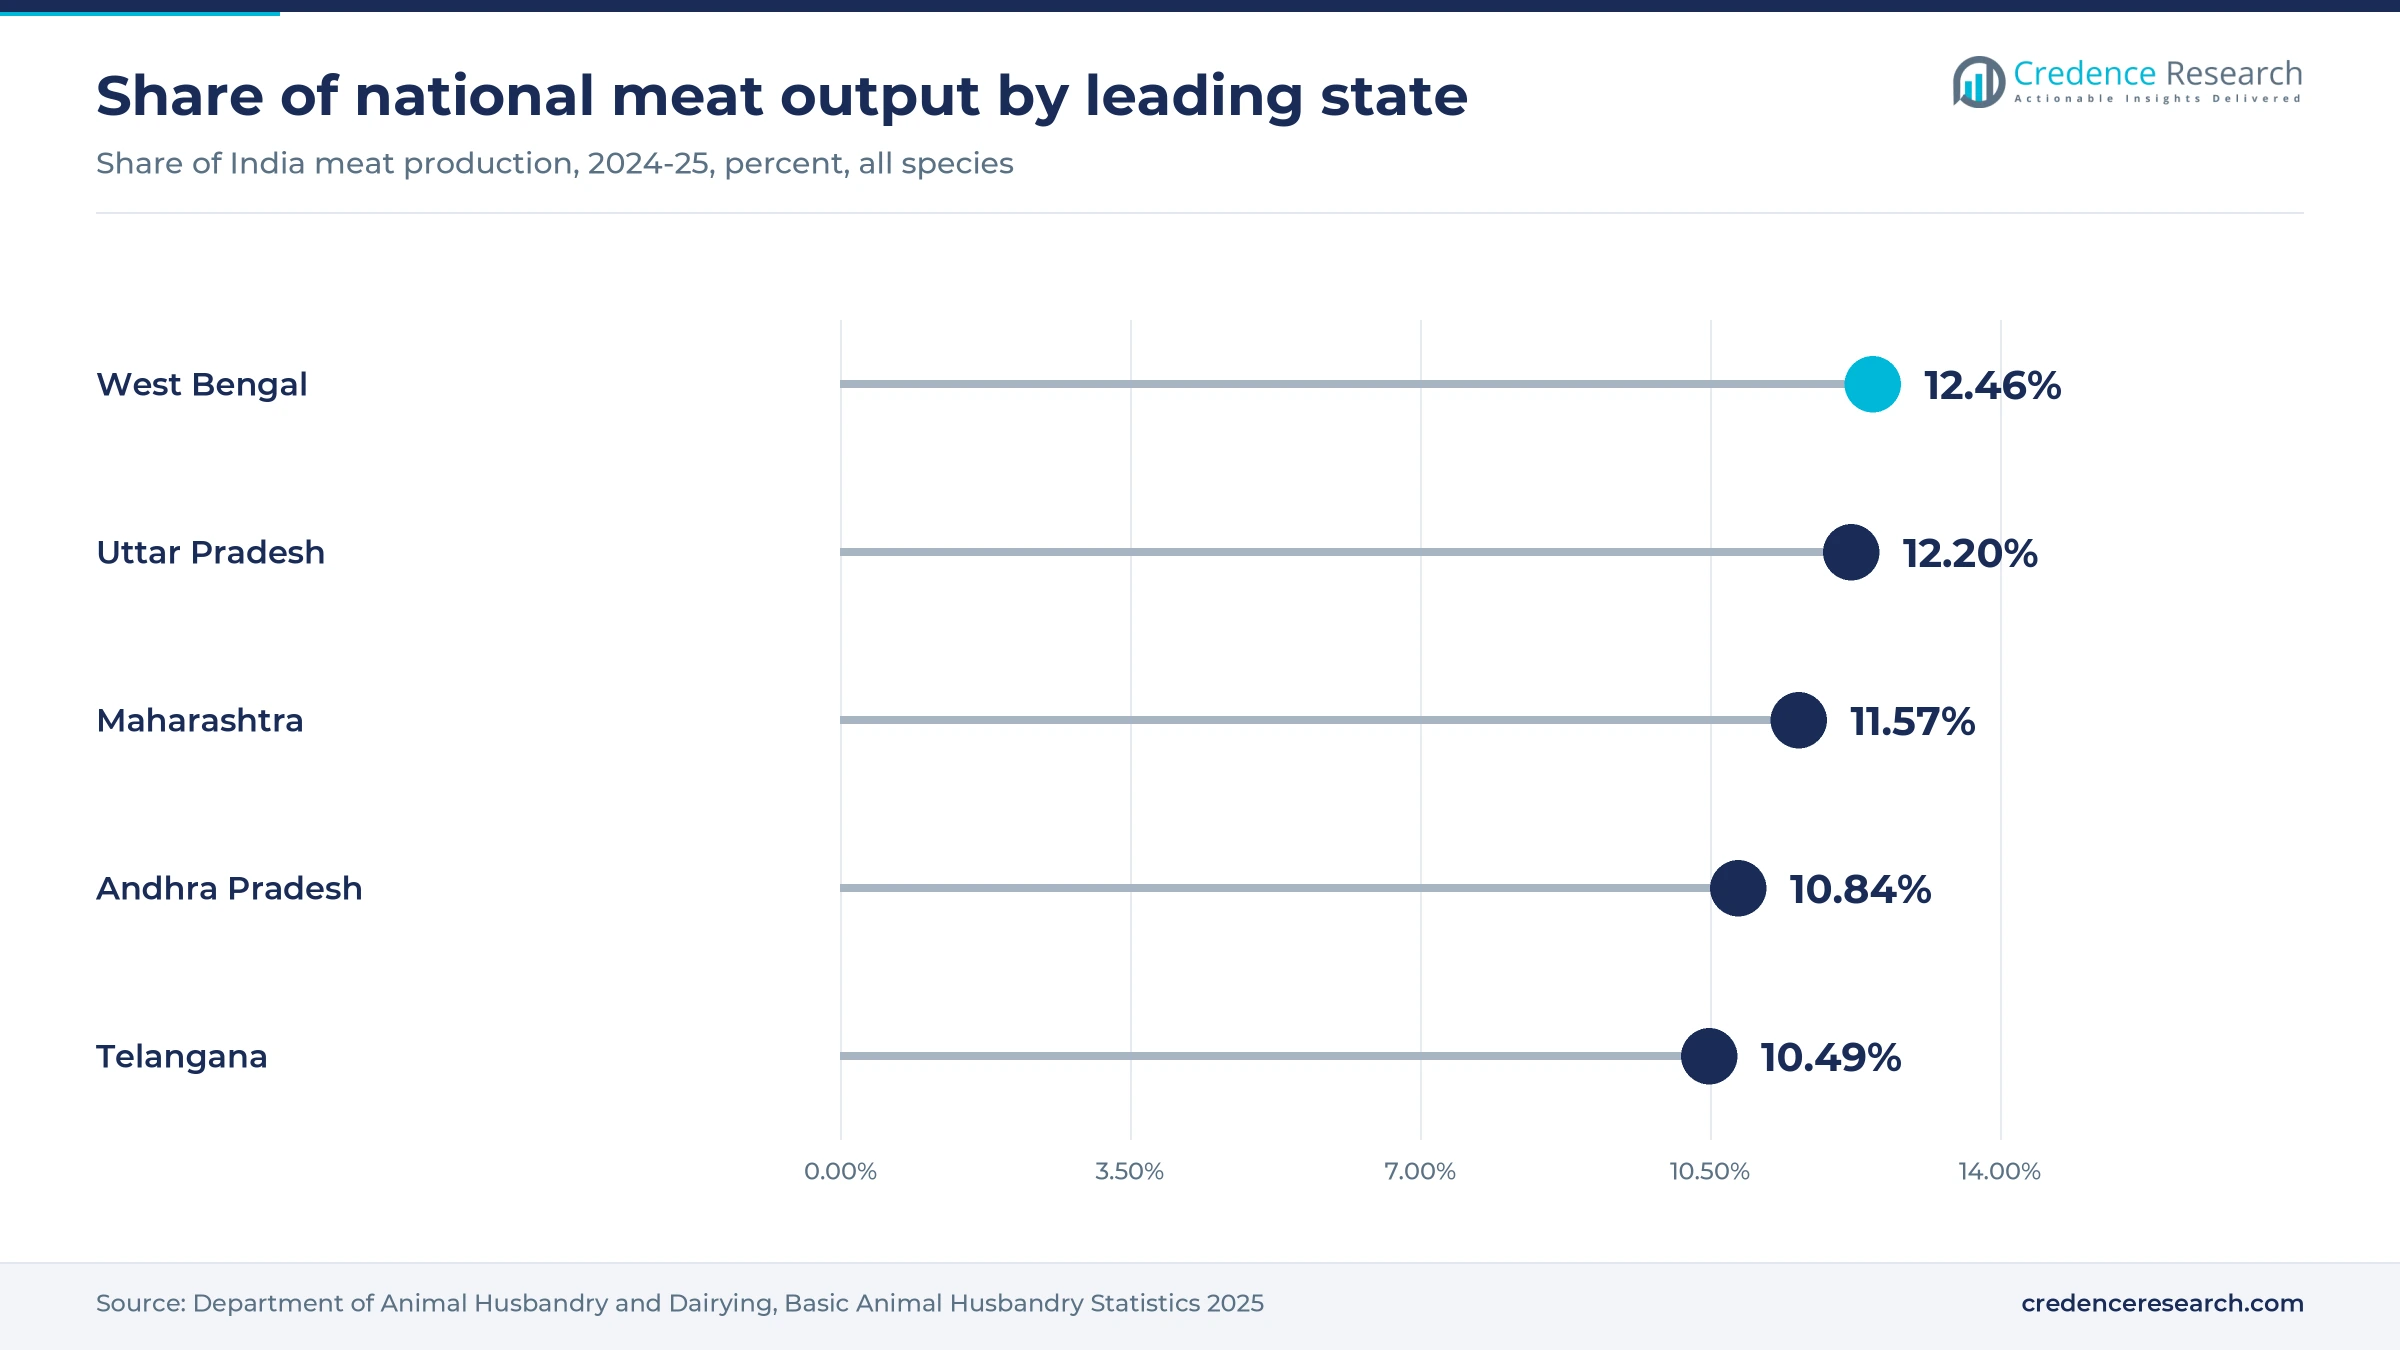
East and Northeast India held 27.0% of 2025 value and grows at 7.1% a year, the slowest pace of the four zones. West Bengal produced 12.46% of national output of all meat, mostly poultry, in 2024-25, the highest of any state, according to Basic Animal Husbandry Statistics 2025 summarized by Rural Voice. West Bengal introduced a notice on May 13, 2026, that limits slaughter of cattle and buffaloes to animals over 14 years old or permanently incapacitated, LiveLaw reported, which tightens supply in the zone's largest market, while the Assam ban described above removes restaurant demand.
West India grows fastest on Mumbai food service and new plants
West India held 18.0% of 2025 value and is the fastest-growing zone at 8.3% a year. Maharashtra produced 11.57% of national output of all meat, mostly poultry, in 2024-25, the largest share in the West India region, and buffalo slaughter remains legal even though bullock slaughter is banned. Mumbai's hotels, caterers and quick service outlets buy frozen carabeef close to home, since the Allana Group is based in the city and Fair Exports runs a plant there. The ready-to-cook joint venture described in the segments adds value-added capacity close to that demand.
North and Central India process most carabeef but sell less
North and Central India held 15.0% of 2025 value and grows at 8.0% a year. Uttar Pradesh supplies about 39% of India's buffalo meat, Factly reported from Department of Animal Husbandry and Dairying data, and hosts HMA Agro plants, Rustam Foods at Unnao and Fair Exports plants, so the zone processes far more than it consumes. Delhi permits buffalo meat but bans the slaughter of agricultural cattle and possession of their meat. Most output leaves for export or southern buyers, which keeps the zone's share of domestic value below its share of production.
Joint ventures, tax cuts and standards reshape processing
| Development | Status and market relevance |
|---|---|
| In February 2025, Chatha Foods and Frigorifico Allana formed Allana CF Foods to build a 6,000-metric-ton ready-to-cook and ready-to-eat meat plant at Aurangabad | Joint venture formed through a stock exchange filing, with operations targeted for October 2025; start of output not yet confirmed |
| In July 2025, FSSAI notified the first amendment of 2025 to food product standards, adding meat content and moisture limits for sausages | Regulation notified, due in force Feb. 1, 2026, with compliance later extended by three months |
| In September 2025, the GST Council cut the tax on preserved and processed meat such as sausages from 12% to 5% | Rate change approved after the GST Council meeting of Sept. 3, 2025, and now in force |
| In May 2026, West Bengal limited slaughter of cattle and buffaloes to certified animals over 14 years old or permanently incapacitated | Government notice issued May 13, 2026, under the 1950 slaughter control act and now being enforced; the Calcutta High Court declined to stay it on May 21, 2026 |
| In November 2026, HMA Agro Industries said it had started vacuum-chilled meat for hypermarkets and supermarkets | Product launch at an early stage, announced on the Nov. 4, 2026, earnings call |
Deboning, chilling and casings set product quality
- Deboning and carcass chilling remove bone and glands and bring meat to safe temperature before cutting, which is the core process in APEDA-registered integrated plants.
- Blast freezing in cartons lets plants hold boneless carabeef for months, which suits restaurant buyers that order in bulk and want stable prices.
- Vacuum and skin packing extends chilled shelf life for retail cuts, and vacuum skin packs also reduce drip loss on display.
- Casings and forming lines shape sausages and burgers, and collagen casings help processors meet the new meat content and texture rules.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Export-grade abattoirs anchor competition at home
Competition in the India processed beef product market sorts suppliers by plant registration, buffalo procurement and access to legal-beef states rather than by brand alone. Allanasons and its Allana Group units run APEDA-listed plants through Frigorifico Allana and Frigerio Conserva Allana and are now building domestic frozen and ready-to-cook lines. HMA Agro Industries runs integrated plants in Uttar Pradesh and is testing vacuum-chilled retail packs. Al Kabeer Exports processes buffalo meat and offal at Rudraram in Telangana, close to southern buyers. Fair Exports, part of the Lulu Group, runs plants in Uttar Pradesh and Mumbai. Rustam Foods supplies fresh and frozen halal boneless buffalo meat from Unnao. Meat Products of India, owned by the Kerala government, leads branded cured and cooked products in the state.
Integrated abattoirs hold scale while local butchers hold volume
Supply in India has two layers that rarely compete head on for the same buyers. APEDA-registered integrated abattoir-cum-processing plants, 83 by 2026, own deboning, chilling and freezing at scale. Below them sit thousands of local butchers that sell same-day fresh meat and dominate fresh meat retail in Kerala and West Bengal. Entry barriers include plant registration, effluent approval and state slaughter permits. Margins sit in portioned, cured and cooked lines, where few players operate. No public data measure concentration, so this view rests on Credence Research estimates.
Processors active in India
| Company | Type | Role in the market |
|---|---|---|
| Allanasons Pvt. Ltd. (Allana Group) | Integrated carabeef processor | Runs integrated plants and is expanding domestic frozen and ready-to-cook food |
| HMA Agro Industries Ltd. | Integrated carabeef processor | Integrated plants in Uttar Pradesh, starting vacuum-chilled packs for modern retail |
| Al Kabeer Exports Pvt. Ltd. | Carabeef and offal processor | APEDA plant 16 at Rudraram, Sangareddy, Telangana |
| Fair Exports (India) Pvt. Ltd. (Lulu Group) | Integrated halal meat processor | Plants in Uttar Pradesh and Mumbai |
| Rustam Foods Pvt. Ltd. | Carabeef processor | Fresh and frozen halal boneless buffalo meat from Unnao |
| Meat Products of India Ltd. | State-owned branded processor | Sells more than 65 meat products, including sausages, bacon and ham, in Kerala |
Legal access by state will decide where volume grows
Credence Research's view is that the domestic market for processed beef will grow where legal access, buffalo supply and cold chains overlap, not evenly across India. Kerala, West Bengal and Mumbai will absorb most new chilled and cooked product, while northern plants keep exporting most of their output. Lower tax and sausage standards favor registered brands over informal makers. The largest risk is political, since a single state cabinet decision can remove a food service outlet overnight. Processors with village procurement and southern distribution will hold margin best.
Consumption, price and plant data drive the estimates
The report on the India processed beef product market uses 2025 as the base year and forecasts value to 2035. Market values come from the Credence Research model, which links bovine meat consumption, the processed share of that consumption and typical prices by product form. The earlier edition's 2023 base was carried to 2025 at its own growth rate and checked against this consumption and price build. Regional, product, type, packaging and channel splits are Credence Research estimates. Sources include government statistics, regulator notices, company disclosures and press reports. No interviews or surveys were used to prepare this edition of the report.
Value-added carabeef carries growth through 2035
Through 2035, demand will rest on food service kitchens in legal-beef states, urban households buying chilled and frozen packs, and processors moving from commodity cuts into cured and cooked ranges. Vacuum packaging grows at 8.2% a year in the base case, the fastest packaging type, as modern retail adds chilled cabinets. West India gains share on Mumbai demand and new Maharashtra capacity. The main risks are further state restrictions, buffalo shortages and disease outbreaks that halt slaughter for weeks at a time.
State policy and buffalo supply set the range of outcomes
The range of outcomes depends on whether more states restrict beef sales and on how many buffaloes reach licensed plants. Further bans on food service sales or stricter transport rules would slow growth, as would a disease outbreak that halts slaughter. Faster brand building in Kerala and Mumbai, wider modern retail cold chains and steady export demand would lift it. Raw material supply from buffalo herds decides the spread between the cases.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 5.5% | USD 3.03 billion | More states restrict beef sales in food service and buffalo supply tightens further |
| Base | 7.55% | USD 3.59 billion | State rules stay broadly unchanged and processors keep adding chilled and ready-to-cook lines |
| Upside | 8.8% | USD 3.97 billion | Branded chilled and cooked ranges scale in southern and western cities with stable supply |
Frequently Asked Questions
How big is the India processed beef product market?
Can you buy beef in India?
Is beef export banned in India?
Which region leads the market?
Which product type leads?
What does Al Kabeer Exports make in India?
What holds the market back?
Who are the main companies in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Uncured Processed
- 1.2.2 Cured Processed
- 1.2.3 Marinated & Ready-to-Cook
- 1.3 By Type
- 1.3.1 Beef Meat
- 1.3.2 Mechanically Recovered Meat
- 1.3.3 Burgers & Sausages
- 1.3.4 Offal & By-Products
- 1.4 By Packaging
- 1.4.1 Fresh Meat Packaging
- 1.4.2 Vacuum Packaging
- 1.4.3 Modified Atmosphere Packaging
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1.74 billion → 2035: USD 3.59 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Processed Beef Product Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Processed Beef Product Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Processed Beef Product Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Processed Beef Product Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Processed Beef Product Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Processed Beef Product Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Processed Beef Product Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Processed Beef Product Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1.74 billion → 2035: USD 3.59 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Processed Beef Product Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Uncured Processed
- 12.3.7.2 Cured Processed
- 12.3.7.3 Marinated & Ready-to-Cook
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Beef Meat
- 12.4.7.2 Mechanically Recovered Meat
- 12.4.7.3 Burgers & Sausages
- 12.4.7.4 Offal & By-Products
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Packaging - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Fresh Meat Packaging
- 12.5.7.2 Vacuum Packaging
- 12.5.7.3 Modified Atmosphere Packaging
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 India Processed Beef Product Geographic Market Outlook, 2025-2035
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 India Processed Beef Product Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 India Processed Beef Product Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Allanasons Pvt. Ltd. (Allana Group)
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 HMA Agro Industries Ltd.
- 17.4 Al Kabeer Exports Pvt. Ltd.
- 17.5 Fair Exports (India) Pvt. Ltd. (Lulu Group)
- 17.6 Rustam Foods Pvt. Ltd.
- 17.7 Meat Products of India Ltd.
- 17.8 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

