
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| India Reusable Water Bottles Market Size 2023 | USD 427.89 Million |
| India Reusable Water Bottles Market, CAGR | 6.72% |
| India Reusable Water Bottles Market Size 2032 | USD 773.79 Million |
Market Overview
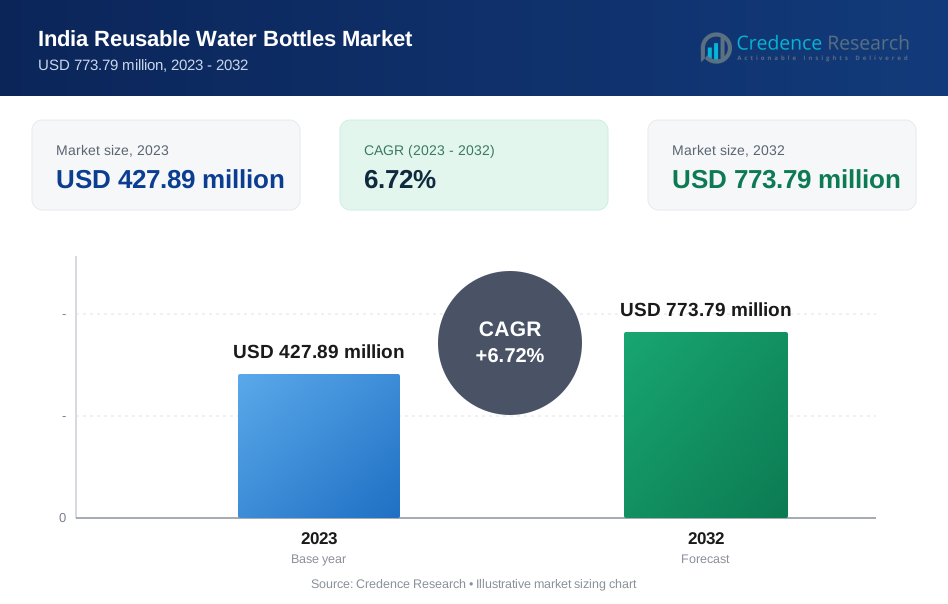
The India Reusable Water Bottles Market is projected to grow from USD 427.89 million in 2023 to an estimated USD 773.79 million by 2032, with a compound annual growth rate (CAGR) of 6.72% from 2024 to 2032. This significant growth underscores a robust expansion within the market, driven by increased consumer awareness towards sustainability and environmentally friendly products. The market's trajectory suggests a promising increase in demand, as consumers increasingly favor reusable over single-use plastic bottles, thereby contributing to a substantial market size and forecasted growth.
Market drivers for the India Reusable Water Bottles Market primarily include growing environmental concerns and the rising awareness of the health implications associated with disposable plastics. Trends towards healthy lifestyle choices further propel the demand for reusable water bottles. Moreover, innovations in bottle design, such as the incorporation of smart technology that tracks hydration levels, are making these products even more appealing to health-conscious consumers. These factors, combined with government initiatives aimed at reducing plastic waste, are set to drive the market forward.
Geographically, the market exhibits strong growth potential across various regions of India, with major urban centers like Mumbai, Delhi, Bangalore, and Chennai showing particularly high demand. These cities are pivotal in driving the adoption rates due to their larger population bases and higher levels of consumer awareness regarding environmental issues. Key players in the India Reusable Water Bottles Market include Tupperware, Cello, Milton, and Nalgene, which are capitalizing on the market growth through innovative product offerings and extensive distribution networks. These companies are instrumental in shaping the market landscape by continuously evolving to meet the dynamic consumer preferences and environmental standards.
Market Drivers
Increasing Environmental Awareness:
As global concern over environmental degradation and plastic pollution intensifies, Indian consumers are becoming more conscious of their ecological footprint. The awareness of the detrimental impacts of single-use plastics on oceans, wildlife, and the broader ecosystem is motivating consumers to switch to more sustainable alternatives like reusable water bottles. This shift is further bolstered by media coverage, environmental campaigns, and educational programs that emphasize the importance of reducing plastic waste. The growing societal push towards sustainability is not just a trend but a profound change in consumer behavior, significantly driving the market for reusable water bottles in India.
Government Initiatives and Regulations:
The Indian government's commitment to combat plastic pollution has led to the implementation of various regulations and initiatives that encourage the use of environmentally friendly products. Bans on single-use plastics in many states across India serve as a legislative driver, pushing both consumers and businesses towards alternatives such as reusable water bottles. These regulatory frameworks not only foster a conducive environment for the growth of the reusable water bottles market but also underscore the government's role in shaping consumer practices towards more sustainable consumption patterns. For instance, the prohibition on single-use plastic water bottles in Australia, Canada, the United States, and some Indian states have created new growth opportunities for reusable bottles.
Health Consciousness Among Consumers:
There is a rising trend of health awareness among Indian consumers, who are increasingly wary of the chemicals and potential toxins associated with disposable plastic bottles, such as BPA and phthalates. The health implications associated with these substances, including hormonal imbalances and increased risk of chronic diseases, have propelled health-conscious individuals to opt for safer alternatives. Reusable water bottles, often made from BPA-free plastics, stainless steel, or glass, are perceived as healthier and safer options. This health-driven demand significantly contributes to the market's growth, as consumers prioritize their health alongside environmental considerations.
Technological Advancements and Product Innovation:
The market for reusable water bottles in India is also driven by continuous product innovations that enhance consumer convenience and appeal. Advances in product features such as built-in filtration systems, insulation technologies that maintain temperature, and integration with digital tools for tracking hydration levels are making reusable water bottles more attractive to consumers. These innovations not only improve the functionality of water bottles but also align with the lifestyle needs of a digitally connected and health-oriented population. Manufacturers are quick to adopt these technological advancements, thereby enriching the product landscape and fueling market growth.
Market Trends
Eco-friendly Materials:
There is a significant shift towards using sustainable materials in the production of reusable water bottles. Materials such as stainless steel, glass, and BPA-free plastics are favored for their durability and non-toxic properties. Additionally, innovations like bamboo and other biodegradable materials are gaining popularity among environmentally conscious consumers who seek products that reduce environmental impact even further.
Smart Bottles:
The integration of technology into everyday items has reached water bottles. Smart reusable water bottles equipped with features like hydration trackers, temperature displays, and even UV purification systems are becoming increasingly popular. These high-tech products appeal particularly to tech-savvy consumers and those involved in fitness and health regimes, offering functionality that goes beyond just providing a drinking container.
Fashion and Personalization:
Reusable water bottles are not just seen as utility items but also as fashion statements. Consumers are attracted to bottles that can be personalized with colors, designs, or features that match their style or personal brand. This trend is particularly strong among younger demographics who value individuality and expressiveness in the products they choose.
Collaborations and Branding:
Many companies are collaborating with popular brands, artists, and influencers to create limited edition bottles. These collaborations help brands tap into new customer segments and generate buzz on social media platforms. They also add a collectible aspect to reusable water bottles, making them more appealing to a broader audience.
Increased Retail Presence:
As demand for reusable water bottles grows, these products are becoming more available in mainstream retail outlets beyond just specialty or outdoor stores. Supermarkets, department stores, and online platforms are expanding their offerings, making it easier for consumers to access a wide range of products.
Corporate and Institutional Initiatives:
Businesses and educational institutions are increasingly adopting reusable water bottles as part of their sustainability initiatives. Providing branded reusable bottles to employees and students not only reduces plastic waste but also enhances the organization's image as an environmentally responsible entity.
Health and Safety Concerns:
In the post-pandemic era, health and safety have become paramount for consumers. Reusable water bottles that offer antimicrobial properties, easy cleaning, and secure sealing features are seeing heightened demand. These aspects assure consumers of safety against contaminants, aligning with the heightened awareness regarding health hygiene.
Market Restraints and Challenges
Prevalence of Low-Cost Alternatives:
The widespread availability and low cost of single-use plastic bottles continue to be a significant challenge for the reusable water bottles market. Many consumers find single-use bottles more convenient for on-the-go consumption due to their lightweight nature and disposability. The price-sensitive nature of a large segment of the Indian market also makes these cheaper, disposable alternatives more appealing despite their environmental impact.
Lack of Awareness and Resistance to Change:
Although awareness about environmental issues is increasing, it is not uniform across all demographics and regions of India. In many rural and semi-urban areas, the concept of reusable water bottles is still not widely understood or valued. Furthermore, changing habitual behavior, such as switching from the convenience of disposable bottles to reusable ones, poses a significant challenge. Overcoming this inertia requires concerted educational efforts and awareness campaigns.
Quality Concerns and Counterfeits:
The market is also challenged by the presence of low-quality and counterfeit products, which can deter consumers from opting for reusable options. These substandard products not only fail to provide the durability and safety promised by reputable brands but can also pose health risks due to the use of non-certified materials. Such incidents can erode consumer trust and confidence in the product category as a whole.
Limited Infrastructure for Cleaning and Maintenance:
For reusable water bottles to be a practical option, consumers need access to facilities for proper cleaning and maintenance. Lack of such infrastructure, especially in public places and at workplaces, can limit the practicality and appeal of carrying a reusable bottle. This challenge is particularly acute in India, where public water sources and facilities often do not meet hygiene standards.
Regulatory and Environmental Compliance:
Complying with evolving regulatory standards for safety and environmental impact can also pose challenges for manufacturers. The Indian market is subject to increasingly stringent regulations concerning materials and manufacturing processes, which can increase production costs and complexity. Ensuring compliance while maintaining competitive pricing and product quality is a delicate balance that manufacturers must manage.
Distribution and Reach in Rural Areas:
Expanding the distribution network to cover vast and diverse geographic areas like India presents logistical challenges. Reaching rural markets, where the potential for growth is significant, requires robust distribution strategies and local market understanding, which can be resource-intensive.
Market Segmentation Analysis
By Material Type
Glass bottles, favored for their chemical-free purity and aesthetic appeal, maintain the flavor of liquids without alteration but are less popular among active consumers and in rural areas due to their fragility and higher cost. Stainless steel bottles are highly valued for their durability, rust resistance, and excellent thermal insulation, making them a preferred choice among travelers, office workers, and fitness enthusiasts. They are considered a mid-to-premium option with eco-friendly credentials and a long lifespan. Plastic bottles continue to be popular despite environmental concerns, thanks to their lightweight, durability, and affordability, with innovations in BPA-free and food-grade plastics maintaining their appeal, especially among school children and in semi-urban areas. Silicon bottles, known for their collapsibility and flexibility, serve as a convenient option for travelers, though they capture a smaller market segment. Additionally, materials like bamboo and other biodegradable options are emerging, gaining traction among environmentally conscious consumers seeking innovative and sustainable solutions.
By Distribution Channel
Specialty stores, including outdoor and sports shops, play a pivotal role in the India Reusable Water Bottles Market by catering to health and environmentally conscious consumers with a variety of high-quality products suited for activities like hiking or yoga. Convenience stores, strategically located in urban and semi-urban areas, facilitate quick, impulsive purchases, making reusable bottles easily accessible to a broad audience. Meanwhile, supermarkets and hypermarkets are vital for mass distribution, offering a diverse range of brands and materials, benefiting from high foot traffic and visibility. Additionally, the market sees considerable contributions from online retailers and direct sales from manufacturers, with the online segment experiencing significant growth due to the convenience of home delivery, the availability of customer reviews, and competitive pricing, all of which enhance consumer engagement and broaden market reach.
Segments
Based on Material Type
- Glass
- Stainless Steel
- Plastic
- Silicon
- Others
Based on Distribution Channel
- Specialty Stores
- Convenience Stores
- Supermarkets and Hypermarkets
- Others
Regional Analysis
North India (30%):
North India, encompassing populous states like Delhi, Punjab, and Uttar Pradesh, holds approximately 30% of the market share. This region benefits from high consumer awareness and a substantial middle-class population that prioritizes sustainability and health. The presence of numerous educational institutions and corporate offices also drives demand for reusable water bottles as part of personal and institutional sustainability efforts.
South India (25%):
With a market share of about 25%, South India, including states like Karnataka, Tamil Nadu, and Kerala, showcases a strong preference for high-quality, durable products due to its well-informed consumer base. The region's emphasis on health and fitness contributes to the popularity of stainless steel and glass water bottles, often seen as more eco-friendly and health-conscious choices.
West India (20%):
Holding around 20% of the market, West India, particularly Maharashtra and Gujarat, is characterized by a vibrant urban lifestyle and a substantial young demographic. The fast-paced urban environments in cities like Mumbai and Pune are conducive to the adoption of innovative products like smart water bottles, which cater to a tech-savvy populace.
East India (15%):
East India, which includes West Bengal, Odisha, and Bihar, accounts for about 15% of the market. The region's market is growing steadily, driven by increasing urbanization and rising disposable incomes. Consumers here are gradually shifting from traditional consumer habits towards more sustainable practices, including the use of reusable water bottles.
Key players
- O. Smith Corporation
- Newell Brands, Inc.
- Vista Outdoor, Inc. (CamelBak Products LLC)
- Groupe SEB
- Tupperware Brands Company
- SIGG Switzerland Bottles AG (Zhejiang Haers Vacuum Containers Co., Ltd.)
- Klean Kanteen
- Hydaway LLC
- Bulletin Bottle
Competitive Analysis
The competitive landscape of the India Reusable Water Bottles Market is marked by the presence of both global giants and specialized local firms. Key players like A. O. Smith Corporation and Newell Brands, Inc. leverage their broad product portfolios and strong brand recognition to dominate the market. Innovations and quality improvements, particularly in terms of material safety and product durability, are common strategies these companies use to attract health-conscious consumers. Smaller players such as Hydaway LLC and Bulletin Bottle differentiate themselves with unique designs and niche offerings, such as collapsible or highly customizable bottles, targeting specific consumer preferences. Collaboration with environmental initiatives and aligning with global sustainability goals are also critical strategies employed to enhance brand value and consumer loyalty in this competitive sector.
Recent Developments
In April 2023, Nalgene announced a significant shift in its manufacturing process to Eastman’s Tritan Renew, utilizing a mass balance technique to ensure the new material comprises 50% recycled content. This transition to Tritan Renew began in 2020 and concluded by January 2023, during which Nalgene successfully repurposed over 2.35 million pounds of plastic waste. This initiative marks a substantial step in Nalgene's commitment to sustainability, reducing the environmental footprint of its production while maintaining the quality and durability expected from their reusable bottles.
In February 2023, SIGG Switzerland AG participated in the ABN AMRO Open tennis tournament, held at Rotterdam Ahoy, by providing all players with reusable bottles made from Tritan Renew. This material is noted for its high impact and scratch resistance, certified by the International Sustainability and Carbon Certification (ISCC). SIGG’s involvement in this event highlights their commitment to promoting sustainability in sports, providing eco-friendly solutions that minimize the environmental impact of large public events.
In December 2022, Klean Kanteen collaborated with fellow outdoor drinkware brands MiiR, Stanley, and YETI to establish the Drinkware CoLab. This initiative aims to reduce carbon emissions within their supply chains and aligns with the Outdoor Industry Association’s (OIA) objective to become the first climate-positive industry by 2030. As members of the OIA’s Climate Action Corps, these brands are working together to achieve a net-positive environmental impact, striving to exceed the standard of net zero emissions.
In August 2022, S’well introduced its Elements Collection, which features three high-gloss bottles: ‘Blue Marble,’ ‘Charcoal Granite,’ and ‘Opal Marble.’ These bottles are crafted from double-walled, stainless steel and are insulated to keep drinks cold for 24 hours or hot for 12 hours. The design of the bottles prevents condensation, allows for drip-free sipping, and includes a wide mouth to facilitate the addition of ice cubes, combining practicality with a stylish aesthetic that draws inspiration from natural elements.
In June 2022, Tupperware Brands Corporation teamed up with Vera Bradley, a renowned U.S.-based fashion company, to launch a limited edition collection of ECO+ water bottles, along with matching snack sets and sandwich keepers. This exclusive line features three vibrant patterns: Daisy Smile, Falling Daisies, and Sunflower collections. This collaboration blends Tupperware's commitment to sustainability with Vera Bradley’s distinctive floral designs, offering consumers aesthetically pleasing and environmentally friendly reusable products.
Market Concentration and Characteristics
The India Reusable Water Bottles Market exhibits a moderate level of market concentration, with a mix of leading global brands and emerging local companies shaping the competitive landscape. Prominent players like Tupperware, SIGG, and Klean Kanteen dominate through widespread distribution networks, brand recognition, and product innovation. However, the market is also characterized by the presence of numerous smaller players that cater to niche segments with specialized products, such as bottles made from biodegradable materials or incorporating advanced technology like hydration tracking. This diversity fosters a dynamic market environment where consumer choices are influenced by a blend of product quality, environmental concerns, and brand loyalty. Overall, the market is competitive but still offers ample opportunities for new entrants and innovation, especially in segments such as smart bottles and eco-friendly materials.
Report Coverage
The research report offers an in-depth analysis based on Material Type and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Consumer awareness regarding environmental sustainability is expected to continue growing, leading to increased adoption of reusable water bottles across various demographics in India.
- Advancements in technology will likely enhance the functionality of reusable water bottles, incorporating features like smart hydration reminders, which will attract a tech-savvy consumer base.
- Stricter government regulations on single-use plastics are anticipated, which will push more consumers towards reusable alternatives, bolstering market growth.
- As awareness and infrastructure improve, there will be significant market expansion opportunities in India’s rural areas, previously untapped by this industry.
- Collaborations between reusable water bottle companies and fashion brands, sports franchises, or environmental campaigns will enhance brand visibility and market penetration.
- The shift towards more sustainable materials like biodegradable composites and recycled plastics will continue to evolve, meeting consumer demand for environmentally friendly products.
- Increasing consumer desire for personalization will drive innovations in customization options for reusable water bottles, making them popular lifestyle accessories.
- The health-conscious trend will persist, with more consumers choosing reusable water bottles to avoid the potential health risks associated with disposable plastics.
- Online sales channels will play a crucial role in the market's growth, facilitated by the convenience of e-commerce platforms and the expansion of digital infrastructure.
- Local manufacturing of reusable water bottles is expected to increase, driven by the Make in India initiative and the need to reduce import dependency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size and growth rate of the India Reusable Water Bottles Market by 2032?
What are the main factors driving the growth of the India Reusable Water Bottles Market?
Which regions in India show the highest demand for reusable water bottles?
Who are the key players in the India Reusable Water Bottles Market?
What are the emerging trends in the India Reusable Water Bottles Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 427.89 million → 2032: USD 773.79 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Reusable Water Bottles Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Reusable Water Bottles Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Reusable Water Bottles Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Reusable Water Bottles Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Reusable Water Bottles Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Reusable Water Bottles Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Reusable Water Bottles Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Reusable Water Bottles Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 427.89 million → 2032: USD 773.79 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Reusable Water Bottles Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 India Reusable Water Bottles Geographic Market Outlook, 2023-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 India Reusable Water Bottles Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 India Reusable Water Bottles Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
