
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Industrial Counterweight Market Size 2024 | USD 7,850 million |
| Industrial Counterweight Market, CAGR | 6% |
| Industrial Counterweight Market Size 2032 | USD 12,512 million |
Market Overview:
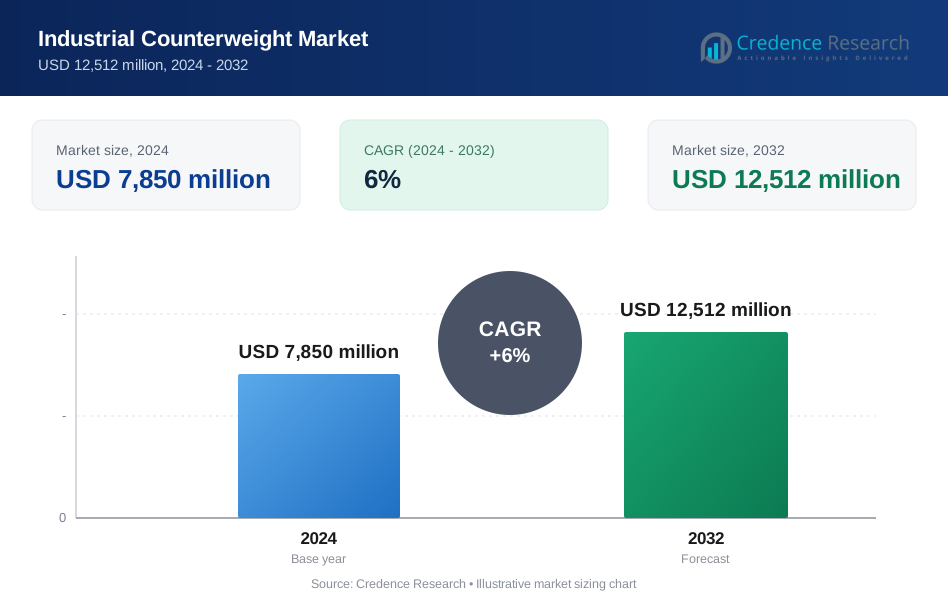
The Industrial Counterweight Market is projected to grow from USD 7,850 million in 2024 to USD 12,512 million by 2032, with a compound annual growth rate (CAGR) of 6%.
The industrial counterweight market is driven by increasing demand from the construction, material handling, and heavy machinery sectors, which require precise weight balancing to ensure operational stability and safety. As infrastructure development and urbanization expand globally, the need for cranes, forklifts, and other lifting equipment has risen, boosting counterweight demand. Advancements in manufacturing technologies, such as the use of eco-friendly materials and innovative designs, are also enhancing the efficiency and durability of counterweights. Additionally, the growing emphasis on sustainability has led to a shift toward reusable and recyclable materials, further driving market growth. The adoption of automated machinery in various industries, coupled with increasing investments in industrial automation, is fostering demand for counterweights to ensure equipment balance and reliability. These trends, combined with rising government investments in infrastructure projects, are expected to fuel steady growth in the industrial counterweight market over the coming years.
The industrial counterweight market is geographically diverse, with significant contributions from North America, Europe, Asia Pacific, the Middle East and Africa (MEA), and Latin America. North America leads with a strong industrial base and infrastructure projects, while Europe focuses on sustainability and eco-friendly materials. Asia Pacific, driven by rapid urbanization and industrialization, is the largest and fastest-growing region, with China, India, and Japan leading demand. The MEA region is witnessing steady growth due to ongoing infrastructure developments, particularly in the UAE and Saudi Arabia. Latin America is growing gradually, with key markets in Brazil and Mexico. Leading players in the market include JSW Steel, Thyssenkrupp, Tata Steel, Hebei Iron Steel, Anshan Iron Steel, Maanshan Iron Steel, Wuhan Iron Steel, Hyundai Steel, POSCO, Steel Dynamics, Baosteel, and Nippon Steel Sumitomo Metal, driving competition and innovation across these regions.
Market Insights:
- The industrial counterweight market is expected to grow from USD 7,850 million in 2024 to USD 12,512 million by 2032, with a CAGR of 6%.
- Increasing demand from construction, material handling, and heavy machinery sectors is driving the market as these industries require counterweights for stability and safety.
- Global infrastructure development and urbanization are pushing the demand for cranes, forklifts, and other lifting equipment, directly fueling counterweight requirements.
- Advances in manufacturing technologies, such as the use of eco-friendly materials and innovative designs, are enhancing counterweight efficiency and durability.
- The shift towards reusable and recyclable materials is in response to growing environmental sustainability concerns, further boosting market growth.
- Rising automation in industries like manufacturing and logistics is increasing the need for precise counterweights to ensure equipment balance.
- Key regions driving the industrial counterweight market include North America, Europe, Asia Pacific, the Middle East and Africa, and Latin America, with Asia Pacific experiencing the highest growth.
Market Drivers:
Growing Infrastructure Development:
The industrial counterweight market is primarily driven by the rapid growth of infrastructure projects across the globe. As countries invest heavily in building new roads, bridges, airports, and commercial spaces, the demand for construction equipment like cranes and excavators is rising. These machines require counterweights to ensure stability and operational safety, making them essential components in construction projects. The increasing need for large-scale infrastructure development in both developed and emerging economies is expected to boost the demand for counterweights.
Rising Demand for Material Handling Equipment:
The global expansion of industries such as manufacturing, logistics, and warehousing is creating a surge in demand for material handling equipment, including forklifts, loaders, and conveyors. These machines depend on counterweights to maintain balance and ensure safe operations during the transportation and lifting of heavy loads. For instance, The largest loader in the world, LeTourneau L-2350, uses a diesel-electric propulsion system where each rubber-tired wheel is driven by its own independent electric motor. As companies seek to improve operational efficiency, the adoption of advanced material handling solutions is growing, directly contributing to the increased use of industrial counterweights.
Advancements in Counterweight Design and Materials:
Technological advancements in the design and production of counterweights are another key driver of the market. Manufacturers are increasingly using innovative materials, such as concrete, steel, and eco-friendly composites, to produce lighter, more durable, and recyclable counterweights. This shift is in response to the growing demand for environmentally sustainable solutions, as well as the need for improved performance and cost-efficiency in industrial machinery. These advancements are expected to drive further growth in the industrial counterweight market.
Increasing Automation in Industrial Sectors:
Automation is transforming various industries, including manufacturing, construction, and logistics. The rise of automated machinery and robotics has created a growing need for precision and balance in equipment, thereby increasing the demand for counterweights. For instance, Tadano introduced its AC 5.250-2 all-terrain crane with enhanced safety features in December 2023. The crane offers a strong lifting capacity while remaining easy to transport. As industries continue to adopt automated solutions to enhance productivity, the industrial counterweight market is expected to experience steady growth in response to these technological changes.
Market Trends:
Shift Toward Sustainable Materials:
A significant trend in the industrial counterweight market is the increasing use of sustainable materials in production. For instance, IKEA has integrated green chemistry by using renewable raw materials in its particleboard production, replacing traditional formaldehyde-based resins with bio-based adhesives derived from plant materials to reduce VOC emissions. Manufacturers are shifting from traditional materials like steel and lead to more eco-friendly alternatives such as concrete and recycled materials. This change is driven by rising environmental concerns and regulatory pressures, encouraging companies to adopt greener practices. The use of sustainable materials not only reduces the carbon footprint of production but also aligns with the growing demand for environmentally responsible solutions across industries.
Integration of Advanced Manufacturing Technologies:
The adoption of advanced manufacturing technologies, such as 3D printing and CNC machining, is transforming the counterweight production process. These technologies enable manufacturers to create more precise, lightweight, and durable counterweights while reducing material waste and production time. The integration of these innovations allows companies to meet the specific requirements of various applications, improving overall efficiency and product performance. This trend is expected to accelerate as industries increasingly demand customized solutions for their machinery.
Increased Demand for Automation:
Automation is playing an increasingly important role in driving demand for industrial counterweights. As industries such as manufacturing, logistics, and construction continue to automate their operations, the need for counterweights that can maintain the balance and stability of automated machinery is growing. For instance, In June 2024, Renault Group launched a 100% automated logistics facility in Villeroy, France, using Exotec's Skypod robots which rely on counterweights. The adoption of robots, automated guided vehicles (AGVs), and other advanced equipment necessitates high-precision counterweights to ensure smooth and safe operations, further fueling market demand.
Focus on Lightweight Counterweights:
Another notable trend is the growing emphasis on lightweight counterweights that enhance machine efficiency without compromising stability. Manufacturers are developing innovative designs that reduce weight while maintaining the necessary balance for heavy equipment. Lightweight counterweights improve fuel efficiency, reduce operational costs, and allow for greater flexibility in machine movement, making them increasingly popular in industries where efficiency is critical.
Market Challenges Analysis:
Fluctuating Raw Material Prices:
One of the key challenges faced by the industrial counterweight market is the volatility of raw material prices. Counterweights are primarily made from materials like steel, iron, and concrete, which are subject to significant price fluctuations due to changes in global demand, supply chain disruptions, and geopolitical factors. Trade policies, natural disasters, and market uncertainties can lead to increased material costs, affecting the profitability of manufacturers. For smaller players in the market, these fluctuations can present additional financial burdens, as they may struggle to absorb rising material costs without passing them on to customers. For instance, Crescent Foundry, an Indian manufacturer of counterweights, uses real-time monitoring and analysis during each production stage, from raw material handling to final product quality checks, to streamline its production process. This volatility creates uncertainty in pricing, cost management, and long-term business planning, making it difficult for manufacturers to maintain stable profit margins and forecast future market trends. The unpredictability of material prices can also hinder the overall growth and expansion of the market, as businesses may be hesitant to invest in new projects or expand production capacities under uncertain economic conditions.
Environmental and Regulatory Constraints:
Stringent environmental regulations also pose a challenge to the industrial counterweight market, especially in regions with strong environmental protection laws. The production of counterweights, particularly those made from metals, often involves energy-intensive processes and the generation of industrial waste. Increasing regulatory scrutiny around emissions, waste management, and the use of hazardous materials like lead has forced manufacturers to adopt more sustainable practices, which can be costly and time-consuming. Compliance with these regulations requires investments in cleaner technologies and the development of eco-friendly alternatives, which may drive up production costs. Additionally, the disposal and recycling of outdated or damaged counterweights can pose logistical challenges, further complicating manufacturers' operations. As environmental concerns continue to grow, companies in the industrial counterweight market will need to navigate evolving regulations and ensure sustainable production methods, while also maintaining cost competitiveness in an increasingly regulated environment.
Market Opportunities:
The industrial counterweight market presents significant opportunities driven by the growing demand for construction and material handling equipment. As urbanization accelerates and infrastructure projects expand globally, the need for cranes, forklifts, and other lifting equipment continues to rise. These machines require counterweights for stability and safety, providing a steady market for manufacturers. Furthermore, the increasing adoption of automation in various industries such as manufacturing, logistics, and warehousing is creating additional demand for counterweights to ensure the balance and operational efficiency of automated machinery. As industries continue to modernize, opportunities for growth in the industrial counterweight market are expanding, particularly in emerging economies where infrastructure development is a priority.
Another promising opportunity is the ongoing shift towards sustainable and lightweight counterweight solutions. With a growing emphasis on environmental responsibility, there is a demand for counterweights made from eco-friendly materials like recycled metals and concrete. Manufacturers that focus on developing and offering green alternatives will be well-positioned to capitalize on this trend. Additionally, advancements in manufacturing technologies, such as 3D printing and precision casting, are opening new avenues for producing customized, cost-effective counterweights. These innovations allow for greater design flexibility and higher performance, further fueling market growth. The combination of technological advancements and a focus on sustainability presents a unique opportunity for companies in the industrial counterweight market to differentiate themselves and meet the evolving needs of the industry.
Market Segmentation Analysis:
By Product Type
The industrial counterweight market is segmented by product type into concrete, steel, and other materials. Concrete counterweights dominate due to their cost-effectiveness and versatility in construction and heavy machinery applications. Steel counterweights are preferred for their durability and strength in demanding environments. Other material segments include composite and eco-friendly alternatives, gaining traction as sustainability becomes more critical.
By Application
The industrial counterweight market is driven by applications in construction, material handling, and mining. In construction, counterweights are vital for cranes and lifting equipment to ensure stability and safety. Material handling equipment, such as forklifts, also relies on counterweights for efficient load handling. The mining sector requires robust counterweights for heavy-duty machinery, driving demand in this application segment.
By Capacity
Counterweights in the industrial market are available in various capacities, ranging from small to heavy-duty options. Smaller counterweights are used in light construction and material handling equipment, while larger, heavy-duty counterweights are essential for large-scale construction projects and mining operations. The demand for higher capacity counterweights is increasing as industries rely on heavier, more powerful machinery.
Segments:
Based on Product Type
- Concrete Counterweights
- Steel Counterweights
- Cast Iron Counterweights
- Polymer Counterweights
Based on Application
- Material Handling Equipment
- Construction Equipment
- Mining Equipment
- Automotive Industry
- Renewable Energy Sector
Based on Capacity
- Below 1,000 lbs
- 1,000 - 5,000 lbs
- 5,001 - 10,000 lbs
- Above 10,000 lbs
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a substantial share of the industrial counterweight market, accounting for 30% in 2024. The region's dominance can be attributed to its advanced infrastructure and high demand for construction and material handling equipment. The United States and Canada lead in large-scale infrastructure projects, which drive the need for cranes and heavy machinery, both of which require counterweights for operational safety and stability. Additionally, the increasing adoption of automation in manufacturing and logistics further supports market growth. The region also places a high emphasis on sustainability, encouraging the development of eco-friendly counterweight materials. North America is expected to maintain steady growth as investments in smart manufacturing, urban development, and infrastructure continue to rise, ensuring sustained demand for counterweights.
Europe
Europe captures 25% of the global industrial counterweight market share in 2024. The region’s well-established industrial base and significant presence in sectors like construction, mining, and material handling contribute to its market strength. Key countries such as Germany, the UK, and France are central to market demand, with ongoing infrastructure development and modernization efforts. Furthermore, Europe’s stringent environmental regulations encourage the use of sustainable materials, spurring innovation in the counterweight sector. The rise of automation, particularly in construction and manufacturing, also plays a key role in market expansion. As industries continue to evolve, the European market is expected to grow steadily, driven by demand for eco-friendly and efficient counterweights that align with regulatory requirements.
Asia Pacific
Asia Pacific is the fastest-growing region in the industrial counterweight market, holding a dominant share of 35% in 2024. The rapid urbanization and industrial growth across countries such as China, India, and Japan are key drivers of market demand. Infrastructure development, particularly in construction and transportation, requires a significant increase in the use of cranes, forklifts, and heavy machinery, which rely on counterweights for safety and stability. The rise of automation across manufacturing, logistics, and material handling sectors further boosts demand. As the region continues to invest heavily in infrastructure and smart technologies, the Asia Pacific market is expected to maintain robust growth, reinforcing its position as the global market leader for industrial counterweights.
Middle East and Africa
The Middle East and Africa (MEA) region holds 5% of the global industrial counterweight market in 2024, with steady growth driven by ongoing infrastructure development projects in key markets like the UAE, Saudi Arabia, and South Africa. The demand for heavy-duty machinery and lifting equipment in sectors such as construction, mining, and logistics is a significant factor in the region's counterweight market growth. Additionally, the region's increasing focus on creating smart cities and modernizing urban infrastructure fuels the need for more efficient and stable machinery, thereby increasing the demand for industrial counterweights. While the MEA market remains smaller compared to other regions, its growth potential is substantial, especially as governments continue to prioritize large-scale infrastructure investments.
Latin America
Latin America represents around 5% of the global industrial counterweight market share in 2024. The region's market growth is driven by key sectors such as construction and mining, with significant investments in infrastructure projects in countries like Brazil, Argentina, and Mexico. Despite facing economic volatility and regulatory challenges, Latin America presents considerable opportunities for growth due to the rising demand for automated and efficient machinery. Industries are increasingly adopting advanced lifting equipment, including cranes and forklifts, which require reliable counterweights for operational safety. As the region navigates economic fluctuations, steady growth in infrastructure and industrial sectors is expected to continue supporting the demand for industrial counterweights.
Key Player Analysis:
- Nippon Steel Sumitomo Metal
- Thyssenkrupp
- Baosteel
- Hyundai Steel
- Hebei Iron Steel
- Wuhan Iron Steel
- Steel Dynamics
- Tata Steel
- POSCO
- Maanshan Iron Steel
- Anshan Iron Steel
- JSW Steel
Competitive Analysis:
The industrial counterweight market is highly competitive, with leading players like JSW Steel, Thyssenkrupp, Tata Steel, Hebei Iron Steel, Anshan Iron Steel, Maanshan Iron Steel, Wuhan Iron Steel, Hyundai Steel, POSCO, Steel Dynamics, Baosteel, and Nippon Steel Sumitomo Metal. These companies focus on innovations in materials and manufacturing processes to gain a competitive edge. Additionally, advancements in lightweight counterweights, including the use of composites and recycled materials, are becoming a key differentiator. To stay ahead in the market, leading players are also adopting advanced manufacturing technologies like 3D printing and precision casting, enabling them to offer customized solutions. These strategies are crucial for maintaining market share as industries increasingly demand more efficient, durable, and environmentally friendly counterweight solutions.
Recent Developments:
- In June 2023, at TOC Europe in Rotterdam, Kalmar, a part of Cargotec, launched its eco-efficient electric reach stacker, offering new sustainable features. This makes the Kalmar electric reach stacker the world's most sustainable with the latest available options. Furthermore, Kalmar has introduced a new counterweight that minimizes emissions by replacing cast iron with unprocessed natural heavy materials.
- In December 2024, Allient Inc., a global designer and manufacturer of precision and specialty motion, controls, and power products, announced the launch of its Allient Defense Solutions business unit. This initiative underscores Allient’s commitment to expanding its presence in high-growth markets and driving long-term value for customers and stakeholders.
Market Concentration & Characteristics:
The industrial counterweight market exhibits a moderate level of concentration, with a few large players dominating the landscape while numerous smaller manufacturers contribute to overall market growth. Key players such as JSW Steel, Thyssenkrupp, Tata Steel, and POSCO hold significant market shares, benefiting from their extensive production capabilities, global reach, and strong supply chains. However, the market also includes regional players that specialize in specific applications or provide niche solutions, creating a competitive environment. Market characteristics are defined by the increasing demand for stability and safety in heavy machinery, which drives the need for industrial counterweights. The industry is witnessing a trend toward product innovation, with a focus on lightweight, durable, and sustainable counterweights. Manufacturers are also exploring advanced technologies, such as 3D printing and automation, to improve production efficiency and customization. This dynamic market offers opportunities for growth as industries adopt new technologies and prioritize eco-friendly solutions.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, Capacity and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The industrial counterweight market is expected to grow steadily due to the increasing demand for construction and material handling equipment.
- The shift toward sustainable and eco-friendly materials will drive innovation in counterweight design and production.
- Technological advancements, such as 3D printing and automation, will enable more customized and efficient counterweights.
- Rising infrastructure projects in emerging economies will contribute to increased demand for counterweights.
- The growth of automation across industries like manufacturing and logistics will create further demand for counterweights in automated machinery.
- The market will see an increase in the adoption of lightweight counterweights to improve fuel efficiency and reduce operational costs.
- Manufacturers will focus on developing high-performance counterweights that balance cost-effectiveness with durability.
- Stringent environmental regulations will push companies to invest in greener production methods and materials.
- Global supply chain disruptions may continue to impact raw material availability, affecting counterweight production costs.
- Regional markets in Asia Pacific and Latin America are likely to experience the highest growth due to ongoing industrialization and infrastructure development.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Industrial Counterweight Market?
What factors are driving the growth of the Industrial Counterweight Market?
What are some challenges faced by the Industrial Counterweight Market?
Who are the major players in the Industrial Counterweight Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 7,850 million → 2032: USD 12,512 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Industrial Counterweight Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Industrial Counterweight Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Industrial Counterweight Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Industrial Counterweight Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Industrial Counterweight Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Industrial Counterweight Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Industrial Counterweight Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Industrial Counterweight Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 7,850 million → 2032: USD 12,512 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Industrial Counterweight Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Industrial Counterweight Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Industrial Counterweight Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Industrial Counterweight Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
