
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
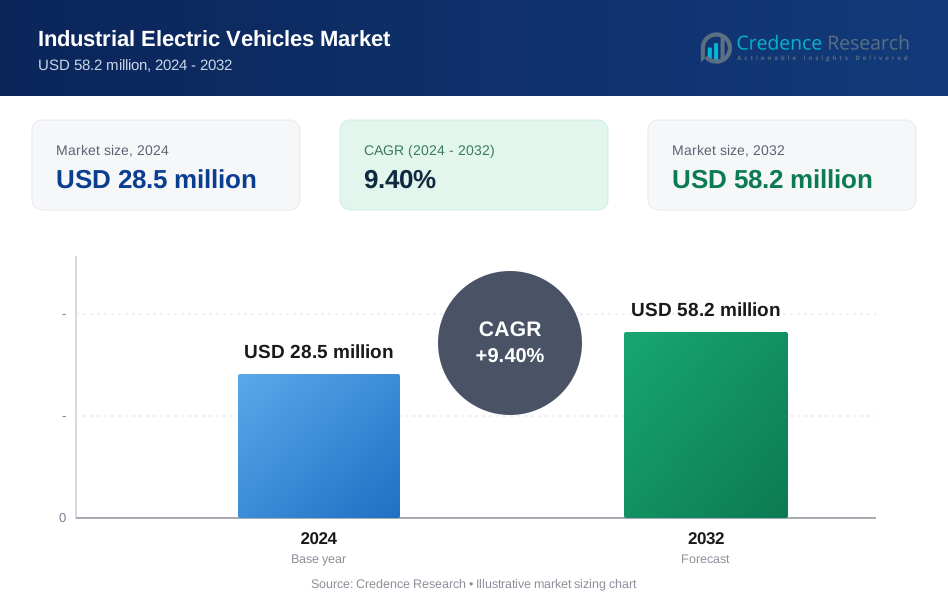
| Industrial Electric Vehicles Market Size 2024 | USD 28.5 Million |
| Industrial Electric Vehicles Market, CAGR | 9.40% |
| Industrial Electric Vehicles Market Size 2032 | USD 58.2 Million |
Market Overview:
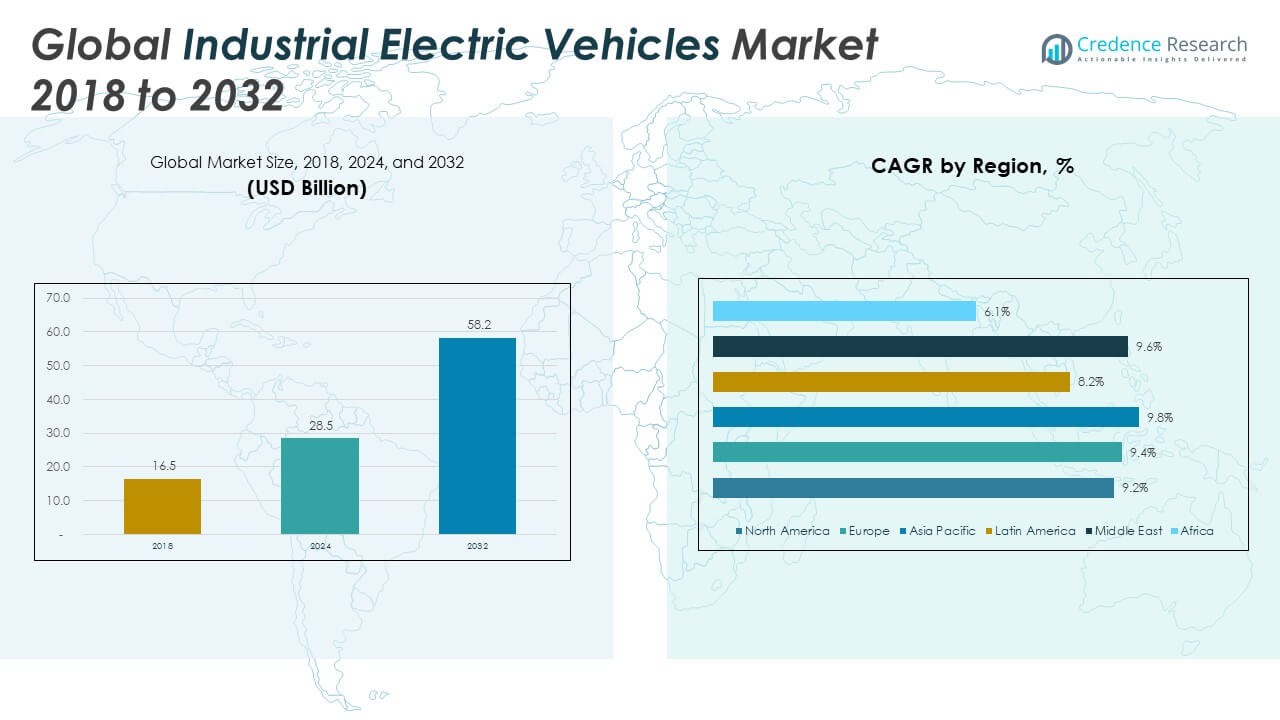
The Industrial Electric Vehicles Market size was valued at USD 16.5 million in 2018 to USD 28.5 million in 2024 and is anticipated to reach USD 58.2 million by 2032, at a CAGR of 9.40% during the forecast period.
The growth of the Industrial Electric Vehicles (IEV) market is primarily driven by the increasing demand for energy-efficient and low-maintenance machinery in industrial settings. Electric vehicles offer significant cost advantages through reduced fuel expenses, lower maintenance requirements, and enhanced operational uptime, making them an attractive choice for logistics, manufacturing, and warehouse operations. Moreover, stringent environmental regulations aimed at reducing carbon emissions and improving workplace safety are accelerating the shift from traditional internal combustion engine vehicles to electric alternatives. Governments and regulatory bodies across key markets are encouraging electrification through tax incentives, carbon credits, and emissions mandates, further stimulating adoption. Technological advancements also play a crucial role, as innovations in battery performance, automation, and telematics are enhancing the efficiency and versatility of electric industrial vehicles. Additionally, the growing emphasis on sustainable and resilient supply chains is prompting companies to invest in electric fleets that align with their ESG objectives and mitigate the risks associated with fuel price volatility.
Regionally, the Asia-Pacific region dominates the industrial electric vehicles market, supported by rapid industrial expansion, government-led electrification initiatives, and the presence of major manufacturing hubs. Countries such as China, Japan, India, and South Korea are witnessing robust demand due to their focus on clean energy transitions and large-scale warehouse automation. Europe follows closely, driven by stringent emission regulations, a well-established electric vehicle infrastructure, and strong governmental support for sustainable industrial practices. Germany, France, and the Netherlands are key adopters within the region, benefiting from early investments in electric material-handling equipment. North America is emerging as one of the fastest-growing regions in the IEV market, with the United States and Canada investing heavily in logistics automation and zero-emission industrial fleets to meet climate goals and improve operational efficiency.
Market Insights:
- The Industrial Electric Vehicles Market was valued at USD 28.5 million in 2024 and is projected to reach USD 58.2 million by 2032, growing at a CAGR of 9.40%.
- Rising demand for energy-efficient and low-maintenance transport solutions is encouraging industries to adopt electric vehicles across logistics, warehousing, and manufacturing sectors.
- Strict emissions regulations and safety mandates are accelerating the shift from internal combustion engines to electric alternatives, especially in enclosed or urban environments.
- Advancements in lithium-ion batteries, real-time tracking, and vehicle automation are enhancing electric vehicle performance and usability for industrial operations.
- The rapid growth of e-commerce and supply chain automation is driving the need for scalable, quiet, and emission-free vehicle fleets in distribution hubs.
- High upfront costs, infrastructure limitations, and retrofitting challenges remain key barriers, particularly for small and mid-sized enterprises and older facilities.
- Asia-Pacific leads the market in terms of volume and growth, followed by Europe and North America, with regional adoption shaped by industrial expansion, policy support, and investment in electrification.
Market Drivers:
Rising Demand for Energy-Efficient and Cost-Effective Industrial Transportation Solutions
The increasing focus on operational efficiency and cost reduction is driving demand for electric alternatives across warehouses, factories, and ports. Industrial Electric Vehicles Market is gaining momentum as companies shift toward energy-efficient vehicles to replace traditional internal combustion equipment. Electric vehicles offer significant savings in fuel and maintenance costs, enabling long-term value. Businesses are actively pursuing technologies that support uninterrupted operations and reduce downtime. The total cost of ownership becomes more favorable with electric fleets, especially in high-usage environments. Energy efficiency also aligns with corporate sustainability goals, further supporting procurement decisions.
- For example, battery advancements, such as Tesla’s 2170 and 4680 cells, have increased energy density and thermal management, supporting longer operational shifts and faster charging key for high-usage environments.
Growing Regulatory Pressure to Reduce Emissions and Improve Workplace Safety Tightening global emissions standards and safety regulations are compelling industries to transition toward cleaner mobility solutions. Governments in key regions have introduced strict mandates for reducing greenhouse gas emissions across industrial sectors. Industrial Electric Vehicles Market is benefitting from policies that ban or limit fossil fuel-powered equipment in enclosed or densely populated spaces. Electric vehicles operate quietly and produce no direct emissions, making them suitable for indoor use and urban logistics. Regulatory compliance is no longer optional in many regions, placing pressure on businesses to modernize fleets. It offers a solution that helps companies meet both safety and sustainability benchmarks.
- For instance, the U.S. Department of Energy reports that all-electric vehicles can exceed 130 MPGe and require only 25–40 kWh per 100 miles, significantly improving fuel economy and reducing operational emissions compared to conventional vehicles.
Technological Advancements Enhancing Battery Life, Automation, and Smart Integration
Recent innovations in lithium-ion batteries, vehicle automation, and telematics systems are transforming industrial fleet management. Longer battery cycles and faster charging capabilities make electric vehicles more viable for full-shift operations. Industrial Electric Vehicles Market is evolving with the integration of autonomous navigation, real-time tracking, and predictive maintenance features. These technologies improve vehicle utilization, reduce human error, and support better decision-making through data analytics. Many OEMs are investing heavily in R&D to stay competitive and meet the changing demands of industrial users. It is becoming more capable, efficient, and intelligent with each product cycle.
Increased Adoption Driven by Logistics Growth and Electrification of Supply Chains
The global expansion of e-commerce and just-in-time delivery systems has created new demands on warehouses and distribution centers. Companies require agile, scalable transport solutions that can operate reliably across multiple shifts. Industrial Electric Vehicles Market supports this shift by offering low-noise, emission-free operation that suits high-density and temperature-controlled environments. Large retailers and logistics providers are transitioning to electric fleets to meet delivery targets and reduce carbon footprints. Electric vehicles are now integral to modern supply chain strategies. It supports operational agility while aligning with broader goals in sustainability and brand responsibility.
Market Trends:
Expansion of Automation and Integration of Autonomous Navigation Technologies
Automation continues to reshape industrial operations, and electric vehicles are at the center of this shift. Companies are incorporating autonomous navigation systems, enabling vehicles to move independently within warehouses and manufacturing facilities. These systems reduce reliance on manual labor and enhance precision in repetitive tasks. Industrial Electric Vehicles Market is adapting to this trend with advanced sensor technologies, AI-powered decision systems, and route optimization features. Businesses are investing in fully integrated systems that connect vehicles to broader logistics and inventory platforms. It helps improve fleet coordination, reduce errors, and support 24/7 operations.
- For example, Oritek’s Longquan 560 series ADAS chipsets, powered by Ceva’s SensPro Vision AI DSP, deliver energy-efficient, real-time processing for advanced driver-assistance systems (ADAS), supporting critical applications such as obstacle detection, lane keeping, and autonomous routing in industrial environments.
Increased Investment in Lithium-Ion Batteries and Rapid Charging Infrastructure
Battery technology is evolving quickly, helping industrial users overcome previous concerns around limited range and charging time. Lithium-ion batteries now offer higher energy density, longer service life, and more efficient power delivery. Industrial Electric Vehicles Market is shifting toward these advanced battery systems due to their improved performance and lower environmental impact. Companies are also developing rapid-charging infrastructure to support continuous vehicle use across multiple shifts. Charging time is becoming less of a barrier, especially in high-demand settings like logistics hubs and cold storage facilities. It allows operators to maintain productivity without compromising energy goals.
Adoption of Telematics and Data-Driven Fleet Optimization Systems
Smart fleet management tools are becoming standard features in electric industrial vehicles. Telematics systems provide real-time data on location, usage, battery health, and performance. Industrial Electric Vehicles Market is responding with integrated software solutions that support predictive maintenance, automated reporting, and energy consumption tracking. These tools reduce unexpected downtime and enhance safety through proactive alerts. Fleet operators use data insights to allocate resources more efficiently and optimize operational planning. It supports greater transparency, accountability, and responsiveness across the logistics chain.
Growing Focus on Customization to Meet Application-Specific Demands
End users increasingly seek electric vehicles tailored to their specific operational environments. Manufacturers are developing modular platforms that support custom configurations in terms of size, payload, and maneuverability. Industrial Electric Vehicles Market is evolving to accommodate niche requirements in industries such as pharmaceuticals, cold storage, and food processing. Demand is rising for compact designs suited to narrow aisles, as well as rugged models for outdoor use. Clients value flexibility in vehicle design to align with automation systems and storage layouts. It drives innovation across form factors, control systems, and auxiliary features.
- For instance, IAV’s modular light BEV platform, for example, supports battery capacities from 27 to 115 kWh, power outputs from 100 to 440 kW, and voltage levels of 400 or 800 volts, with over 24 million technically feasible powertrain variants generated via simulation tools.
Market Challenges Analysis:
High Initial Capital Investment and Infrastructure Constraints
The transition to electric vehicles in industrial environments often involves a significant upfront cost. Businesses must invest in both the vehicles and the supporting infrastructure, such as charging stations and facility upgrades. For small and mid-sized enterprises, this capital requirement can delay adoption despite long-term operational savings. Industrial Electric Vehicles Market faces resistance in regions with limited access to reliable power supply or inadequate facility space for fleet charging. It also encounters challenges in retrofitting older industrial buildings that are not designed for modern electrical loads. These factors can slow market penetration and limit deployment in less developed industrial zones.
Battery Limitations, Lifecycle Uncertainty, and Technological Gaps
While battery technology is advancing, concerns remain around durability, performance degradation, and recycling processes. Industrial users require equipment that performs consistently under high usage and demanding environmental conditions. The Industrial Electric Vehicles Market continues to grapple with limitations in battery longevity, particularly in cold storage, high-heat zones, or rough outdoor terrains. It must also address the challenges of battery disposal, regulatory compliance, and total lifecycle management. Gaps in workforce training and maintenance skills further complicate adoption, especially in regions lacking technical expertise. These barriers make full-scale integration more complex for many industrial operators.
Market Opportunities:
Emerging Demand in Developing Economies and Untapped Industrial Sectors
Rapid industrialization in regions such as Southeast Asia, Latin America, and parts of Africa presents a strong growth opportunity. Many businesses in these areas are seeking efficient, low-emission solutions to modernize logistics and warehousing. Industrial Electric Vehicles Market stands to benefit from government-led sustainability initiatives and infrastructure investments. It can meet rising demand across sectors like agriculture, mining, and small-scale manufacturing. Manufacturers offering affordable and adaptable solutions will likely capture early market share. Entry into these regions also allows brands to establish long-term supply and service networks.
Integration with Smart Warehousing and Industry 4.0 Initiatives
Companies adopting smart warehousing strategies increasingly require connected, automated, and sustainable equipment. Industrial electric vehicles with integrated telematics and autonomous capabilities align well with Industry 4.0 priorities. Industrial Electric Vehicles Market is positioned to support digital transformation efforts across logistics and production environments. It can deliver strong value in operations requiring precision, low emissions, and data-driven decision-making. OEMs that develop modular and software-compatible vehicles will meet growing expectations for system interoperability. This creates opportunity for innovation, differentiation, and strategic partnerships across the industrial technology landscape.
Market Segmentation Analysis:
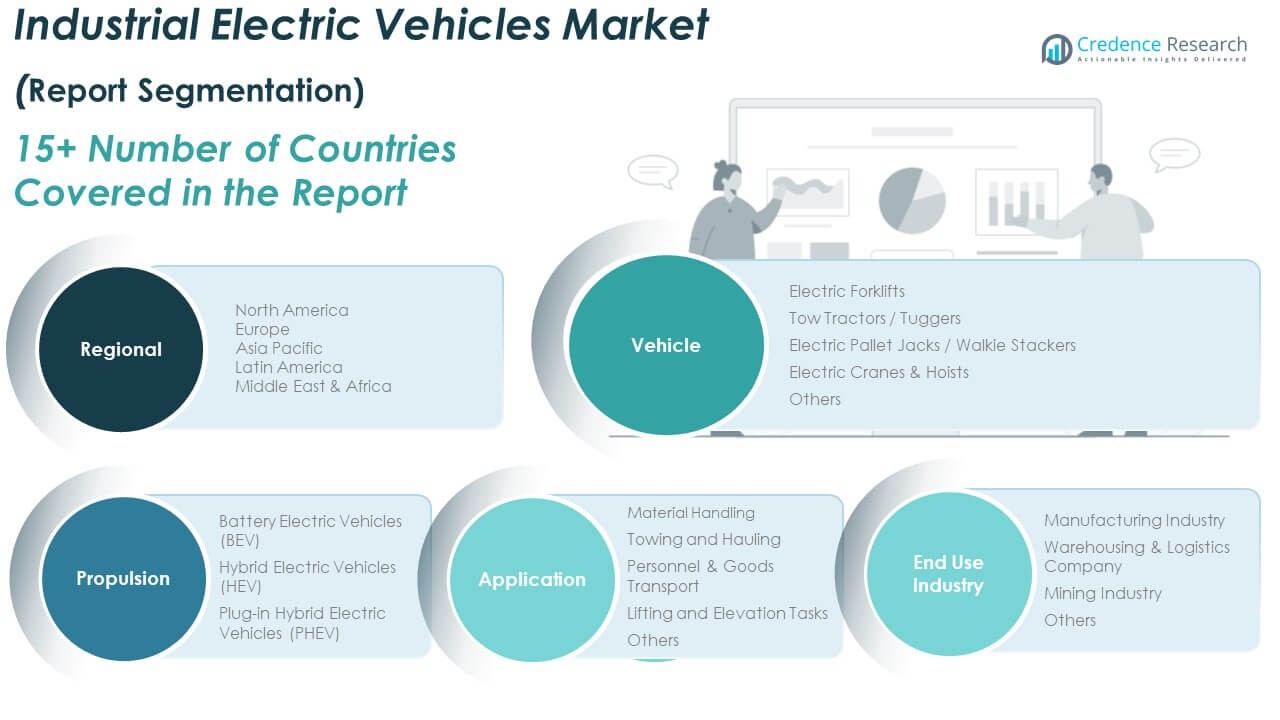
The Industrial Electric Vehicles Market is segmented across multiple categories, reflecting its diverse industrial applications and evolving propulsion technologies.
By vehicle type, electric forklifts account for the largest share due to widespread use in warehouses and manufacturing units, followed by tow tractors, pallet jacks, cranes, and specialized vehicles under the “others” category.
- For example, the Toyota 3-Wheel Electric Forklift, for example, offers a load capacity of up to 4,000 lbs and features Toyota’s AC drive motor, which extends run time by up to 20% compared to previous models.
By propulsion type into Battery Electric Vehicles (BEVs), Hybrid Electric Vehicles (HEVs), and Plug-in Hybrid Electric Vehicles (PHEVs), with BEVs leading due to zero-emission operations and reduced maintenance.
- For example, BYD’s ECB18C electric forklift uses an iron-phosphate battery with a 10-year warranty and zero emissions, reducing maintenance costs by up to 40% compared to internal combustion models.
By application, material handling dominates the market, supported by growing demand in logistics and production facilities. Towing, personnel transport, and lifting tasks also drive demand in automated and high-volume environments.
By end-user industry, manufacturing and warehousing lead adoption, while mining and others show potential for growth in rugged and remote operations.
Segmentation:
By Vehicle Segment:
- Electric Forklifts
- Tow Tractors / Tuggers
- Electric Pallet Jacks / Walkie Stackers
- Electric Cranes & Hoists
- Others
By Propulsion Type:
- Battery Electric Vehicles (BEV)
- Hybrid Electric Vehicles (HEV)
- Plug-in Hybrid Electric Vehicles (PHEV)
By Application:
- Material Handling
- Towing and Hauling
- Personnel & Goods Transport
- Lifting and Elevation Tasks
- Others
By End User Industry:
- Manufacturing Industry
- Warehousing & Logistics Companies
- Mining Industry
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
The North America Industrial Electric Vehicles Market size was valued at USD 4.96 million in 2018 to USD 8.50 million in 2024 and is anticipated to reach USD 17.21 million by 2032, at a CAGR of 9.20% during the forecast period. North America holds a strong position in the global industrial electric vehicles market, supported by rapid automation in logistics, warehouse modernization, and growing environmental regulations. The region benefits from advanced infrastructure and early adoption of emission-free transport solutions in industrial sectors. Companies across the U.S. and Canada are investing in zero-emission fleets to align with ESG mandates and reduce operational costs. The Industrial Electric Vehicles Market in this region is gaining traction across retail, e-commerce, and government-owned facilities. It supports both efficiency and sustainability goals in high-throughput operations. Demand is likely to remain strong, especially with ongoing investment in battery and autonomous technologies.
Europe
The Europe Industrial Electric Vehicles Market size was valued at USD 3.93 million in 2018 to USD 6.81 million in 2024 and is anticipated to reach USD 13.98 million by 2032, at a CAGR of 9.40% during the forecast period. Europe maintains a significant share of the market, driven by stringent carbon emission regulations and strong policy support for electrification. The region emphasizes sustainable industrial practices, prompting widespread adoption of electric fleets in manufacturing and logistics. Countries like Germany, France, and the Netherlands lead in deploying advanced warehouse automation systems. The Industrial Electric Vehicles Market in Europe benefits from a mature electric mobility ecosystem and high awareness of workplace safety standards. It continues to attract investment from OEMs offering low-noise, energy-efficient solutions. Integration with Industry 4.0 systems also fuels demand across key applications.
Asia Pacific
The Asia Pacific Industrial Electric Vehicles Market size was valued at USD 5.62 million in 2018 to USD 9.94 million in 2024 and is anticipated to reach USD 20.97 million by 2032, at a CAGR of 9.80% during the forecast period. Asia Pacific leads the global market in both volume and growth potential, accounting for the largest share due to industrial expansion, urbanization, and strong policy support. China, India, Japan, and South Korea are prioritizing electric mobility across industrial applications to reduce pollution and enhance energy efficiency. The Industrial Electric Vehicles Market benefits from large-scale warehouse automation and demand for agile, emission-free equipment. Governments across the region are offering subsidies and regulatory incentives to accelerate electrification. It supports high-volume manufacturing operations and cold chain logistics. Demand will likely continue growing with the expansion of smart industrial zones.
Latin America
The Latin America Industrial Electric Vehicles Market size was valued at USD 0.95 million in 2018 to USD 1.55 million in 2024 and is anticipated to reach USD 2.91 million by 2032, at a CAGR of 8.20% during the forecast period. Latin America is gradually embracing electric industrial vehicles as part of broader efforts to modernize logistics and reduce dependency on fossil fuels. Brazil and Mexico are leading early adoption, focusing on electric forklifts and warehouse vehicles in large distribution networks. The Industrial Electric Vehicles Market in the region is gaining visibility due to rising e-commerce activity and sustainability goals. It is still at a developing stage but offers untapped potential across agriculture, mining, and retail sectors. Infrastructure development and foreign investment are expected to boost adoption in coming years. Lower-cost, durable models will find strong traction across mid-sized businesses.
Middle East
The Middle East Industrial Electric Vehicles Market size was valued at USD 0.63 million in 2018 to USD 1.10 million in 2024 and is anticipated to reach USD 2.27 million by 2032, at a CAGR of 9.60% during the forecast period. The Middle East is emerging as a high-growth market, driven by efforts to diversify economies and invest in sustainable industrial practices. Countries such as the UAE and Saudi Arabia are implementing electrification plans for logistics, ports, and industrial parks. The Industrial Electric Vehicles Market supports national visions for reducing carbon emissions and enhancing energy efficiency. It plays a key role in smart city projects and high-tech warehousing zones. Increased government funding and partnerships with global OEMs are accelerating regional adoption. Market penetration is likely to deepen with more localized production and training support.
Africa
The Africa Industrial Electric Vehicles Market size was valued at USD 0.38 million in 2018 to USD 0.56 million in 2024 and is anticipated to reach USD 0.90 million by 2032, at a CAGR of 6.10% during the forecast period. Africa represents a nascent yet promising market for industrial electric vehicles, with early adoption centered around ports, mining, and infrastructure projects. South Africa leads the region, focusing on cleaner industrial practices and workplace safety improvements. The Industrial Electric Vehicles Market in Africa remains constrained by limited infrastructure and high upfront costs. It holds potential for growth through donor-backed green energy programs and private sector logistics investments. Continued economic development and energy reforms will be key to unlocking larger market volumes. Local adaptation and rugged, low-maintenance vehicle designs will be essential for long-term success.
Key Player Analysis:
- EP Equipment
- Toyota Material Handling
- KION Group (Linde, STILL)
- Jungheinrich AG
- Hyster-Yale Materials Handling
- Crown Equipment Corporation
- Mitsubishi Logisnext
- Doosan Industrial Vehicle
- Hangcha Group
- BYD Company Ltd.
- Clark Material Handling
- Komatsu Ltd.
- Caterpillar Inc. (via Mitsubishi/CAT Lift Trucks)
- Terberg Group
- Other Key Players
Competitive Analysis:
The Industrial Electric Vehicles Market is characterized by strong competition among global and regional players aiming to expand their portfolios and geographic reach. Key companies such as Toyota Industries Corporation, Jungheinrich AG, Kion Group, Hyster-Yale Materials Handling, and Mitsubishi Logisnext dominate the landscape with broad product offerings and advanced automation capabilities. It is witnessing increased investment in R&D, particularly in battery efficiency, autonomous systems, and telematics integration. Emerging players are focusing on niche applications and cost-effective models to capture market share in developing regions. Strategic partnerships, acquisitions, and technological innovations are central to gaining a competitive edge. Companies are also emphasizing sustainability and operational flexibility to meet evolving client demands. It remains dynamic, with rapid product development cycles and high responsiveness to regulatory changes and industry-specific needs. Competitive differentiation hinges on energy efficiency, customizability, total cost of ownership, and the ability to deliver fully integrated, smart fleet solutions.
Recent Developments:
- In June 2025, Tata Elxsi entered a strategic partnership with Infineon Technologies to co-develop advanced electric vehicle solutions for the Indian market. This collaboration leverages Infineon’s semiconductor expertise and Tata Elxsi’s design capabilities. It targets high-efficiency EV powertrain systems and embedded electronics systems tailored for industrial and commercial vehicles, signaling deeper integration of Indian OEMs in electrification endeavors.
- In May 2025, EP Equipment announced a strategic partnership with Jungheinrich AG to jointly shape the future of material handling. EP Equipment will support Jungheinrich’s portfolio expansion with a new Mid-Tech brand called “AntOn by Jungheinrich,” focusing on electric counterbalance and warehouse trucks. This collaboration aims to enhance efficiency, productivity, and sustainability globally by combining the strengths of both companies in lithium-ion powered material handling equipment.
- In January 2025, Wrightbus launched its Rightech sub-brand in partnership with JAC Motors and King Long, unveiling the RB6 and RB9 battery-electric buses alongside the Rightech RT75 electric box truck. This sub-brand focuses on zero-emission transport solutions for both public and commercial fleets.
Market Concentration & Characteristics:
The Industrial Electric Vehicles Market shows a moderate to high level of concentration, with a few established players holding significant market share across global and regional levels. It is defined by strong barriers to entry due to high capital requirements, advanced technology integration, and the need for robust after-sales support. The market favors companies with extensive distribution networks, R&D capabilities, and the ability to offer scalable, customizable solutions. It is characterized by growing demand for automation, low-emission operations, and energy efficiency across logistics, manufacturing, and warehousing sectors. Buyers emphasize total cost of ownership, battery performance, and system integration. The market evolves rapidly, driven by innovation cycles and regulatory shifts influencing product design and fleet deployment.
Report Coverage:
The research report offers an in-depth analysis based on Vehicle Segment, Propulsion Type, Application and End User Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for electric material-handling vehicles will rise with continued warehouse automation and e-commerce expansion.
- Integration of AI and telematics will enhance fleet optimization and predictive maintenance capabilities.
- Battery innovations will reduce charging time and extend operational range across industrial applications.
- Adoption will grow in emerging economies due to industrial expansion and green infrastructure investment.
- Government incentives and emissions regulations will accelerate fleet electrification across sectors.
- OEMs will focus on modular and customizable platforms to address varied operational needs.
- Strategic partnerships between logistics firms and manufacturers will drive product innovation.
- Autonomous industrial EVs will gain traction in high-volume, labor-intensive environments.
- Total cost of ownership will become a key differentiator in competitive procurement decisions.
- Sustainability goals and ESG compliance will continue to shape investment in electric vehicle technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Industrial Electric Vehicles Market?
What factors are driving the growth of the Industrial Electric Vehicles Market?
What are the key segments within the Industrial Electric Vehicles Market?
What are some challenges faced by the Industrial Electric Vehicles Market?
Who are the major players in the Industrial Electric Vehicles Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Industrial Electric Vehicles Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Industrial Electric Vehicles Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 28.5 million → 2032: USD 58.2 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Industrial Electric Vehicles Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Industrial Electric Vehicles Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Industrial Electric Vehicles Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Industrial Electric Vehicles Market Drivers
- 3.3 Industrial Electric Vehicles Market Restraints & Challenges
- 3.4 Industrial Electric Vehicles Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Industrial Electric Vehicles Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Industrial Electric Vehicles Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Industrial Electric Vehicles category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Industrial Electric Vehicles Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Industrial Electric Vehicles Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Industrial Electric Vehicles. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Industrial Electric Vehicles Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Industrial Electric Vehicles Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Industrial Electric Vehicles Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Industrial Electric Vehicles (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Industrial Electric Vehicles
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Industrial Electric Vehicles Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Industrial Electric Vehicles Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Industrial Electric Vehicles Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Industrial Electric Vehicles Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Industrial Electric Vehicles Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Industrial Electric Vehicles Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Industrial Electric Vehicles Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Industrial Electric Vehicles Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
