
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Industrial Wireless Sensor Network Market Size 2024 | USD 5792.04 million |
| Industrial Wireless Sensor Network Market, CAGR | 11.6% |
| Industrial Wireless Sensor Network Market Size 2032 | USD 13936.22 million |
Market Overview
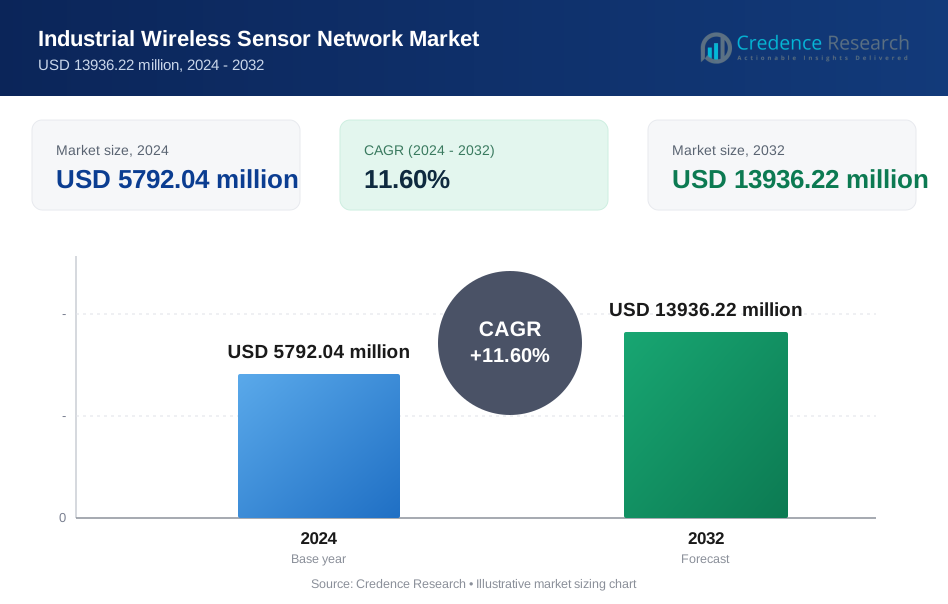
Industrial Wireless Sensor Network Market size was valued at USD 5792.04 million in 2024 and is anticipated to reach USD 13936.22 million by 2032, at a CAGR of 11.6% during the forecast period (2024-2032).
The primary drivers of the IWSN market include the growing adoption of Industry 4.0 and the Industrial Internet of Things (IIoT), which emphasizes the need for wireless connectivity and sensor systems for monitoring and controlling industrial operations. As industries move toward automation, the demand for efficient data transmission and connectivity continues to rise, positioning IWSNs as crucial enablers of these systems. The demand for real-time data analytics and predictive maintenance in industries like oil and gas, manufacturing, and energy production is further boosting the market. Additionally, the reduction in infrastructure costs and the ease of installation associated with wireless sensor networks are propelling their widespread adoption. These networks are seen as cost-effective solutions for improving productivity, minimizing risks, and ensuring asset integrity. The integration of advanced technologies like AI, machine learning, and cloud computing is also enhancing the capabilities of industrial wireless sensor networks, thereby accelerating their market growth. Furthermore, the increasing need for environmental monitoring and energy efficiency is driving the adoption of these networks in sectors like agriculture and water management.
Regionally, North America holds a significant share of the IWSN market due to the early adoption of smart technologies and a high concentration of industrial automation in the region. The presence of major industry players and research institutions further contributes to North America's leadership. The Asia-Pacific market is experiencing rapid growth, particularly in countries like China and India, driven by ongoing industrialization, government investments in smart manufacturing, and a growing focus on energy efficiency. In addition, the increasing demand for industrial automation and smart infrastructure is boosting the need for IWSNs in this region. Europe also plays a crucial role in the market, supported by stringent regulations around industrial safety and sustainability. The adoption of IWSNs is expected to increase across these regions as industries seek to improve operational efficiency and reduce environmental impact. Growing demand for energy-efficient technologies in sectors such as automotive and manufacturing will continue to drive market expansion in Europe.
Market Insights:
- The Industrial Wireless Sensor Network (IWSN) market is expected to grow significantly, reaching USD 13,936.22 million by 2032.
- Industry 4.0 and the Industrial Internet of Things (IIoT) are major drivers of IWSN adoption, emphasizing the need for wireless connectivity and sensor systems.
- Real-time data analytics and predictive maintenance are key factors pushing the demand for IWSNs, particularly in manufacturing and energy sectors.
- Wireless sensor networks offer cost-effective solutions by reducing infrastructure costs and simplifying installation, driving their widespread use.
- Technological advancements, including AI, machine learning, and cloud computing integration, are enhancing the capabilities of IWSNs and accelerating market growth.
- North America holds the largest market share at 35%, supported by high industrial automation and strong investments in IoT infrastructure.
- The Asia-Pacific region is the fastest-growing market, with a 30% share, driven by rapid industrialization, smart manufacturing investments, and government initiatives.
Market Drivers:
Adoption of Industry 4.0 and Industrial Internet of Things (IIoT)
The increasing adoption of Industry 4.0 and the Industrial Internet of Things (IIoT) is a primary driver for the growth of the Industrial Wireless Sensor Network (IWSN) market. Industry 4.0 emphasizes the integration of smart technologies into industrial environments, which requires efficient, real-time data exchange between machines, sensors, and systems. Wireless sensor networks enable the seamless connectivity needed for these smart environments, offering improved monitoring, automation, and control. By supporting applications such as predictive maintenance, asset tracking, and real-time condition monitoring, IWSNs play a key role in enhancing operational efficiency across industries like manufacturing, oil and gas, and energy.
Demand for Real-Time Data and Predictive Maintenance
As industries strive to optimize operations and reduce downtime, there is an increasing demand for real-time data analytics and predictive maintenance. Wireless sensor networks are central to enabling this shift by providing accurate, on-demand data on machinery conditions, performance, and environmental factors. For instance, Siemens has implemented wireless sensor networks in manufacturing environments to enable continuous monitoring of critical assets such as motors and turbines, supporting predictive maintenance strategies that reduce unplanned downtime and extend equipment life. These networks allow for continuous monitoring of equipment health, facilitating early detection of potential failures and reducing unplanned downtime. In sectors like manufacturing and energy production, where operational continuity is crucial, the use of IWSNs to enhance maintenance strategies is driving significant market demand. This predictive capability lowers operational costs and ensures that assets are operating at their maximum potential.
Cost Reduction and Ease of Installation
One of the most attractive features of wireless sensor networks is their ability to reduce infrastructure costs and simplify installation processes. Unlike wired networks, which require extensive cabling and complex setup, wireless networks reduce the need for costly physical infrastructure and allow for easier scalability. For example, the General Services Administration (GSA) in the United States conducted a broad deployment of wireless sensor networks across federal data centers, finding that these systems could be installed with minimal power interruptions and provided immediate benefits in operational efficiency and energy savings. The installation of IWSNs is less intrusive and can be implemented without major disruptions to ongoing operations. For businesses looking to minimize capital expenditures while still achieving advanced monitoring capabilities, IWSNs offer a cost-effective solution. The simplicity and flexibility of these systems make them appealing to companies across diverse industries, from manufacturing to logistics.
Technological Advancements and Integration with AI and Cloud Computing
Technological advancements are also driving the growth of the IWSN market. The integration of AI, machine learning, and cloud computing technologies with wireless sensor networks is significantly enhancing their capabilities. AI algorithms enable data processing, anomaly detection, and predictive analytics, allowing businesses to gain deeper insights and make data-driven decisions. Additionally, cloud computing facilitates centralized data storage and remote monitoring, enabling businesses to access real-time information from any location. These advancements increase the value of IWSNs by offering not only data collection but also intelligent analysis, further accelerating their adoption across industries such as manufacturing, logistics, and energy management.
Market Trends:
Integration with IoT and Smart Devices
One of the key trends driving the Industrial Wireless Sensor Network (IWSN) market is the increasing integration with the Internet of Things (IoT) and smart devices. As industries move toward greater automation and digitization, wireless sensor networks are playing a critical role in connecting machines, sensors, and devices to create a cohesive and intelligent system. These IoT-enabled systems allow for real-time data transmission and remote monitoring, which improves operational efficiency, predictive maintenance, and decision-making. The rise of IoT in industries such as manufacturing, logistics, and energy is propelling the demand for IWSNs.
Adoption of Edge Computing
Another notable trend is the growing adoption of edge computing in conjunction with IWSNs. Edge computing enables data processing closer to the source of data generation, reducing latency and improving response times. For instance, Digi International’s Remote Manager® platform is used in oil and gas plants to process sensor data on-site, allowing real-time responses that prevent small problems from escalating into major failures-especially valuable in remote locations where connectivity to central data centers is limited. This is particularly beneficial in industries where real-time decision-making is critical, such as manufacturing and energy production. By processing data at the edge, IWSNs can operate more efficiently and provide faster insights without overwhelming centralized systems. The trend towards edge computing is boosting the performance and scalability of industrial wireless sensor networks.
Advancements in Sensor Technology
There is also a growing trend toward advancements in sensor technology, which are enhancing the capabilities of industrial wireless sensor networks. For instance, NXP Semiconductors introduced its Advanced Connected MCX W Wireless MCU series in April 2024, a significant leap in microcontroller technology that enables smarter and more efficient wireless sensor deployments in industrial and IoT environments. New sensor technologies, such as miniaturized sensors with greater sensitivity and accuracy, are enabling IWSNs to capture more precise data in diverse industrial environments. These advancements are driving the adoption of IWSNs in more applications, including hazardous or remote locations where traditional wired sensors may not be viable.
Focus on Energy Efficiency and Sustainability
The increasing focus on energy efficiency and sustainability is another trend influencing the IWSN market. Wireless sensor networks are being utilized to monitor energy consumption, reduce waste, and optimize operations in industries such as manufacturing and utilities. The growing emphasis on environmental impact and sustainability is encouraging businesses to adopt more energy-efficient solutions, further promoting the use of IWSNs for operational optimization and sustainability goals.
Market Challenges Analysis:
Security Concerns and Data Privacy
One of the primary challenges faced by the Industrial Wireless Sensor Network (IWSN) market is ensuring robust security and data privacy. As IWSNs transmit sensitive operational data across wireless channels, they become vulnerable to cyber-attacks, hacking, and data breaches. For instance, companies such as Cisco have addressed these concerns with their Secure Wireless Plant solution, which integrates advanced security measures like wireless-device host intrusion prevention, an integrated authentication framework, and support for WPA and WPA2 security standards to safeguard sensor data transmission in industrial environments. The risks of these security breaches extend beyond financial loss, as they could lead to significant operational disruptions or compromise intellectual property. Industries relying on IWSNs for critical applications, such as manufacturing, oil and gas, and energy, require secure networks to protect proprietary information and operational integrity. The lack of standardized security protocols and the complexity of securing diverse wireless networks across various industrial environments pose significant challenges for organizations. To mitigate these risks, businesses must invest in advanced encryption techniques, authentication methods, and continuous monitoring systems, which can increase operational costs. Additionally, the evolving nature of cyber threats necessitates ongoing updates and adaptive security measures, further adding to the burden of ensuring data privacy and system protection.
Integration with Legacy Systems
Another challenge lies in the integration of wireless sensor networks with existing legacy systems. Many industries still rely on outdated infrastructure and equipment that is not designed to accommodate modern IWSNs. The compatibility issues between old and new systems can result in operational disruptions and inefficiencies during integration. Moreover, the lack of skilled personnel who can effectively manage and implement these complex integrations adds an additional layer of difficulty. Overcoming these integration challenges requires significant investment in system upgrades, training, and a phased implementation approach to ensure seamless interoperability and full utilization of IWSNs within established industrial environments. As industries continue to evolve, the need to integrate emerging technologies with legacy systems will increase, making it crucial for companies to plan for long-term compatibility and scalability.
Market Opportunities:
The Industrial Wireless Sensor Network (IWSN) market presents significant opportunities driven by the increasing demand for smart manufacturing, automation, and real-time data analysis. As industries continue to embrace digital transformation, there is a growing need for connected systems that enable efficient monitoring, predictive maintenance, and decision-making. The integration of wireless sensor networks into the Industrial Internet of Things (IIoT) ecosystem creates opportunities for businesses to enhance operational efficiency, reduce downtime, and optimize asset management. Additionally, advancements in sensor technology, such as miniaturization and improved accuracy, offer new avenues for IWSNs to expand into various industries, including energy, agriculture, and logistics. These innovations enable the adoption of wireless networks in previously inaccessible or remote locations, further broadening the market's potential.
Moreover, the rising focus on sustainability and energy efficiency in industrial operations presents a significant opportunity for IWSN adoption. Wireless sensor networks can play a crucial role in monitoring energy consumption, reducing waste, and improving resource utilization. As governments and organizations implement stricter environmental regulations, industries are increasingly turning to IWSNs to ensure compliance and reduce their environmental footprint. The growing emphasis on sustainability in sectors such as manufacturing, utilities, and agriculture opens up new market prospects for IWSN solutions. With the continuous advancement of technology and the push toward green energy practices, the market for IWSNs is expected to experience strong growth in the coming years.
Market Segmentation Analysis:
By Component
The Industrial Wireless Sensor Network (IWSN) market is segmented into sensors, transmitters, receivers, and other components. Sensors account for the largest share of the market, as they are crucial for collecting data from various industrial operations. These sensors are used for monitoring temperature, humidity, pressure, vibration, and other key parameters in real-time. Transmitters and receivers are also essential in ensuring seamless data transmission and communication between sensors and central monitoring systems, enabling real-time analytics and decision-making.
By Technology
The market is divided into several technologies, including Bluetooth Low Energy (BLE), Zigbee, LoRaWAN, and Wi-Fi. Among these, LoRaWAN technology is growing in prominence due to its long-range capabilities and low power consumption, making it ideal for large-scale industrial applications. BLE and Zigbee are widely adopted for short-range communication, particularly in environments that require fast data exchange. Wi-Fi remains popular in applications where higher bandwidth and faster data transfer are necessary.
By Application
The IWSN market finds applications across various industries such as manufacturing, oil and gas, energy, and logistics. Manufacturing holds the largest market share, driven by the need for real-time condition monitoring, predictive maintenance, and automation. The energy sector also contributes significantly to market growth, with IWSNs used for monitoring energy consumption, improving efficiency, and ensuring safety in power plants and other energy-related infrastructure.
Segmentations:
By Component
- Sensors
- Transmitters
- Receivers
- Others
By Technology
- Bluetooth Low Energy (BLE)
- Zigbee
- LoRaWAN
- Wi-Fi
- Others
By Application
- Manufacturing
- Oil and Gas
- Energy
- Logistics
- Healthcare
- Agriculture
- Others
By Sensor Network
- Mesh Networks
- Star Networks
- Hybrid Networks
By End-Use
- Industrial Automation
- Environmental Monitoring
- Predictive Maintenance
- Asset Tracking
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
North America holds the largest share of the Industrial Wireless Sensor Network (IWSN) market, accounting for 35% of the global market. The region's dominance is driven by advanced technological adoption, a high concentration of industrial automation, and substantial investments in IoT infrastructure. The presence of key market players, such as Honeywell, Siemens, and Bosch, further contributes to North America’s market share. Industries in the region, including manufacturing, oil and gas, and energy, are increasingly integrating IWSNs to enhance operational efficiency, reduce downtime, and support predictive maintenance. Additionally, regulatory initiatives and government support for smart infrastructure are expected to drive further adoption of IWSNs across North America, solidifying its market leadership. The region's robust demand for smart cities and automated solutions will continue to stimulate growth in the coming years.
Asia-Pacific
Asia-Pacific is the fastest-growing region in the IWSN market, with a market share of 30%. The growth in this region is fueled by rapid industrialization, particularly in countries like China and India, where there is a significant push towards modernizing manufacturing processes and adopting automation technologies. The rise of smart cities, increased investments in IoT, and government-led initiatives to enhance industrial safety and energy efficiency further boost the demand for wireless sensor networks. The region also benefits from the growing adoption of smart manufacturing, environmental monitoring, and predictive maintenance solutions, contributing to the accelerated growth of IWSNs in Asia-Pacific. Additionally, Asia-Pacific’s expanding focus on industrial digitalization and energy management supports its increasing adoption of IWSNs.
Europe
Europe holds a 25% share of the global IWSN market, supported by stringent regulations on industrial safety and energy efficiency. The region's advanced manufacturing sector, combined with its focus on sustainability and environmental monitoring, is driving the adoption of IWSNs. Countries such as Germany, France, and the UK are leading the way in industrial automation, integrating wireless sensor networks to optimize production processes, ensure asset reliability, and enhance safety protocols. Additionally, the increasing demand for smart grids, smart factories, and real-time condition monitoring in energy and manufacturing industries further strengthens the growth of IWSNs in Europe. The region’s commitment to reducing carbon footprints and improving energy efficiency through automation technology is likely to foster sustained market growth, further accelerating the implementation of IWSNs across key sectors.
Key Player Analysis:
- Cisco Systems, Inc.
- Huawei Technologies Co., Ltd.
- Analog Devices, Inc.
- Texas Instruments Incorporated
- Advantech Co., Ltd.
- Honeywell International Inc.
- NXP Semiconductors
- Sensirion AG
- Intel Corporation
- ABB
Competitive Analysis:
The Industrial Wireless Sensor Network (IWSN) market is highly competitive, with key players striving to meet the growing demand for efficient, scalable, and secure solutions across various industries. Leading companies like Honeywell, Siemens, and Bosch dominate the market, offering a wide range of wireless sensor networks tailored for industrial applications, including manufacturing, energy, and automation. These companies differentiate themselves by leveraging advanced technologies, such as IoT, AI, and edge computing, to enhance the functionality and performance of their wireless sensor systems.
Smaller players, such as Advantech and NXP Semiconductors, focus on specialized applications, including environmental monitoring and predictive maintenance, offering innovative products like LoRaWAN-based sensors and multi-protocol wireless MCUs. The competition is also fueled by ongoing advancements in sensor technology, low-power solutions, and network integration. As demand for real-time data and IoT connectivity continues to rise, these companies are expected to increasingly innovate to maintain market leadership.
Recent Developments:
- In April 2024, Advantech formed a strategic partnership with Qualcomm Technologies to reshape the edge computing landscape. This collaboration focuses on the development of an open and versatile edge AI ecosystem designed to support Artificial Internet of Things (AIoT) applications. The partnership aims to overcome the challenges associated with deploying AI at the edge and is expected to have a significant impact across industries such as industrial automation, transportation, robotics, and more.
- In February 2024, at MWC Barcelona, Huawei launched ten new industrial digital and intelligent transformation solutions, including new flagship products designed to accelerate digitalization and intelligence in manufacturing and other industries.
Market Concentration & Characteristics:
The Industrial Wireless Sensor Network (IWSN) market is moderately concentrated, with a few key players holding significant market share, including established companies like Honeywell, Siemens, and Bosch. These leaders dominate through their broad portfolios, strong technological expertise, and established customer bases in industries such as manufacturing, energy, and automation. However, the market also features numerous smaller players, such as Advantech and NXP Semiconductors, which focus on niche applications like environmental monitoring and predictive maintenance. These companies differentiate themselves through specialized product offerings and innovative technologies, including low-power sensors and advanced communication protocols like LoRaWAN and BLE. The market is characterized by rapid technological advancements, including the integration of IoT, AI, and edge computing, which drive continuous innovation. As the demand for real-time data, energy efficiency, and IoT connectivity increases, competition is expected to intensify, encouraging both larger and smaller players to continuously refine their offerings.
Report Coverage:
The research report offers an in-depth analysis based on Component, Technology, Application, Sensor Network, End-Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Industrial Wireless Sensor Network (IWSN) market will continue to expand as industries increasingly adopt IoT and automation technologies.
- Advancements in wireless sensor technology, such as improved battery life and enhanced data transmission, will drive further adoption.
- The integration of artificial intelligence (AI) and machine learning (ML) with IWSNs will enable predictive maintenance and real-time decision-making.
- Demand for energy-efficient solutions will push the adoption of wireless sensor networks, especially in industries focused on sustainability and reducing operational costs.
- The rise of Industry 4.0 and smart factories will significantly contribute to the growth of IWSNs as key enablers of digital transformation.
- Enhanced security features, including encryption and authentication, will become critical to safeguarding industrial wireless networks from cyber threats.
- The development of low-power wide-area network (LPWAN) technologies like LoRaWAN will further facilitate the scalability of wireless sensor networks in remote and large-scale industrial environments.
- The increasing focus on environmental monitoring and asset tracking will create new opportunities for IWSN applications in industries such as agriculture and logistics.
- Real-time monitoring of industrial equipment and infrastructure will continue to be a significant driver for IWSNs in sectors like energy, manufacturing, and oil and gas.
- The market will see increased regional growth in Asia-Pacific, driven by industrialization and government initiatives to modernize infrastructure and manufacturing practices.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Industrial Wireless Sensor Network (IWSN) market?
What are the primary drivers of the IWSN market?
Which regions are leading in the IWSN market?
How is the demand for energy efficiency affecting the IWSN market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5792.04 million → 2032: USD 13936.22 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Industrial Wireless Sensor Network Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Industrial Wireless Sensor Network Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Industrial Wireless Sensor Network Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Industrial Wireless Sensor Network Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Industrial Wireless Sensor Network Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Industrial Wireless Sensor Network Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Industrial Wireless Sensor Network Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Industrial Wireless Sensor Network Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5792.04 million → 2032: USD 13936.22 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Industrial Wireless Sensor Network Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Industrial Wireless Sensor Network Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Industrial Wireless Sensor Network Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Industrial Wireless Sensor Network Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
