
Market Overview:
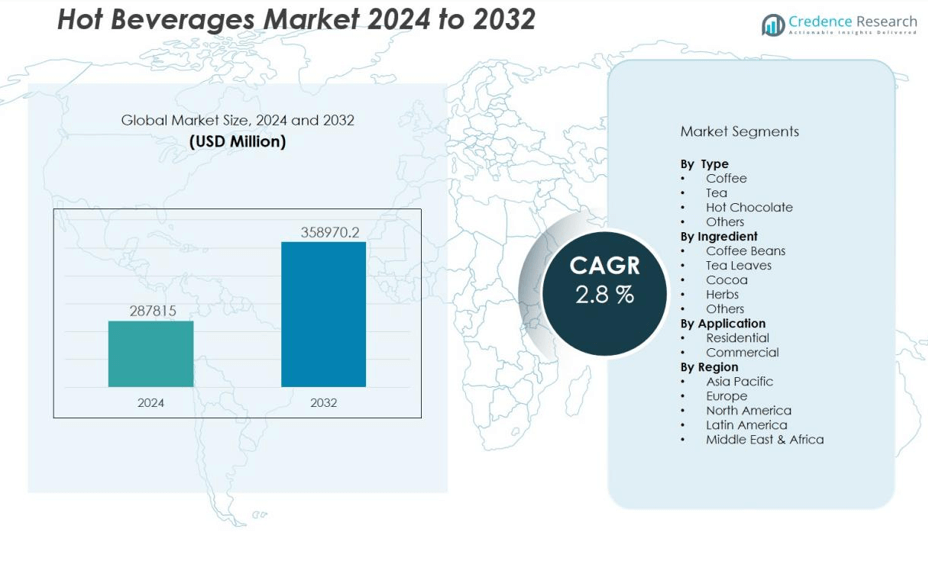
The hot beverages market size was valued at USD 287815 million in 2024 and is anticipated to reach USD 358970.2 million by 2032, at a CAGR of 2.8 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hot Beverages Market Size 2024 | USD 287815 million |
| Hot Beverages Market, CAGR | 2.8% |
| Hot Beverages Market Size 2032 | USD 358970.2 million |
Market growth is driven by rising health and wellness awareness, which has boosted demand for herbal and functional hot beverages with added nutritional benefits. The increasing popularity of specialty coffee, artisanal tea blends, and ready-to-drink hot beverage formats is reshaping consumption trends. Technological advancements in brewing equipment, coupled with expanding café culture and home-brewing convenience, are further driving adoption. Sustainability initiatives, including eco-friendly packaging and fair-trade sourcing, are also influencing purchase decisions.
Regionally, Asia-Pacific dominates the hot beverages market, supported by strong tea consumption in China, India, and Japan, alongside rising coffee adoption among younger consumers. Europe remains a key market, driven by a long-standing café culture and premiumization trends, while North America is witnessing strong growth in specialty coffee and health-focused beverage segments.
Market Insights:
- The hot beverages market was valued at USD 287,815 million in 2024 and is projected to reach USD 358,970.2 million by 2032, growing at a CAGR of 2.8%.
- Rising health and wellness awareness is boosting demand for herbal teas, green tea, and functional beverages enriched with antioxidants, vitamins, and adaptogens.
- Specialty coffee and artisanal tea culture are expanding, supported by café proliferation, single-origin offerings, and ethically sourced products.
- Technological advancements in brewing equipment, e-commerce platforms, and subscription models are enhancing accessibility and consumer convenience.
- Sustainability commitments, including eco-friendly packaging, recyclable materials, and fair-trade sourcing, are shaping purchase decisions.
- Asia-Pacific leads with 42% market share, followed by Europe at 28% and North America at 20%, each driven by unique cultural and consumption trends.
- Market challenges include fluctuating raw material prices, intense competition, and shifting preferences toward low-sugar, plant-based, and ready-to-drink alternatives.
Market Drivers:
Rising Consumer Preference for Health and Wellness-Oriented Beverages:
The growing awareness of health and wellness is significantly influencing consumer choices in the hot beverages market. Demand for herbal teas, green tea, and functional beverages enriched with antioxidants, vitamins, and adaptogens is accelerating. Consumers are increasingly opting for low-sugar, natural, and organic options that align with preventive health trends. This shift is prompting manufacturers to expand portfolios with products that offer both flavor and functional benefits, strengthening their market position.
- For instance, Matcha green tea from brands such as Tradition Matcha is scientifically proven to contain up to 1,968.8mg/L of flavonoids and 1,765.1mg/L of polyphenols per liter, making it one of the highest antioxidant beverages available in the category.
Expansion of Specialty Coffee and Premium Tea Culture:
The surge in specialty coffee and artisanal tea consumption is a major growth driver. Urban consumers are seeking unique flavors, single-origin varieties, and ethically sourced products. The proliferation of coffeehouses, tea lounges, and specialty cafés has elevated beverage experiences, encouraging premium purchases. The hot beverages market benefits from this trend through higher value sales and increased customer loyalty toward quality-focused brands.
- For instance, Nespresso’s VertuoLine machines spin coffee capsules at up to 7,000 RPM to achieve uniform infusion and a velvety crema on every cup.
Technological Advancements in Brewing and Distribution Channels:
Advancements in brewing equipment, from single-serve machines to smart coffee makers, are enhancing convenience for both households and commercial establishments. E-commerce platforms and subscription models are expanding product accessibility, allowing brands to reach a broader audience. It leverages these innovations to improve distribution efficiency and strengthen brand presence. This integration of technology is reshaping consumer engagement and purchasing habits.
Sustainability and Ethical Sourcing Driving Brand Differentiation:
Sustainability has become a core purchasing criterion, influencing packaging choices and sourcing strategies. Consumers are favoring brands committed to fair trade, eco-friendly packaging, and traceable supply chains. The hot beverages market is responding by adopting recyclable materials and supporting ethical farming practices. These initiatives not only meet regulatory requirements but also enhance brand credibility in competitive markets.
Market Trends:
Premiumization and Diversification of Product Portfolios:
The shift toward premium and diverse beverage options is reshaping the competitive landscape of the hot beverages market. Consumers are increasingly drawn to specialty coffee, artisanal tea blends, and limited-edition seasonal flavors that deliver unique taste experiences. Brands are introducing single-origin and micro-lot varieties to cater to discerning buyers who value authenticity and provenance. Functional ingredients, such as adaptogens, probiotics, and plant-based alternatives, are being incorporated to enhance nutritional value. It is also expanding into fusion beverages that combine traditional flavors with contemporary twists to capture younger demographics. The trend is driving higher price points and strengthening customer loyalty in both retail and foodservice channels.
- For instance, Keurig Dr Pepper’s K-Brew + Chill brewer, introduced in fall 2024, employs QuickChill™ Technology to deliver coffee three times colder than its prior Brew-Over-Ice method in under 3 minutes.
Integration of Technology and Sustainable Practices in Operations:
Technological innovation is influencing how consumers purchase and prepare hot beverages. Smart brewing devices, mobile ordering, and subscription-based delivery models are becoming mainstream, offering convenience and personalization. E-commerce platforms are enabling direct-to-consumer engagement, supported by targeted digital marketing campaigns. The hot beverages market is adopting sustainable practices, such as compostable packaging, carbon-neutral production, and ethical sourcing, to meet evolving consumer expectations. It is also witnessing collaborations between beverage brands and technology companies to create interactive customer experiences. This combination of digital transformation and sustainability is shaping long-term competitive strategies across the industry.
- For instance, Keurig Dr Pepper shipped 9.7 million single-serve coffee brewers in the 12 months ending December 31, 2023.
Market Challenges Analysis:
Fluctuating Raw Material Prices and Supply Chain Vulnerabilities:
Volatility in the prices of key raw materials such as coffee beans, tea leaves, cocoa, and dairy products poses a significant challenge for the hot beverages market. Unpredictable weather patterns, geopolitical tensions, and trade restrictions disrupt supply stability and increase production costs. Small and medium-sized brands face higher pressure in maintaining profit margins amid fluctuating input expenses. It also contends with logistical bottlenecks, including port delays and transportation shortages, which can hinder timely distribution. These challenges demand agile sourcing strategies and strong supplier relationships to sustain market competitiveness.
Intense Competition and Shifting Consumer Preferences:
The market faces strong competition from both global brands and local players offering niche, innovative products. Rapidly changing consumer preferences toward healthier, low-sugar, and plant-based options require continuous product adaptation. Failure to meet these evolving demands risks losing market share to agile competitors. The hot beverages market must also address the growing popularity of ready-to-drink cold beverages, which can divert consumer spending. It requires sustained investment in research, product development, and marketing to retain relevance and customer loyalty in a crowded landscape.
Market Opportunities:
Expansion into Functional and Health-Focused Beverage Segments:
The growing demand for beverages that offer health benefits presents a strong opportunity for the hot beverages market. Functional teas, fortified coffees, and herbal infusions with immunity-boosting or stress-relieving properties are gaining popularity among health-conscious consumers. Brands can leverage this trend by innovating with superfoods, adaptogens, and plant-based ingredients. It can also expand product lines to include options catering to specific dietary needs, such as vegan, keto-friendly, or gluten-free. Strategic collaborations with nutrition experts and wellness influencers can further strengthen market positioning. This focus on functional offerings aligns with global wellness trends and supports premium pricing potential.
Leveraging Digital Channels and Emerging Markets for Growth:
The rapid expansion of e-commerce and subscription-based delivery models creates new avenues for brand reach and customer engagement. The hot beverages market can capitalize on direct-to-consumer platforms to personalize product recommendations and build loyalty. Growing middle-class populations in emerging markets, coupled with rising disposable incomes, provide fertile ground for market expansion. Urbanization and café culture adoption in Asia, Africa, and Latin America offer untapped sales potential. It can also benefit from targeted marketing strategies and localized product innovations to appeal to regional tastes. These opportunities can significantly enhance market penetration and revenue streams in the coming years.
Market Segmentation Analysis:
By Type:
The hot beverages market is segmented into coffee, tea, hot chocolate, and others. Coffee holds the largest share, driven by the rising popularity of specialty brews, single-origin varieties, and café culture. Tea remains a strong segment, supported by deep-rooted consumption habits in Asia and growing demand for herbal and green tea in global markets. Hot chocolate appeals to both younger consumers and indulgence-seeking adults, with premium and artisanal variants gaining traction.
- For instance, Twinings reached over 4.84 million consumers for its herbal and green tea varieties in the UK in 2023, showing robust demand for premium blends.
By Ingredient:
Key ingredients include coffee beans, tea leaves, cocoa, herbs, and others. Coffee beans lead the segment due to strong consumption in both retail and foodservice channels. Tea leaves see consistent demand, with specialty and organic variants attracting health-conscious buyers. Cocoa remains integral to the hot chocolate segment, while herbs such as chamomile, ginger, and peppermint are increasingly used in functional blends. It benefits from the rising interest in natural and ethically sourced raw materials.
- For instance, Nestlé's Abuelita Mexican Style Hot Chocolate Mix uses cocoa sourced under the Nestlé Cocoa Plan, offering an 18-month shelf life and is produced in 2lb bulk pouches for commercial and retail use.
By Application:
Applications span residential and commercial use. Residential consumption is supported by convenient brewing devices and expanding e-commerce availability. Commercial applications, including cafés, restaurants, hotels, and corporate spaces, drive significant sales through premium beverage offerings. Seasonal menus, on-site brewing technology, and experiential service formats further enhance growth in this segment.
Segmentations:
By Type:
- Coffee
- Tea
- Hot Chocolate
- Others
By Ingredient:
- Coffee Beans
- Tea Leaves
- Cocoa
- Herbs
- Others
By Application:
- Residential
- Commercial
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
Asia-Pacific :
Asia-Pacific holds 42% market share in the global hot beverages market, driven by its deep-rooted tea culture and expanding coffee consumption. China, India, and Japan remain dominant tea markets, while Southeast Asian countries are experiencing rapid growth in specialty coffee demand. Rising disposable incomes and urban lifestyles are fueling café culture and premium product adoption. It benefits from strong retail networks, growing e-commerce penetration, and a young consumer base eager to try new flavors. Health-focused products, such as green tea and herbal infusions, are gaining traction among middle-class households. Government initiatives supporting agricultural development further strengthen the supply base.
Europe :
Europe commands 28% market share, supported by a long-established coffeehouse and tea tradition. The region exhibits strong demand for specialty and organic hot beverages, particularly in countries like the UK, Germany, France, and Italy. Premiumization trends are evident in the popularity of single-origin coffee and artisanal tea blends. The hot beverages market benefits from well-developed distribution infrastructure and a high preference for ethically sourced products. Sustainability commitments, such as recyclable packaging and fair-trade certifications, are key purchase drivers. Seasonal and festive product launches remain popular across retail and hospitality channels.
North America :
North America holds 20% market share, fueled by the popularity of premium coffee, health-oriented beverages, and on-the-go formats. The United States leads consumption, with a strong presence of global café chains and innovative local roasters. Consumer interest in plant-based creamers, low-sugar hot chocolate, and fortified teas is expanding the product mix. It benefits from advanced brewing technology adoption and high per-capita beverage spending. Direct-to-consumer models and subscription services are gaining traction, enhancing brand loyalty. Seasonal flavors and limited-edition offerings continue to boost sales in both retail and foodservice channels.
Key Player Analysis:
- Celestial Seasonings,
- Harney & Sons
- Costa Limited
- Dilmah
- Nestlé S.A.
- JAB Holding Company
- Smucker Company
- JDB (China) Beverages Ltd.
- Jacobs Douwe Egberts
- Kraft Heinz Company
- McCafé
- Luigi Lavazza S.p.A.
- Twini
Competitive Analysis:
The hot beverages market is highly competitive, with global brands and regional specialists competing for market share through product innovation, brand positioning, and distribution strength. Leading players such as Celestial Seasonings, Inc., Harney & Sons, Costa Limited, Dilmah, Nestlé S.A., McCafé, Luigi Lavazza S.p.A., and R. Twining & Company maintain strong portfolios spanning coffee, tea, and specialty beverages. It is characterized by high brand loyalty, where consumer preferences are shaped by flavor variety, ethical sourcing, and quality consistency. Companies invest heavily in sustainable practices, premium product lines, and health-focused formulations to align with evolving market trends. Strategic partnerships, acquisitions, and expansion into e-commerce are key tactics to enhance reach and engagement. Innovation in brewing technology, seasonal offerings, and functional beverage formulations continues to be a core differentiator in strengthening competitive advantage.
Recent Developments:
- In April 2025, Nestlé S.A. initiated its largest-ever agroforestry partnership with OFI (Olam Food Ingredients), aiming to train 25,000 cocoa farmers and plant 2.8 million trees in Nigeria, Côte d’Ivoire, and Brazil.
- In May 2025, Dilmah and Emirates celebrated 33 years of partnership, highlighting over 33 million cups of Dilmah tea served annually on Emirates flights.
Market Concentration & Characteristics:
The hot beverages market exhibits moderate concentration, with a mix of global corporations and strong regional players competing across product categories. Leading brands such as Nestlé, Starbucks, Unilever, JDE Peet’s, and Tata Consumer Products dominate through extensive distribution networks, diversified portfolios, and strong brand equity. It is characterized by high product differentiation, frequent innovation in flavors and formats, and increasing emphasis on premium and functional offerings. Consumer loyalty plays a critical role, driven by consistent quality and brand reputation. Market dynamics are influenced by seasonal demand shifts, evolving health trends, and sustainability initiatives. E-commerce expansion and café culture growth continue to reshape competitive positioning.
Report Coverage:
The research report offers an in-depth analysis based on Type, Ingredient, Application and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Demand for functional hot beverages with added health benefits will continue to grow, driven by consumer focus on wellness and preventive nutrition.
- Specialty coffee and premium tea segments will expand further, supported by rising urban café culture and evolving taste preferences.
- Brands will increasingly invest in sustainable sourcing, recyclable packaging, and carbon-neutral production to meet environmental expectations.
- Digital sales channels, including e-commerce platforms and subscription-based models, will strengthen market accessibility and customer retention.
- Emerging markets in Asia, Africa, and Latin America will witness faster adoption due to growing middle-class populations and urbanization.
- Product innovation will focus on unique flavor combinations, fusion beverages, and plant-based alternatives to cater to diverse dietary needs.
- Smart brewing devices and personalized beverage technology will enhance consumer convenience and engagement.
- Seasonal, limited-edition, and culturally inspired product launches will play a vital role in driving short-term sales spikes.
- Strategic collaborations between beverage brands, cafés, and technology companies will boost experiential marketing and brand visibility.
- Health-focused and ethically positioned brands will gain a competitive edge as conscious consumption shapes purchasing decisions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Health and Wellness Awareness
Consumers are increasingly seeking hot beverages with functional benefits, such as herbal teas, green tea, and drinks enriched with antioxidants and adaptogens, driving manufacturers to innovate and expand health-oriented product lines.
Expansion of Specialty Coffee and Premium Tea Culture
The proliferation of specialty cafés and demand for unique, single-origin, and ethically sourced beverages are elevating consumer expectations and increasing premium product sales across both coffee and tea segments.
Technological Advancements in Brewing and Distribution
Smart brewing devices, single-serve machines, and e-commerce platforms are making hot beverages more accessible and convenient, supporting both at-home and commercial consumption growth.
Sustainability and Ethical Sourcing
Rising consumer preference for eco-friendly packaging, fair-trade sourcing, and traceable supply chains is prompting brands to adopt sustainable practices, which enhances brand loyalty and market differentiation.
Growth of Café Culture and Urbanization in Emerging Markets
Rapid urbanization and rising disposable incomes in Asia Pacific, Africa, and Latin America are fueling café culture and increasing demand for premium and innovative hot beverage offerings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the hot beverages market, and what is its projected size in 2032?
Which hot beverages market segment held the largest share in 2024?
Who are the leading companies in the hot beverages market?
Which region commanded the largest share of the hot beverages market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Coffee
- 1.2.2 Tea
- 1.2.3 Hot Chocolate
- 1.2.4 Others
- 1.3 By Ingredient
- 1.3.1 Coffee Beans
- 1.3.2 Tea Leaves
- 1.3.3 Cocoa
- 1.3.4 Herbs
- 1.3.5 Others
- 1.4 By Application
- 1.4.1 Residential
- 1.4.2 Commercial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 287,815 million → 2032: USD 358,970.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hot Beverages Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hot Beverages Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hot Beverages Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hot Beverages Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hot Beverages Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hot Beverages Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hot Beverages Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hot Beverages Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 287,815 million → 2032: USD 358,970.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hot Beverages Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Coffee
- 12.3.7.2 Tea
- 12.3.7.3 Hot Chocolate
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Ingredient - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Coffee Beans
- 12.4.7.2 Tea Leaves
- 12.4.7.3 Cocoa
- 12.4.7.4 Herbs
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Residential
- 12.5.7.2 Commercial
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hot Beverages End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Hot Beverages Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Hot Beverages Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Hot Beverages Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Nestlé S.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 JAB Holding Company
- 18.4 Luigi Lavazza S.p.A.
- 18.5 Celestial Seasonings
- 18.6 Harney & Sons
- 18.7 Costa Limited
- 18.8 Dilmah
- 18.9 JDB (China) Beverages Ltd.
- 18.10 Kraft Heinz Company
- 18.11 Jacobs Douwe Egberts
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

