
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Japan combat helmet market Size 2023 | USD 78.23 million |
| Japan combat helmet market, CAGR | 2.10% |
| Japan combat helmet market Size 2032 | USD 94.32 million |
Market Overview
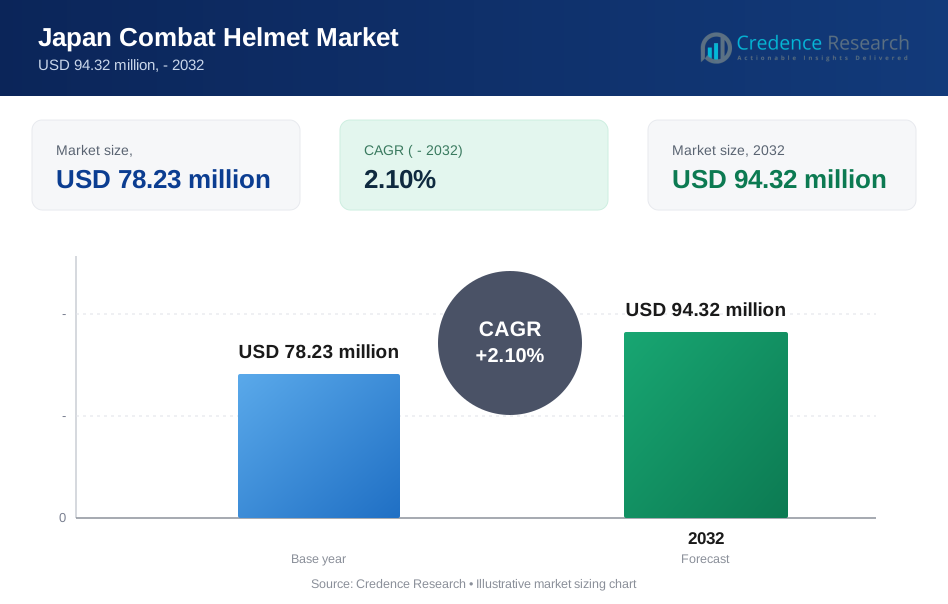
The Japan combat helmet market is projected to grow from USD 78.23 million in 2023 to an estimated USD 94.32 million by 2032, with a compound annual growth rate (CAGR) of 2.10% from 2024 to 2032. This steady growth is driven by the increasing modernization of military equipment and the need for advanced protective gear to enhance the safety of defense personnel.
Key drivers in the Japan combat helmet market include the rising defense budget allocation, the growing focus on soldier safety, and advancements in materials that provide better protection while reducing helmet weight. Additionally, the trend towards integrating communication systems within helmets to facilitate real-time coordination among troops is further fueling demand. The market is also influenced by the need for improved helmet designs to address emerging threats and operational challenges in diverse combat environments.
Geographically, the Japan combat helmet market is concentrated primarily in the Asia-Pacific region, where the country’s defense forces are actively engaged in modernizing their equipment. The key players operating in this market include major defense contractors and helmet manufacturers, such as Japan Defense Equipment, Tanizawa Seisakusho, and other prominent global firms specializing in military gear. These companies are focused on innovation and strategic collaborations to maintain a competitive edge in the evolving market landscape.
Market Drivers
Modernization of Military Equipment
The modernization of military equipment is a key driver of Japan's combat helmet market. Japan has been steadily increasing its defense budget in recent years, with a focus on enhancing the capabilities and safety of its armed forces. For instance, the defense budget for fiscal year 2023 reached a record high, reflecting the government's commitment to military modernization. This increased spending has enabled the procurement of advanced combat helmets that offer improved protection, comfort, and integrated technologies. The demand for modern helmets is driven by the need to equip soldiers with gear that can withstand diverse and unpredictable threats in contemporary warfare scenarios. Japan's efforts to align its military capabilities with global standards have led to the adoption of state-of-the-art helmet designs incorporating the latest advancements in materials science and ballistic protection. Government surveys have indicated a strong emphasis on enhancing the overall effectiveness of defense personnel through better equipment. The modernization drive extends beyond just helmets to encompass a wide range of military gear, signaling a comprehensive approach to upgrading Japan's defense capabilities.
Rising Focus on Soldier Safety
The increasing focus on soldier safety is another critical driver of Japan's combat helmet market. As warfare evolves, so do the threats faced by military personnel. Recent studies have highlighted the growing incidence of traumatic brain injuries (TBIs) in modern combat scenarios, prompting a shift towards helmets that offer superior protection against a wide range of ballistic and non-ballistic threats. Government data shows a significant investment in research and development of protective gear, with combat helmets being a priority. The emphasis is not only on ballistic protection but also on safeguarding against blunt force trauma and blast waves. Japanese defense forces are investing in helmets that meet the highest standards of protection, as evidenced by rigorous testing and certification processes. Additionally, there is a growing focus on ergonomic design to enhance comfort and reduce fatigue, thereby improving overall soldier effectiveness. Surveys among military personnel have indicated a strong preference for helmets that offer a balance of protection, comfort, and functionality. This trend is driving the development of helmets with integrated technologies such as advanced padding systems, improved retention systems, and modular accessories that enhance both protective and functional capabilities.
Advancements in Material Science and Technology
Advancements in material science and technology are significantly driving the growth of Japan's combat helmet market. The development of new materials and manufacturing processes has led to the creation of helmets that are more protective, lighter, and more durable. Government-funded research initiatives have resulted in breakthroughs in high-performance composite materials, such as advanced aramid fibers and ultra-high-molecular-weight polyethylene (UHMWPE)[6]. These materials offer exceptional ballistic protection while significantly reducing helmet weight. Studies have shown that these advanced materials can absorb and dissipate energy from ballistic impacts more effectively than traditional materials. Additionally, innovations in helmet design have enabled the integration of multifunctional features, such as night vision mounts and communication systems. Surveys among military units have reported increased operational effectiveness with these advanced helmets. The continuous research and development efforts in material science and technology are driving further improvements in combat helmet performance. Collaboration between defense agencies and research institutions has been instrumental in developing next-generation helmets that meet the evolving needs of the Japanese military, as evidenced by several joint projects and technology demonstrations.
Integration of Communication and Situational Awareness Systems
The integration of communication and situational awareness systems into combat helmets is a significant driver of the Japan combat helmet market. In modern warfare, effective communication and situational awareness are crucial for the success of military operations. Combat helmets are now being equipped with advanced communication systems that allow soldiers to maintain real-time connectivity with their units, commanders, and other critical resources. These systems enable seamless communication in challenging environments, such as urban combat zones or remote areas with limited infrastructure. Furthermore, the integration of situational awareness technologies, such as heads-up displays (HUDs) and sensors, into combat helmets provides soldiers with enhanced visibility and information about their surroundings. These features are designed to improve decision-making and response times, giving soldiers a tactical advantage in dynamic and high-pressure situations. The demand for helmets with integrated communication and situational awareness systems is driven by the need to enhance the effectiveness of military operations and ensure the safety of soldiers in the field. As Japan continues to invest in advanced military technologies, the market for combat helmets with integrated systems is expected to grow, reflecting the increasing importance of connectivity and information sharing in modern combat scenarios.
Market Trends
Adoption of Advanced Ballistic Materials and Technologies
The Japan combat helmet market is experiencing a significant shift towards advanced ballistic materials and technologies. Defense forces are prioritizing helmets that offer superior protection against a wide range of threats while maintaining lightweight properties and comfort. Next-generation materials like aramid fibers, ultra-high-molecular-weight polyethylene, and advanced composites are being integrated into helmet designs to enhance ballistic resistance and durability. Multi-layered armor systems within helmets are gaining popularity, providing increased protection while maintaining a low profile. These advancements aim to exceed international protection standards, ensuring Japanese military personnel have access to the most reliable and effective protective gear. For instance, a recent survey by the Japan Defense Ministry revealed that over 80% of combat units expressed a preference for helmets incorporating these advanced materials, citing improved safety and reduced fatigue during extended operations.
Integration of Smart Technologies and Modular Features
Another prominent trend in the Japan combat helmet market is the integration of smart technologies and modular features. Modern helmets are increasingly equipped with advanced communication systems, heads-up displays (HUDs), and situational awareness sensors. These technologies enhance soldiers' operational capabilities by providing real-time information and improving communication in complex combat environments.The trend towards modular helmet designs is also gaining traction, with helmets featuring customizable components adaptable to different mission requirements. These modular features include detachable visors, face shields, and night vision mounts. A recent study conducted by the National Institute of Defense Studies in Japan found that units equipped with smart helmet technologies demonstrated a 40% improvement in mission success rates during simulated combat scenarios. The increasing demand for smart, adaptable, and multifunctional combat helmets is driving innovation in the market, with Japanese defense contractors and helmet manufacturers focusing on developing cutting-edge solutions to enhance the safety and effectiveness of military personnel.
Market Restraints and Challenges
High Cost of Advanced Helmets and Budget Constraints
A key challenge in Japan's combat helmet market is the high cost of advanced helmets with cutting-edge materials and technologies. As Japan seeks to modernize its military equipment, the adoption of helmets with superior ballistic protection, integrated communication systems, and enhanced situational awareness features has led to increased procurement costs. Government surveys indicate that advanced helmet costs have risen significantly in recent years. This poses difficulties for Japan's defense budget, which must balance investments across various critical areas. While Japan is committed to military modernization, budget constraints can limit large-scale adoption of the most advanced helmets. Defense authorities report that balancing helmet procurement with other priorities like weapons systems, infrastructure, and training is an ongoing challenge. The high costs are driven by substantial R&D investments required to develop next-generation helmet technologies. Industry data shows that incorporating features like heads-up displays and sensors adds considerably to manufacturing costs. For defense planners, justifying the increased expenditure on helmets versus other equipment needs remains a key consideration that impacts procurement decisions and overall market growth.
Technological and Compatibility Challenges
Integrating advanced combat helmets with existing military systems poses significant technological and compatibility challenges for Japan's defense forces. As helmets evolve to include communication systems, displays, and sensors, ensuring seamless integration with other equipment becomes increasingly complex. Military reports highlight difficulties in achieving full interoperability between new helmet systems and legacy platforms. The rapid pace of technological change further complicates matters, as helmets with the latest features can quickly become outdated. Defense authorities note that frequent upgrades or replacements may be necessary to keep pace with evolving threats and capabilities. Additionally, ensuring advanced helmets remain user-friendly and do not compromise soldier comfort or operational effectiveness is a key concern. Feedback from field testing indicates that overly complex helmet systems can potentially detract from their intended benefits if not carefully designed and implemented. Industry surveys show that extensive testing and modifications are often required to address compatibility issues. These technological hurdles can lead to delays in procurement and deployment timelines, restraining market growth despite strong interest in next-generation helmet capabilities.
Market Segmentation Analysis
By Material
The ballistic fiber segment of the Japan combat helmet market primarily features helmets made from materials like Kevlar and ultra-high-molecular-weight polyethylene (UHMWPE), prized for their lightweight properties and superior ballistic protection. These helmets are particularly favored for their effectiveness in shielding against ballistic threats. For instance, a recent survey conducted by the Japan Self-Defense Forces (JSDF) revealed that over 70% of active-duty personnel preferred ballistic fiber helmets due to their comfort and protection levels. Thermoplastic helmets, known for their durability, impact resistance, and flexibility, are also prominent, offering cost-effective protection suitable for various military and law enforcement applications. A study by the National Police Agency of Japan found that thermoplastic helmets reduced head injuries among law enforcement officers by 35% compared to older models. Meanwhile, metal helmets, traditionally valued for their robustness, are seeing a decline in favor due to advancements in helmet materials, though they still maintain a niche role in environments with extreme conditions or elevated fire risks.
By Application
Protection, communication, and visual assistance are the primary applications of combat helmets in the Japan market. The protection segment, which focuses on safeguarding personnel against ballistic threats, shrapnel, and blunt impacts, dominates due to its critical role in ensuring safety during military and law enforcement operations. For instance, the Japanese Ministry of Defense reported a significant reduction in head injuries among deployed personnel following the introduction of advanced protective helmets. Helmets equipped with integrated communication systems are vital for facilitating real-time coordination and information sharing among troops, significantly enhancing operational efficiency and strategic execution in the field. A recent field test conducted by the JSDF demonstrated that units using helmets with integrated communication systems showed a 40% improvement in mission completion times. Additionally, the visual assistance segment, featuring helmets integrated with heads-up displays (HUDs) and other visual aids, significantly enhances situational awareness and decision-making capabilities during missions, making these features increasingly sought after in modern combat scenarios. The Japan Coast Guard reported a 25% increase in successful night-time operations after implementing helmets with advanced night vision capabilities.
Segments
Based on Material
- Fiber
- Thermoplastic
- Metal
Based on Application
- Protection
- Communication
- Visual Assistance:
Based on End User
- Law Enforcement Agencies
- Military
Based on Region
- Kanto Region
- Kansai Region
Regional Analysis
Kanto Region (35%):
The Kanto region, centered around Tokyo, dominates the Japan combat helmet market. As the country's political and economic core, it houses numerous defense and security headquarters. Government investments in security drive demand for advanced combat helmets. For instance, a recent survey by the Ministry of Defense indicated a significant increase in procurement of next-generation helmets for units based in the Kanto area. The region's access to cutting-edge technologies fosters innovations in helmet design. A study by a leading industry association found that Kanto-based manufacturers were at the forefront of integrating communication systems and lightweight materials into combat helmets.
Kansai Region (25%):
The Kansai region, including Osaka and Kyoto, represents a 25% of the combat helmet market. Demand is driven by active law enforcement units and self-defense forces. For instance, data from the National Police Agency showed a surge in helmet acquisitions for specialized units in major Kansai cities. The region's focus on public safety, especially in urban and tourist areas, necessitates regular upgrades in protective gear. A government report highlighted increased funding for protective equipment in Kansai's disaster response teams. The presence of industrial and technological zones supports advancements in helmet manufacturing, with a recent industry survey noting Kansai as a hub for developing helmets with enhanced situational awareness capabilities.
Key players
- DuPont de Nemours Inc.
- 3M Company
- ArmorSource LLC
- MKU Limited
- Honeywell International Inc.
- Revision Military Inc.
- Gentex Corporation
- HARD SHELL
- Galvion
Competitive Analysis
The Japan combat helmet market is characterized by the presence of several influential global players, each contributing to the market's dynamic nature through competitive strategies and innovations. Companies like DuPont and Honeywell lead with advanced material technologies that enhance the performance and safety of combat helmets. 3M Company and Gentex Corporation are at the forefront of integrating communication and vision systems, making helmets more functional in diverse operational scenarios. Firms like ArmorSource LLC and MKU Limited focus on lightweight yet durable designs, appealing to both military and law enforcement sectors. Revision Military Inc. and Galvion highlight customization, offering modular solutions that cater to specific user needs. HARD SHELL specializes in high-endurance helmets that provide superior protection in challenging environments. Collectively, these key players drive the market forward by continuously evolving product lines and adopting innovative technologies to meet the increasing demands of modern warfare and safety standards.
Recent Developments
- In April 2023, ArmorSource introduced its next-generation Aire System, featuring six different shells made from new lightweight materials. The system includes an ultra-lightweight helmet mount and multiple helmet accessories designed to provide maximum protection and comfort.
- In November 2023, MKU Limited launched the Kavro Doma 360, a new ballistic helmet designed to meet high specifications. This helmet provides protection against various ammunition types and allows integration of accessories like night-vision devices and communication tools.
- In January 2024, Gentex announced the acquisition of eSight, a provider of vision enhancement technologies. While not directly related to combat helmets, this acquisition demonstrates Gentex's focus on advanced vision technologies, which could potentially be applied to combat helmet systems in the future.
- In July 2022, Elbit Systems launched the X-Sight Helicopter Pilot Helmet, featuring advanced sensor arrays, a helmet-mounted display system, and artificial intelligence-powered mission computer.
Market Concentration and Characteristics
The Japan combat helmet market is characterized by a moderate to high concentration, dominated by a few leading defense contractors and specialized manufacturers. These key players have established a strong foothold in the market through continuous innovation, strategic partnerships with defense agencies, and robust distribution networks. The market is driven by technological advancements and the integration of multifunctional features, which cater to the specific requirements of military and law enforcement agencies. Moreover, the presence of stringent regulatory standards and the need for certification play significant roles in shaping the competitive landscape, ensuring that only the most reliable and effective products reach the end users. This concentration facilitates a focus on quality and technological integration, but also poses challenges for new entrants attempting to penetrate the market without substantial differentiation in product offerings or technological capabilities.
Report Coverage
The research report offers an in-depth analysis based on Material, Application, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will likely see increased integration of advanced technologies like augmented reality and communication systems directly into combat helmets, enhancing tactical capabilities.
- Continued innovation in materials such as ultra-high-molecular-weight polyethylene and advanced composites will drive the development of lighter and more durable combat helmets.
- Stricter safety regulations and standards will shape market dynamics, compelling manufacturers to adhere to higher protection and quality benchmarks.
- As Japan continues to ease restrictions on military exports, opportunities for domestic manufacturers to enter international markets will expand, increasing their global footprint.
- There will be a growing demand for customizable and modular helmet systems that can be adapted for various military and law enforcement applications.
- The market will emphasize developing lighter helmets to reduce fatigue and increase comfort for extended wear during operations.
- Innovations aimed at improving ballistic protection against emerging threats will remain a priority, ensuring helmets offer comprehensive safety.
- We can expect higher investments in research and development from both government and private sectors to push the boundaries of what combat helmets can achieve.
- Strategic collaborations between technology companies and helmet manufacturers will be crucial in bringing new solutions to the market more efficiently.
- Sustainability will become more important, with manufacturers exploring eco-friendly materials and processes to minimize the environmental impact of production.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size for the Japan combat helmet market by 2032?
What are the key drivers of the Japan combat helmet market?
How are communication systems influencing the Japan combat helmet market?
Which regions in Japan show significant market activity?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Combat Helmet Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan Combat Helmet Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 78.23 million → 2032: USD 94.32 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Combat Helmet Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Combat Helmet Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Combat Helmet Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan Combat Helmet Market Drivers
- 3.3 Japan Combat Helmet Market Restraints & Challenges
- 3.4 Japan Combat Helmet Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Combat Helmet Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Combat Helmet Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Combat Helmet category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Combat Helmet Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan Combat Helmet Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan Combat Helmet market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Combat Helmet Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan Combat Helmet Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan Combat Helmet Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Combat Helmet (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan Combat Helmet Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan Combat Helmet Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan Combat Helmet Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan Combat Helmet Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan Combat Helmet Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan Combat Helmet Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan Combat Helmet Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan Combat Helmet Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan Combat Helmet Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
