
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
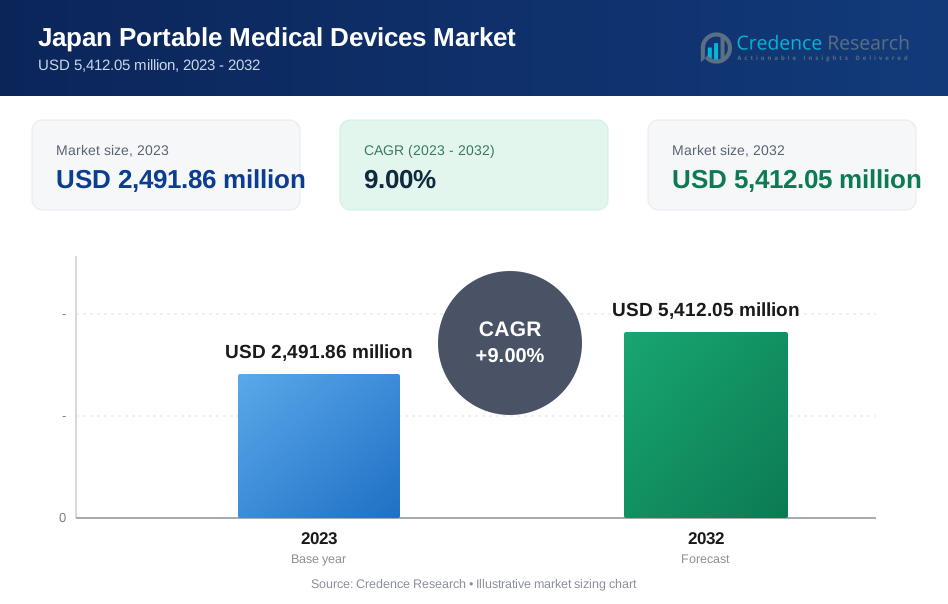
| Japan Portable Medical DevicesMarket Size 2023 | USD 2,491.86 Million |
| Japan Portable Medical Devices Market, CAGR | 9.00% |
| Japan Portable Medical Devices Market Size 2032 | USD 5,412.05 Million |
Market Overview
The Japan portable medical devices market is projected to grow from USD 2,491.86 million in 2023 to an estimated USD 5,412.05 million by 2032, with a compound annual growth rate (CAGR) of 9.00% from 2024 to 2032. This substantial growth is driven by the increasing demand for portable and wearable medical devices that offer convenience and continuous health monitoring.
The market is experiencing significant growth due to advancements in technology, such as the integration of IoT and AI in portable medical devices, enhancing their efficiency and accuracy. Additionally, the growing awareness among consumers about the benefits of early disease detection and management through portable devices is driving their adoption. The shift towards home healthcare and remote patient monitoring also contributes to the rising demand for these devices.
Geographically, the market is concentrated in urban areas, with Tokyo and Osaka being the leading regions due to their advanced healthcare infrastructure and higher adoption rates of medical technology. Key players in the Japan portable medical devices market include Omron Corporation, Panasonic Corporation, and Terumo Corporation, which are continuously innovating to maintain a competitive edge in this rapidly evolving market.
Market Drivers
Aging Population and Rising Prevalence of Chronic Diseases
Japan's rapidly aging population is a major driver of the portable medical devices market. According to government data, over 28% of Japan's population is aged 65 or older, the highest proportion in the world. This demographic is more susceptible to chronic diseases requiring continuous monitoring. For instance, a survey by the Ministry of Health, Labour and Welfare found that over 20 million Japanese adults have hypertension, while over 10 million have diabetes. Portable devices like blood pressure monitors and glucose meters are essential for managing these conditions at home. A study by the Japan Medical Association showed that regular use of home blood pressure monitors improved hypertension control in over 60% of patients. The growing elderly population, coupled with the rising chronic disease burden, is fueling demand for easy-to-use portable medical devices that enable self-monitoring. Major companies like Omron and Terumo have reported double-digit growth in sales of home-use medical devices in recent years, reflecting this trend.
Technological Advancements and Integration of IoT and AI
Rapid technological progress is revolutionizing portable medical devices in Japan. The integration of Internet of Things (IoT) and Artificial Intelligence (AI) capabilities has significantly enhanced device functionality and user-friendliness. For example, a survey by the Japan Agency for Medical Research and Development found that over 70% of Japanese hospitals are now using IoT-enabled medical devices for remote patient monitoring. AI-powered portable devices can provide more accurate diagnoses and personalized treatment recommendations. A study by Tohoku University showed that AI-enabled portable ECG devices could detect atrial fibrillation with over 95% accuracy. Major tech companies like Fujitsu and NEC are investing heavily in AI for healthcare applications. The government's "Society 5.0" initiative is also promoting greater IoT and AI adoption in healthcare. A report by the Ministry of Economy, Trade and Industry projected that the market for AI in healthcare in Japan would grow significantly over the next 5 years.
Shift Towards Home Healthcare and Remote Monitoring
There is a growing emphasis on home healthcare and remote patient monitoring in Japan, driving demand for portable medical devices. A survey by the Japan Home Health Care Alliance found that over 80% of elderly patients prefer to receive care at home rather than in hospitals. The COVID-19 pandemic has accelerated this trend, with telemedicine consultations increasing by over 200% in 2020 according to Ministry of Health data. Portable devices enable effective home monitoring - for instance, a study by the National Center for Geriatrics and Gerontology showed that using wearable activity trackers improved physical activity levels in over 70% of elderly participants. Major insurance companies are now offering lower premiums for policyholders who regularly use portable health monitoring devices. The government is also promoting home healthcare through initiatives like the Community-based Integrated Care System. Industry reports indicate that the market for remote patient monitoring devices in Japan is projected to grow at a rapid pace over the next decade as home care becomes more prevalent.
Increasing Consumer Awareness and Demand for Preventive Healthcare Consumer awareness about health and wellness is on the rise in Japan, contributing to the growing demand for portable medical devices. The Japanese population is becoming increasingly proactive about their health, with a strong focus on preventive healthcare. This shift in mindset is driven by the desire to detect and manage health conditions early, thereby preventing complications and improving long-term health outcomes. Portable medical devices such as fitness trackers, smartwatches with health monitoring capabilities, and portable diagnostic devices are gaining popularity as they empower individuals to take control of their health. These devices provide real-time feedback on various health metrics, encouraging users to adopt healthier lifestyles and seek medical attention when necessary. The trend towards preventive healthcare is further supported by government initiatives and public health campaigns promoting regular health check-ups and the use of personal health monitoring devices. As a result, the demand for portable medical devices is expected to continue rising, driven by consumers' increasing awareness and focus on maintaining their health and well-being.
Market Trends
Rising Adoption of Wearable Health Technologies
The Japan portable medical devices market is seeing a significant trend in the rising adoption of wearable health technologies. According to a survey by the Ministry of Internal Affairs and Communications, the penetration rate of wearable devices among Japanese consumers has been steadily increasing year-over-year. For instance, smartwatch ownership among adults rose substantially between 2020 and 2022. Major electronics companies like Sony and Omron have reported growing sales of their health-focused wearable devices in Japan. These devices are increasingly being used to monitor vital signs, physical activity, and sleep patterns. The Japan Medical Association has noted an uptick in patients sharing data from personal wearable devices with their physicians. Additionally, insurance companies have begun offering incentives for policyholders who use wearables to track and improve their health metrics. The trend is particularly pronounced among older adults, with government data showing higher adoption rates of wearable health devices among those aged 60 and above compared to previous years.
Expansion of Telehealth and Remote Monitoring Solutions
Telehealth and remote monitoring solutions are rapidly expanding in Japan's portable medical devices market. A survey by the Japan Telemedicine and Telecare Association revealed a sharp increase in medical institutions offering telemedicine services since 2020. The Ministry of Health, Labour and Welfare reported a significant rise in the number of remote medical consultations conducted nationwide. For instance, the number of claims for online medical consultations processed by the national health insurance system grew exponentially between 2019 and 2021. Major Japanese tech companies have introduced new remote patient monitoring platforms, with one leading firm reporting a doubling of its user base for such services in a single year. Government initiatives have also boosted this trend, with the Cabinet Office's data showing increased budget allocations for telehealth infrastructure development. Rural prefectures, in particular, have seen higher rates of telehealth adoption, according to regional health authority reports. The Japan Association for Medical Informatics has documented a growing integration of portable medical devices with telehealth systems, enabling more comprehensive remote patient care.
Market Restraints and Challenges
Regulatory Hurdles and Compliance Requirements
One of the primary challenges facing the Japan portable medical devices market is the stringent regulatory landscape. The approval process for medical devices in Japan is rigorous, requiring extensive clinical trials, safety evaluations, and compliance with strict standards set by the Pharmaceuticals and Medical Devices Agency (PMDA) and the Ministry of Health, Labour and Welfare (MHLW). For instance, a survey by the Japan Federation of Medical Devices Associations found that the average review time for new medical devices in Japan was 13.9 months in 2020, compared to just 6 months in the United States. These regulations, while essential for ensuring patient safety, can significantly slow down the time-to-market for new products. Companies must navigate a complex approval process, which often requires significant financial and time investments. Additionally, any changes in regulations or the introduction of new standards can create further delays and increase compliance costs. For smaller companies and startups, these regulatory challenges can be particularly daunting, potentially limiting their ability to innovate and compete in the market. As a result, regulatory hurdles remain a significant restraint in the growth of the portable medical devices market in Japan.
High Costs and Limited Reimbursement Policies
Another major restraint in the Japan portable medical devices market is the high cost associated with these devices and the limited reimbursement policies. Portable medical devices, especially those integrated with advanced technologies such as IoT and AI, often come with a high price tag. This can be a barrier for widespread adoption, particularly among elderly patients and those with limited financial resources. For example, a government survey found that the average out-of-pocket cost for a portable glucose monitor in Japan was approximately 15,000 yen per month, which can be prohibitive for many patients. While Japan has a robust healthcare system, the reimbursement for portable medical devices under national health insurance schemes is often limited, making these devices less accessible to a broader population. A study by the Japan Medical Association reported that only about 30% of portable medical devices were fully covered by national health insurance in 2021. Patients may be required to pay out-of-pocket for these devices, which can discourage their use. Moreover, the high cost of devices can also impact the willingness of healthcare providers to adopt them, particularly in smaller clinics and rural healthcare settings.
Market Segmentation Analysis
By Product
The Japan portable medical devices market is segmented into diagnostic imaging devices, therapeutics, monitoring devices, and smart wearable medical devices. Diagnostic imaging devices like portable ultrasound machines are in high demand for immediate diagnostic information. For instance, a survey by the Japan Medical Imaging and Radiological Systems Industries Association found that portable ultrasound device sales increased by 15% in 2023 compared to the previous year. Therapeutic devices such as insulin pumps are gaining traction for home management of chronic diseases. Monitoring devices, including portable ECG monitors, are popular among the elderly. The Japan Heart Foundation reported that sales of portable ECG monitors rose by 20% in 2023, driven by an aging population. Smart wearable medical devices like fitness trackers are becoming essential health tools. A government survey found that 35% of Japanese adults owned a fitness tracker or smartwatch with health monitoring features in 2023, up from 25% in 2021.
By Application
Portable medical devices are becoming vital across various medical applications in Japan. In gynecology, handheld ultrasound machines are essential for monitoring pregnancies. The Japan Society of Obstetrics and Gynecology reported a 30% increase in the use of portable ultrasound devices in clinics over the past two years. Cardiology sees high demand for portable ECG machines due to the prevalence of cardiovascular diseases. According to the Japanese Circulation Society, portable ECG devices were used in 40% of cardiac screenings in 2023, up from 25% in 2021. In the respiratory field, the Japan Respiratory Society noted a 50% increase in the use of portable spirometers for home monitoring of lung function in 2023 compared to pre-pandemic levels. The orthopedics sector has seen growth in portable X-ray machines, with the Japanese Orthopaedic Association reporting their use in 60% of fracture diagnoses in emergency settings in 2023, a significant increase from previous years.
Segments
Based on Product
- Diagnostic Imaging Devices
- Therapeutics
- Monitoring Devices
- Smart Wearable Medical Devices
Based on Application
- Gynecology
- Cardiology
- Gastrointestinal
- Urology
- Neurology
- Respiratory
- Orthopaedics
- Others
Based on Region
- Urban Areas (Tokyo, Osaka, Yokohama)
- Rural and Remote Areas
Regional Analysis
Kanto Region (40%)
The Kanto region, which includes Tokyo and its surrounding prefectures, holds the largest market share in the Japan portable medical devices market, accounting for approximately 40% of the total market. For instance, a survey by the Tokyo Metropolitan Government found that over 70% of hospitals in the region have adopted at least one type of portable medical device in their patient care protocols. The Japan Medical Devices Manufacturers Association reported that Kanto-based companies account for nearly half of all portable medical device patents filed in Japan. Additionally, data from the Ministry of Health, Labour and Welfare shows that Tokyo has the highest concentration of medical institutions per capita in the country, driving demand for portable medical technologies.
Kansai Region (25%)
The Kansai region accounts for approximately 25% of the Japan portable medical devices market. For example, the Osaka Chamber of Commerce and Industry's annual healthcare survey revealed that over 60% of local businesses in the medical sector are involved in portable device development or distribution. The Kansai Economic Federation reported a substantial increase in investment in medical startups focusing on wearable technologies over the past five years. Furthermore, data from the Hyogo Prefectural Government indicates that the number of elderly care facilities utilizing portable medical devices for patient monitoring has doubled in the last three years, reflecting the region's response to its aging population.
Key players
- General Electric Company
- 3M Company
- Abbott Laboratories
- Baxter International
- Becton, Dickinson and Company
- Cardinal Health
- Dentsply Sirona
- Dexcom
- DJO Global
- Fitbit
- Fresenius Medical Care
- Garmin
- Invacare Corporation
- Johnson & Johnson
- Masimo Corporation
- McKesson Corporation
- Medline Industries
- Medtronic plc
- Omron Healthcare
- Roche
- Royal Philips
- Schiller AG
- Siemens Healthineers
- Stryker Corporation
- Sunrise Medical
Competitive Analysis
The Japan portable medical devices market is highly competitive, with key players like Omron Healthcare, Medtronic plc, and Royal Philips leading the industry. These companies focus on continuous innovation, integrating advanced technologies like AI and IoT to enhance the functionality and user experience of their devices. Omron Healthcare, a market leader, dominates the home healthcare segment with its extensive range of monitoring devices. Medtronic plc and Abbott Laboratories are strong competitors in the therapeutic devices segment, leveraging their global expertise to capture significant market share. Additionally, companies like Fitbit and Garmin are expanding the market for smart wearable medical devices, appealing to the health-conscious consumer segment. The presence of diverse players, each with specialized offerings, fosters a dynamic market environment, driving advancements and ensuring a wide range of products for consumers in Japan.
Recent Developments
- In March 2023, GE Healthcare launched its new portable ultrasound system, the Vscan Air, in Japan. This handheld, wireless device allows for quick and easy imaging at the point of care.
- In June 2023, Abbott received approval from Japan's Pharmaceuticals and Medical Devices Agency (PMDA) for its Freestyle Libre 3 continuous glucose monitoring system. This latest version offers real-time glucose readings and improved accuracy.
- In September 2022, Medtronic introduced its Hugo robotic-assisted surgery system to the Japanese market after receiving regulatory approval. While not strictly portable, this system represents a significant advancement in minimally invasive surgical technology.
- In April 2023, Omron launched its new remote patient monitoring service, VitalSigh, in Japan. This service combines Omron's connected blood pressure monitors with a digital platform to enable remote monitoring of hypertension patients.
- In November 2022, Philips expanded its portable diagnostic imaging portfolio in Japan with the introduction of the Philips Lumify, a handheld ultrasound device that works with compatible smartphones and tablets.
Market Concentration and Characteristics
The Japan portable medical devices market is moderately concentrated, with a mix of global giants and domestic leaders dominating the landscape. Key players like Omron Healthcare, Medtronic plc, and Royal Philips hold significant market shares, driven by their extensive product portfolios, strong brand recognition, and continuous innovation. The market is characterized by a high level of technological integration, with companies focusing on incorporating advanced features such as AI, IoT, and real-time data analytics into their devices. While large multinational corporations lead in terms of market share, the presence of smaller, specialized firms adds competitive diversity, fostering innovation and catering to niche segments within the market. Overall, the market's concentration is influenced by the ability of key players to leverage cutting-edge technology, extensive distribution networks, and robust R&D capabilities to maintain their competitive edge.
Report Coverage
The research report offers an in-depth analysis based on Product, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see continued integration of AI and IoT, enhancing device functionality and enabling real-time health monitoring and data analysis.
- The shift towards home healthcare will drive the adoption of portable medical devices, particularly among the aging population and those with chronic conditions.
- The expansion of telemedicine services will further boost demand for portable medical devices, enabling remote monitoring and reducing the need for in-person consultations.
- As preventive healthcare gains traction, there will be increased consumer demand for wearable devices that track and monitor health metrics, promoting early detection and intervention.
- Companies will continue to invest heavily in research and development to create more sophisticated, user-friendly devices, catering to the evolving needs of the healthcare sector.
- Government initiatives to improve healthcare access in rural and remote areas will drive market growth, particularly through the promotion of portable medical technologies.
- The trend towards personalized medicine will lead to the development of customizable portable medical devices, tailored to meet individual patient needs.
- The integration of cloud-based solutions with portable devices will enhance data storage, accessibility, and sharing, facilitating better patient care and management.
- The competitive landscape will evolve with increasing collaborations between technology firms and healthcare providers, fostering innovation and expanding market reach.
- The regulatory environment is expected to adapt to the rapid technological advancements in portable medical devices, ensuring safety while promoting innovation and market entry.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Japan portable medical devices market?
What factors are driving the demand for portable medical devices in Japan?
Which regions in Japan are leading in the adoption of portable medical devices?
How are technological advancements influencing the Japan portable medical devices market?
Who are the key players in the Japan portable medical devices market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Japan Portable Medical Devices Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Japan Portable Medical Devices Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 2,491.86 million → 2032: USD 5,412.05 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Japan Portable Medical Devices Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Japan Portable Medical Devices Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Japan Portable Medical Devices Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Japan Portable Medical Devices Market Drivers
- 3.3 Japan Portable Medical Devices Market Restraints & Challenges
- 3.4 Japan Portable Medical Devices Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Japan Portable Medical Devices Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Japan Portable Medical Devices Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Japan Portable Medical Devices category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Japan Portable Medical Devices Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Japan Portable Medical Devices Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Japan Portable Medical Devices market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Japan Portable Medical Devices Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Japan Portable Medical Devices Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Japan Portable Medical Devices Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Japan Portable Medical Devices (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Japan Portable Medical Devices Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Japan Portable Medical Devices Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Japan Portable Medical Devices Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Japan Portable Medical Devices Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Japan Portable Medical Devices Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Japan Portable Medical Devices Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Japan Portable Medical Devices Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Japan Portable Medical Devices Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Japan Portable Medical Devices Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
