
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Kaolin Market Size 2024 | USD 4,409.5 million |
| Kaolin Market, CAGR | 4.20% |
| Kaolin Market Size 2032 | USD 6,128.17 million |
Market Overview
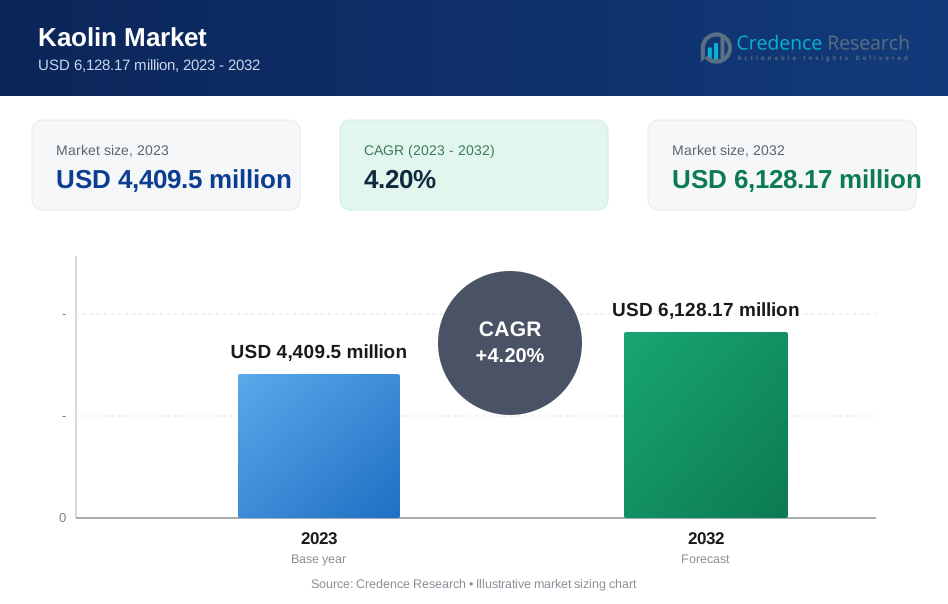
The Global Kaolin Market is projected to grow from USD 4,409.5 million in 2023 to an estimated USD 6,128.17 million by 2032, with a compound annual growth rate (CAGR) of 4.20% from 2024 to 2032. This growth reflects the increasing demand for kaolin across various industries, including paper, ceramics, paints and coatings, and rubber.
Market drivers for kaolin include its extensive application in paper and ceramics, where it enhances quality and functionality. The construction industry's expansion and the rising demand for premium paper products have also fueled kaolin consumption. Emerging trends indicate a growing preference for refined kaolin products with specialized properties, such as increased brightness and enhanced particle size. Additionally, technological advancements in extraction and processing methods have further supported market growth by improving product quality and lowering production costs.
Geographically, Asia-Pacific dominates the kaolin market, with significant contributions from countries like China and India, driven by rapid industrialization and expanding end-use sectors. North America and Europe also hold substantial market shares, with a strong presence of established players and advanced manufacturing capabilities. Key players, such as Imerys S.A. (France), Ashapura Group (India), and KaMin LLC (US), play pivotal roles in shaping market dynamics through ongoing innovation, strategic partnerships, and product expansion efforts to cater to a diverse range of applications globally.
Market Drivers
Increasing Demand from the Paper Industry
The paper industry represents one of the largest sectors driving demand for kaolin. As a primary raw material in paper production, kaolin is used to improve various properties such as opacity, smoothness, and brightness of paper. Its role as a filler and coating material enables manufacturers to produce high-quality paper products that meet the demands of both industrial and consumer applications. For instance, kaolin is utilized as a coating material that not only enhances the visual appeal of printed materials but also improves ink receptivity, resulting in sharper images and better color reproduction. Additionally, the rising demand for packaging materials, fueled by the growth of e-commerce and consumer goods, has further accelerated the need for kaolin in paper production. Emerging economies in Asia-Pacific, Latin America, and the Middle East have witnessed increased consumption of paper due to urbanization and rising literacy rates, thus boosting kaolin demand. Moreover, as the trend toward environmentally sustainable packaging continues to grow, kaolin’s role as a natural, eco-friendly filler enhances its attractiveness over synthetic alternatives.
Growth of the Construction and Ceramic Industries
Kaolin's importance in the construction and ceramic industries continues to be a key market driver. In the construction sector, kaolin is used to manufacture cement, tiles, and other building materials that are critical for infrastructure projects. For example, its role as a binding agent improves the durability and aesthetic qualities of ceramic products. With rapid urbanization and increasing construction activity in developing regions, the demand for kaolin-based products has experienced a significant uptick. In particular, countries in the Asia-Pacific region are experiencing substantial growth in their construction and ceramics industries due to rising middle-class populations and increased investment in infrastructure. Furthermore, kaolin is essential in the ceramics industry, where it is utilized in the production of porcelain, sanitary ware, and tiles. Its properties allow it to act as a binding agent that enhances texture and color stability.
Rising Demand for Paints and Coatings
The paints and coatings industry heavily relies on kaolin for its pigment properties. Kaolin enhances brightness, whiteness, and opacity while also improving durability and adhesion. With growth in the automotive, construction, and manufacturing sectors, there has been an increased demand for high-quality paints and coatings, contributing to rising consumption of kaolin. For instance, its use in paints improves their durability and adhesion properties. Additionally, kaolin is seen as a safer, more environmentally friendly alternative to other mineral additives due to its low toxicity and minimal environmental impact. In regions like North America and Europe, the push for sustainable materials in the coatings industry is further boosting the use of kaolin. As manufacturers seek to improve their product formulations with renewable components, specialty kaolin products that offer enhanced properties-such as improved color stability and weather resistance-are gaining traction particularly in premium paint applications.
Technological Advancements in Kaolin Processing and Refinement
Technological advancements have revolutionized kaolin processing, enhancing product quality and widening its application scope. New processing techniques, such as flotation, magnetic separation, and advanced calcination, have enabled manufacturers to produce high-purity kaolin with specific particle sizes and properties tailored to various end-use industries. These advancements allow for more efficient extraction processes and reduce impurities, which in turn enhances the performance of kaolin-based products. Additionally, the rise of nanokaolin – kaolin processed to nanoscale dimensions – has introduced new possibilities in applications such as nanocomposites, where it offers improved mechanical properties and increased resistance to thermal stress. These technological advancements are particularly valuable in sectors like electronics, where refined kaolin can improve product performance and durability. Companies investing in R&D and innovative technologies are better positioned to cater to niche markets, providing a competitive edge that further drives growth within the kaolin market.
Market Trends
Growing Focus on Sustainable and Eco-Friendly Products
The global shift toward sustainable practices has significantly impacted the kaolin market, with a notable emphasis on eco-friendly products and production processes. As industries increasingly prioritize environmental responsibility, kaolin has become a preferred choice over synthetic additives and fillers. This is particularly evident in the paper, paints, and plastics industries, where kaolin is valued for its natural, non-toxic properties. For instance, many manufacturers are now prioritizing the development of biodegradable kaolin composites that minimize environmental impact. This shift is evident in the paper and packaging industries, where kaolin is sought after for its natural attributes compared to synthetic alternatives, which often involve harmful chemicals. Manufacturers are investing in research and development to create kaolin products with reduced environmental impact, including water-based formulations. Furthermore, companies are refining kaolin processing methods to minimize waste and conserve energy. Techniques such as low-emission calcination processes are being adopted to lower the carbon footprint associated with kaolin production. This aligns with the broader industry trend toward sustainability, as firms respond to stricter environmental regulations and consumer demand for greener products. The emphasis on sustainable kaolin products is expected to drive market growth as industries continue to seek eco-friendly solutions.
Increased Demand for High-Purity and Specialty Kaolin Grades
Another prominent trend in the kaolin market is the rising demand for high-purity and specialty grades of kaolin. High-purity kaolin, often produced through advanced refinement techniques, offers enhanced qualities such as increased brightness, particle size uniformity, and greater chemical stability. These refined kaolin products are essential in high-performance applications across industries like electronics, pharmaceuticals, and cosmetics, where they improve product efficacy and appearance. For example, calcined kaolin is widely utilized in paints and coatings due to its superior opacity and reinforcement properties. Specialty kaolin grades, such as calcined kaolin and metakaolin, are gaining popularity due to their improved performance characteristics. Metakaolin, in particular, is recognized in construction for enhancing concrete strength and durability. This trend reflects technological advancements that enable producers to tailor kaolin properties to meet specific industry requirements, ultimately expanding the mineral’s application scope and boosting market demand for specialized kaolin products.
Market Restraints and Challenges
High Production Costs and Resource Limitations
One significant challenge in the kaolin market is the high cost associated with mining, processing, and refining kaolin to meet specific quality standards. Extracting high-purity kaolin requires advanced technology and energy-intensive processes such as calcination and magnetic separation, which increase overall production expenses. Additionally, kaolin reserves are often located in remote areas, necessitating substantial investments in infrastructure and transportation to bring the raw material to processing facilities and end markets. These factors contribute to higher operating costs, impacting profit margins and limiting the affordability of kaolin products for certain applications. Furthermore, the availability of high-quality kaolin deposits is increasingly constrained, leading to resource scarcity in some regions. This limitation on high-grade kaolin resources may hinder market growth, particularly as global demand continues to rise, putting pressure on existing reserves and increasing the likelihood of price volatility.
Intense Competition from Substitutes and Alternative Materials
The kaolin market faces significant competition from alternative materials, which can substitute kaolin in various applications. For instance, in the paper industry, calcium carbonate is often used as a filler and coating agent due to its similar properties and generally lower cost. In construction and ceramics, alternatives such as bentonite and feldspar are sometimes preferred based on specific application requirements and regional availability. Moreover, synthetic materials are also being developed to mimic or enhance kaolin’s properties, particularly in sectors such as paints and coatings, where manufacturers seek optimized performance characteristics. This competition from substitutes poses a challenge to kaolin market players, as they must continually innovate to demonstrate the unique advantages of kaolin over alternatives. Additionally, fluctuations in substitute material costs and regulatory changes favoring more accessible or readily available materials may impact the overall demand for kaolin, presenting a restraint on market expansion.
Market Segmentation Analysis
By Process
The kaolin market, segmented by process, is led by water-washed kaolin, which is highly valued for its purity and brightness, making it ideal for ceramics, paper, paints, coatings, and rubber. Its straightforward and cost-effective production process is especially popular in regions with abundant kaolin deposits. Airfloat kaolin, produced through dry milling, is widely used as a filler in adhesives, sealants, rubber, and plastics due to its cost efficiency, though its lower purity may restrict its applications. Calcined kaolin, subjected to thermal treatment, is sought after for its high brightness, opacity, and reinforcement capabilities, making it essential in paints, coatings, and rubber. Delaminated kaolin, produced by separating kaolin into thin platelets, enhances smoothness and coverage in high-performance coatings and paper products, with demand growing in developed markets. Surface-modified kaolin, treated for improved compatibility with specific materials, finds use in specialized applications like plastics and adhesives, while unprocessed kaolin is typically used in products not requiring high purity, such as cement. As specialized applications expand, surface-modified kaolin is expected to see steady growth.
By End Use Industry
Kaolin serves diverse roles across several end-use industries, significantly impacting the ceramics and sanitaryware segment, where it provides essential plasticity and durability, driven by urbanization and the global demand for high-quality ceramics. In fiberglass production, kaolin enhances thermal stability, making it valuable in construction and automotive applications, particularly in North America and Asia-Pacific. The paints and coatings segment benefits from kaolin's ability to improve opacity, brightness, and durability, meeting the demand for eco-friendly materials in North America and Europe. In rubber, kaolin acts as a reinforcing filler, supporting the automotive and construction sectors' need for high-performance products. Kaolin also enhances viscosity and workability in adhesives and sealants, spurred by construction and packaging growth, especially in developing regions. The plastics segment uses kaolin to boost mechanical properties, heat resistance, and cost efficiency, with demand rising in packaging, automotive, and consumer goods. Additionally, smaller markets like agriculture, pharmaceuticals, and cosmetics leverage kaolin for its absorbent, non-toxic qualities, contributing to the market's diversity and specialized applications.
Segments
Based on Process
- Waterwashed
- Airfloat
- Calcined
- Delaminated
- Surfacemodified & Unprocessed
Based on the Enduse industry
- Ceramics & Sanitarywares
- Fiberglass
- Paints & Coatings
- Rubber
- Adhesives & Sealants
- Plastics
- Others
Based on the Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis
Asia-Pacific (39%):
Asia-Pacific holds the largest share of the global kaolin market, accounting for approximately 39% of the total market share. This region's dominance is primarily due to the rapid growth of key industries such as construction, ceramics, and paper, especially in countries like China, India, and Japan. China is a leading producer and consumer of kaolin, driven by its expansive ceramics and construction sectors. In India, rising urbanization and infrastructural developments have led to increased demand for kaolin in construction and sanitaryware. Additionally, Japan’s advanced manufacturing sector leverages high-purity kaolin in electronics and specialty ceramics. The region's competitive advantage lies in the availability of substantial kaolin deposits and lower production costs, which have attracted investment in kaolin processing and refining.
North America (25%):
North America holds around 25% of the global kaolin market share, largely due to the United States’ robust demand for kaolin in industries such as paper, paints, and coatings. The U.S. is one of the largest consumers of kaolin, utilizing it in the production of high-quality coated paper and as a filler in paints, coatings, and rubber. The region benefits from well-established processing facilities and advanced technologies that produce high-grade kaolin, catering to industries that require premium-quality materials. Furthermore, increasing environmental awareness has spurred the adoption of kaolin in eco-friendly applications, such as sustainable packaging materials and environmentally friendly paints. Canada also contributes to the region's market growth, with rising demand for kaolin in construction and ceramic applications.
Key players
- Imerys S.A. (France)
- Ashapura Group (India)
- EICL Limited (India)
- SCR-Sibelco N.V. (Belgium)
- KaMin LLC (US)
- Thiele Kaolin Company (US)
- LASSELSBERGER Group (Hungary)
- Quarzwerke GmbH (Germany)
- Sedlecký kaolin A.S. (Czech Republic)
- Minerals Inc. (Canada)
- 20 Microns Limited (India)
- Minotaur Exploration Limited (Australia)
- R. Grace & Co. (US)
Competitive Analysis
The Global Kaolin Market is characterized by strong competition among established players, each leveraging extensive portfolios, advanced processing technologies, and wide-reaching distribution networks. Imerys S.A. and SCR-Sibelco N.V. are market leaders with significant global presence and diverse kaolin products catering to multiple industries, including paper, ceramics, and construction. Companies like KaMin LLC, Thiele Kaolin Company, and W. R. Grace & Co. focus heavily on North American markets, providing high-quality, refined kaolin products for specialized applications in paints, coatings, and plastics. Meanwhile, Asian players such as Ashapura Group and 20 Microns Limited cater primarily to regional demand in construction and ceramics, capitalizing on cost-effective production and growing local markets. To maintain competitive advantage, companies invest in R&D for innovative products, sustainable processing methods, and strategic partnerships, adapting to evolving customer requirements and environmental regulations.
Recent Developments
- In September 2023, Ashapura Group launched a new range of specialty kaolin products at its processing complex in Bhuj, India. This expansion aims to cater to increasing demand in the ceramics and paints sectors, enhancing the company’s product offerings.
- In March 2023, EICL Limited introduced a new line of calcined kaolin products that focus on improving performance in coatings and plastics. This launch is part of their strategy to enhance product quality and meet evolving market demands.
- In August 2022, SCRInSibelco announced the expansion of its kaolin processing facility in Brazil. This development aims to increase production capacity and improve supply chain efficiency for its customers in the Americas.
- In September 2022, KaMin LLC completed the acquisition of BASF SE’s kaolin business, which included approximately 440 employees across North America, Europe, and Asia. This acquisition is expected to enhance KaMin's technical capabilities and market reach.
- In February 2023, LASSELSBERGER launched a new product line featuring highInpurity kaolin aimed at the ceramics industry. This initiative is designed to meet increasing quality standards and customer expectations.
- In October 2023, Quarzwerke GmbH introduced a new ecoInfriendly kaolin product designed for use in paper manufacturing, emphasizing sustainability and reduced environmental impact.
- In April 2023, Sedlecký kaolin announced an upgrade to its processing technology aimed at improving the quality of its kaolin products for the ceramics and construction industries.
- In November 2022, IInMinerals Inc. reported progress on its pilot plant project for producing highInpurity halloysite clay, which is closely related to kaolin and has applications in various industries.
- In June 2023, 20 Microns Limited launched a new grade of calcined kaolin aimed at enhancing performance in paints and coatings applications, responding to market demand for higher quality materials.
- In January 2023, Minotaur Exploration announced positive results from its exploration activities focused on highIngrade kaolin deposits, indicating potential for future production increases.
- In March 2023, W. R. Grace & Co. expanded its portfolio by launching new specialty additives that incorporate kaolin, targeting the construction and coatings markets to provide enhanced performance characteristics.
Market Concentration and Characteristics
The Global Kaolin Market is moderately concentrated, with a mix of large multinational corporations and smaller regional players competing for market share. Leading companies such as Imerys S.A., SCRInSibelco N.V., and KaMin LLC hold significant influence due to their extensive resources, advanced processing technologies, and broad product portfolios that serve diverse industries like ceramics, paper, and paints. Market characteristics include a focus on innovation, with key players investing in R&D to develop specialized and highInpurity kaolin products that meet specific industry needs. Additionally, environmental considerations and regulatory pressures have spurred a trend toward sustainable processing methods, driving demand for ecoInfriendly kaolin solutions. The market is further characterized by regional specialization, with companies in AsiaInPacific benefiting from costIneffective production and abundant resources, while those in North America and Europe prioritize highInquality and refined kaolin products to cater to premium applications.
Report Coverage
The research report offers an inIndepth analysis based on Process, Enduse industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The global kaolin market is expected to continue growing, driven by increasing demand across diverse industries, including construction, ceramics, and paper, particularly in developing regions.
- With a global shift toward ecoInfriendly materials, kaolin's natural properties make it a preferred choice for sustainable applications in packaging, coatings, and green construction.
- Ongoing innovations in kaolin processing, such as improved calcination and refining techniques, are set to enhance product quality, expand application range, and reduce production costs.
- HighInpurity and specialty kaolin grades are gaining traction in sectors like electronics and pharmaceuticals, where they offer enhanced performance characteristics and superior quality.
- AsiaInPacific is expected to maintain its position as the largest and fastestIngrowing market for kaolin, driven by rapid industrialization, urbanization, and infrastructure development in countries like China and India.
- Kaolin’s heatInresistant properties are increasingly utilized in the renewable energy sector, particularly in solar panel production, where it helps improve durability and efficiency.
- As the automotive industry prioritizes lightweight, highInstrength materials, kaolinInbased composites are anticipated to see increased use, particularly in electric vehicle manufacturing.
- Stricter environmental policies in regions like North America and Europe will likely drive demand for ecoInfriendly kaolin processing methods, encouraging sustainable production practices.
- Major players are expected to pursue mergers, acquisitions, and collaborations to expand their market presence, access new resources, and drive technological innovation in kaolin applications.
- To meet evolving industry demands, companies will continue investing in R&D to develop kaolin products with specific attributes, such as enhanced brightness, particle size, and thermal stability, thus expanding their market potential.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Demand from the Paper Industry
Kaolin is a key raw material in paper manufacturing, enhancing opacity, smoothness, and brightness. The growth of packaging and premium paper products, especially in emerging economies, is driving higher consumption of kaolin as both a filler and coating agent.
Growth of the Construction and Ceramic Industries
Kaolin is essential in the production of ceramics, sanitaryware, cement, and tiles, providing plasticity and durability. Rapid urbanization and infrastructure development, particularly in Asia-Pacific, are fueling demand for kaolin-based construction and ceramic products.
Rising Demand for Paints and Coatings
Kaolin improves brightness, opacity, and durability in paints and coatings, making it a preferred additive in the automotive, construction, and manufacturing sectors. The shift toward eco-friendly and high-performance paints is further boosting kaolin usage.
Technological Advancements in Kaolin Processing
Innovations in extraction and refinement, such as advanced calcination and particle size control, are enabling the production of high-purity and specialty kaolin grades. These advancements expand kaolin’s application scope and improve product quality, supporting market growth.
Focus on Sustainable and Eco-Friendly Products
With increasing environmental regulations and consumer preference for green materials, kaolin’s natural, non-toxic properties make it an attractive alternative to synthetic fillers. The trend toward sustainable packaging and coatings is accelerating kaolin adoption across industries.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Kaolin Market?
What are the primary industries driving demand in the Kaolin Market?
How is the Asia-Pacific region influencing the Kaolin Market?
What technological advancements are enhancing kaolin processing?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Process
- 1.2.1 Waterwashed
- 1.2.2 Airfloat
- 1.2.3 Calcined
- 1.2.4 Delaminated
- 1.2.5 Surfacemodified & Unprocessed
- 1.3 By End Use Industry
- 1.3.1 Ceramics & Sanitarywares
- 1.3.2 Fiberglass
- 1.3.3 Paints & Coatings
- 1.3.4 Rubber
- 1.3.5 Adhesives & Sealants
- 1.3.6 Plastics
- 1.3.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 4,409.5 million → 2032: USD 6,128.17 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Kaolin Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Kaolin Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Kaolin Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Kaolin Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Kaolin Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Kaolin Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Kaolin Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Kaolin Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 4,409.5 million → 2032: USD 6,128.17 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Kaolin Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Process - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Waterwashed
- 12.3.7.2 Airfloat
- 12.3.7.3 Calcined
- 12.3.7.4 Delaminated
- 12.3.7.5 Surfacemodified & Unprocessed
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use Industry - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Ceramics & Sanitarywares
- 12.4.7.2 Fiberglass
- 12.4.7.3 Paints & Coatings
- 12.4.7.4 Rubber
- 12.4.7.5 Adhesives & Sealants
- 12.4.7.6 Plastics
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Kaolin End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Kaolin Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Kaolin Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Kaolin Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Imerys S.A.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ashapura Group
- 18.4 EICL Limited
- 18.5 SCR-Sibelco N.V.
- 18.6 KaMin LLC
- 18.7 Thiele Kaolin Company
- 18.8 LASSELSBERGER Group
- 18.9 Quarzwerke GmbH
- 18.10 Sedlecký kaolin A.S.
- 18.11 20 Microns Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

